Payroll GL Posting Validation: Catch Mapping Drift Before Close

Updated: 2 days ago

Three reconciliation results deserve separate checks: a missing payroll run, a wrong department allocation, and a duplicate journal. Each can leave debits equal to credits. Payroll GL posting validation traces the selected payroll events into their final ledger treatment, including accounts, dimensions and accounting periods.
For payroll managers, controllers and accounting leads, the practical test is whether another reviewer can follow the same run from source results to posted accounts, explain every difference, and identify the next action. This guide develops that test through a worked tie-out and a reusable GL Posting Proof Sheet.
The approach is intended for U.S. employer payroll operations, with accounting examples that may also help other teams. It is a control design, not a prescribed chart of accounts or a determination of your accounting policy. Have the accounting owner approve recognition, capitalization, currency conversion and correction treatment for the organization.
Decide what the posting review must establish
Start with five assertions: the selected payroll activity is complete, each event is included once, the accounting classification is intended, the ledger and dimensions are correct, and the posting belongs in the approved accounting period. Balancing debits and credits is a necessary check within that review. It cannot establish the other assertions on its own.
Specify the object under review. A payroll register describes calculated pay; a costing report allocates amounts to accounting combinations; an export or subledger transforms those results; a posted journal affects the ledger. Some systems combine stages, but the reviewer still needs evidence of the transformation and its final effect.
Also separate payroll recognition from settlement. Wages, employee deductions, employer expenses and related liabilities can appear in different entries from the later bank payment. OpenStax's payroll accounting explanation illustrates why employee deductions and employer payroll expenses have different accounting effects. Use that distinction without borrowing its historical tax rates as current payroll instructions.
An accounting export that credits a payroll clearing account will not necessarily equal the bank debit on the same day. Provider fees, separate tax funding, returned payments and payment timing need their own supporting bridge. First establish what the interface is designed to record; otherwise a legitimate difference can trigger a duplicate entry.
Choose the review boundary. For a single payroll and ledger, one run-to-journal schedule may be sufficient. With several employers, currencies, departments or posting routes, use separate schedules for combinations that cannot be meaningfully compared. A consolidated total can hide an equal overstatement in one entity and understatement in another.
State which decision this review supports: authorizing an import, relying on posted payroll expense, closing a period, or accepting a changed mapping. Broader payroll-accounting reconciliation also addresses settlement and closing balances. This guide focuses on whether the source-to-ledger route produced the intended posting, then connects that result to the month-end expense bridge.
Build the run-to-journal population before comparing dollars
Make a run manifest from payroll's finalized activity list, independently of the files already found in accounting. Starting with the available GL files can make a missing file invisible: every file you found may reconcile, while an entire off-cycle remains outside the review.
For each regular run, bonus run, manual payment, reversal, void, retroactive adjustment or costing-only correction, identify the payroll event, its status, its relevant dates and the accounting route. Include events with negative or zero net pay when they create accounting activity. Count the events for each employee, including any additional off-cycle or correction.
Record the legal employer, payroll identifier, reporting currency, earning period, pay date, approved accounting date and extraction timestamp. Keep the actual report filters with the export. Payroll's pay-date report and finance's accounting-period report can be individually accurate while describing different populations.
Create a cross-reference from payroll event to export batch, import or subledger transaction, and posted journal identifier. Mark each event as posted, awaiting processing, rejected, superseded or intentionally excluded with a specific reason. An exclusion should describe where the accounting is handled instead, or why no entry is required. It should not simply say that the event is small.
Compare counts at the right level. Payroll events may expand into employee costing lines and then collapse into summarized journal lines. Different row counts are therefore possible without data loss. Define the expected grouping keys, such as employer, currency, account, cost center and accounting date, then compare monetary totals and coverage at those keys.
Oracle's account analysis reports distinguish posted and unposted results and support tracing summarized GL amounts to underlying subledger detail. That is a useful example of the evidence to request from your own platform. Do not assume that every integration retains the same identifiers or drill-down capability.
Preserve the manifest when the review starts and record subsequent additions as changes. If payroll reopens a run or finance posts a late journal, the original sign-off no longer describes the complete current population. Identify the changed events, repeat the affected checks, and date the supplemental review.
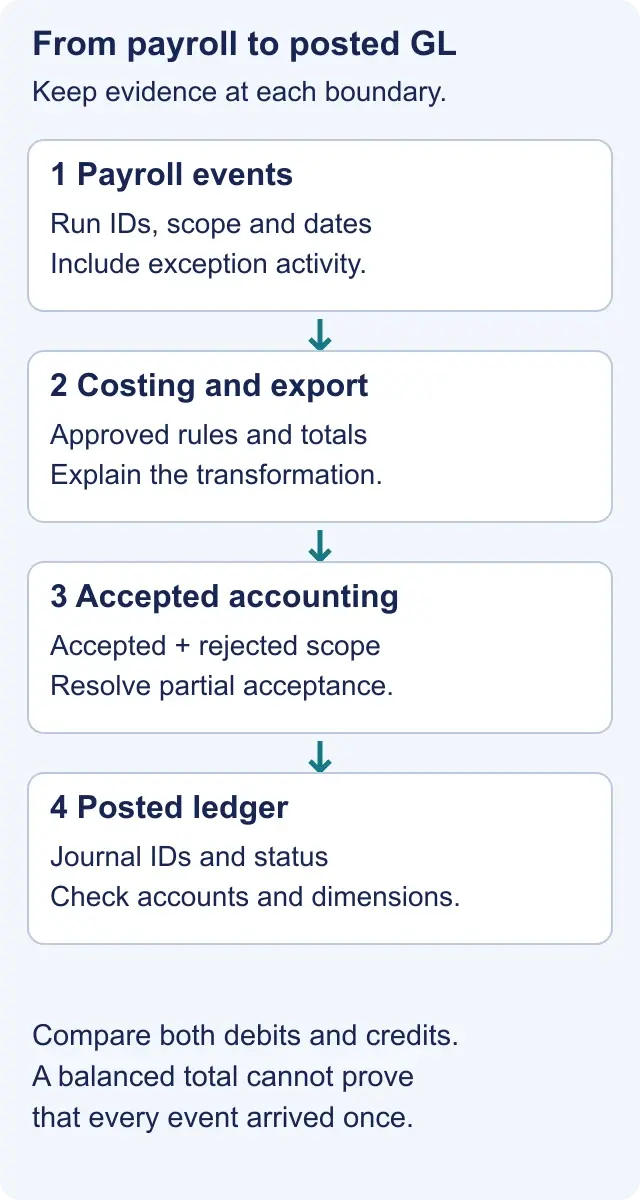
Trace the selected payroll events through each transformation. Reconcile accepted and rejected scope before relying on a posted journal.
Trace the stages without treating a status as proof
At each boundary, compare what was expected to leave with what was accepted. Keep both debit and credit totals, relevant category totals, currency and rejected-item counts. A net-zero batch total can conceal a missing balanced journal or two offsetting errors.
Source results to costing. Confirm that the finalized payroll results were costed, including the categories and exception events in scope. Identify uncosted or rejected results separately.
Costing to accounting output. Tie the approved distribution to the generated accounting lines. Check changes made by export rules, subledger rules, account substitutions and summarization. Retain the version actually used for that batch, not only the configuration visible when someone investigates later.
Accounting output to import. Reconcile the submitted batch to accepted and rejected records. If a loader partially accepts a file, document the accepted subset before repairing and resubmitting anything. A replacement file needs an explicit relationship to the first attempt so accepted lines are not inadvertently included twice.
Import to posted ledger. Find the final journal, confirm its posting status, and tie its accounting lines to the accepted output. An imported or approved journal may still be unposted. Record the ledger, accounting period, journal source and posting timestamp from accounting evidence.
Oracle's Create Accounting parameters distinguish draft and final accounting and separately control transfer and posting. The lesson for a mixed-system environment is to define what each local status means. Do not translate an interface's word “success” into “posted and reconciled” without checking the receiving ledger.
When no usable identifier survives the handoff, create a controlled reconciliation key from retained source attributes and maintain the cross-reference outside the journal. Do not quietly replace missing lineage with a total-only comparison. Tell the accounting owner when the available evidence supports totals only.
For a suspected missing or duplicate transfer, pause automatic or manual retry until the receiver's actual state is known. Search for the original batch and journal references, inspect rejected items, and identify what remains unprocessed. A file name with a new date does not prove that its financial content is new.
Test the effective mapping against intended accounting
Mapping drift is a difference between approved accounting treatment and the rule that actually produced a posting. It can arise from a new payroll code, an effective-date change, a department override, a chart-of-accounts change or a downstream transformation. A mapping file that has not changed is not proof that the resulting account combinations stayed the same.
Build an expected mapping register with the accounting owner. For each relevant payroll element, identify its economic meaning, debit or credit role, intended account, required dimensions, applicable employer and currency, effective dates, overrides and approver. Distinguish employee withholding from employer expense even when the payroll system displays similar labels.
Include employer-paid benefits, taxable noncash items, reimbursements, garnishments and other special categories when present. Their accounting treatment depends on the underlying transaction and approved policy. For example, do not assume that every reimbursement should increase wage expense or that an imputed-income item produces an additional cash payment.
Compare the mapping used by the export with the approved register, then trace selected actual results. Testing only the configuration can miss a downstream rule. Testing only the posted account against the same live mapping can validate an unauthorized change against itself.
For example, assume finance approves a new shift-premium code for wage account 5105, with the employee's approved labor distribution supplying the department. Test a $300 premium split 60% to Support and 40% to Sales. The expected wage debits are $180 and $120 in account 5105, with the payroll event's corresponding credits tested separately. A $300 debit to the old regular-wage account passes the total test but fails classification. A $300 debit to Support passes the account test but fails allocation. These are fictional account numbers and expectations, not a recommended account structure.
Prioritize every new or changed code and account combination, all unrecognized codes, exception run types and important overrides. Add unchanged examples that demonstrate the normal route still works. Document the remaining population and why the selected tests are sufficient for the stated reliance decision; a few samples cannot be described as full-population assurance.
Oracle's cost hierarchy illustrates how account segments can be assembled from several levels, with lower-level values taking precedence. Your test should therefore include the relevant assignment or element override, not just a payroll-level account map. Use the hierarchy documented for your own system rather than applying Oracle's ordering universally.
Investigate fallback behavior explicitly. Ask what happens when a code has no mapping, an account is inactive, a required segment is missing, or a distribution does not total its required allocation. The answer may be rejection, a blank segment, suspense, a default account or another configured treatment.
Oracle's costing account setup documents different outcomes for required and optional segments and for suspense and default configurations. These are product examples, not interchangeable names for a universal clearing process. Capture what your configuration actually does and how those results become visible to the reviewer.
Review both the balance and the activity in fallback accounts. Equal debit and credit errors may leave a zero ending balance. A default department can also be technically valid while violating management-reporting requirements. Give each unexplained fallback item a source reference, owner and resolution date before deciding whether the related posting can be relied on.
Validate dimensions, currency and rounding at their own level
Prove account classification separately from department, location, project, grant, class or cost-center allocation. A journal can use the right wage account and still charge the wrong team. The relevant comparison is the approved allocation at the level finance uses, including blank and default values.
Select a case with a mid-period transfer, a split allocation and an override if those exist. Compare the employee or assignment attributes used for the payroll period with the attributes used to construct the journal. A current HR roster may differ legitimately from the historical assignment that should govern the cost.
Test that allocation percentages produce the expected complete distribution and that rounding is handled consistently. A distribution totaling 100% can still allocate to the wrong departments, so check the identities as well as the arithmetic. Retain enough detail to reconstruct summarized lines without distributing unnecessary employee data in the general close folder.
Keep currencies distinct. Reconcile entered-currency amounts before translated or functional-currency amounts. Record the approved rate source, rate date and conversion method for any translated comparison. Two reports denominated in different currencies cannot be made comparable by labeling the difference “FX” without a calculation.
Where multiple entities share a payroll service or funding account, verify the employer and balancing segments in addition to the bank account. Do not net one entity's overstatement against another entity's shortfall. Have finance determine any intercompany or allocation entries and keep those entries distinguishable from payroll's original posting.
Rounding needs evidence. Identify whether the system rounds at the employee, element, allocation or journal-summary level. Recalculate the expected difference at that same level. Use the organization's approved tolerance and escalation policy; there is no universal payroll-posting dollar threshold that makes an unexplained difference harmless.
A recurring small difference can signal a wrong rate, missing category or systematic allocation error. A large exact offset can signal misclassification. Assess the cause and affected population before deciding that a result is suitable for monitoring. Keep qualitative concerns, including wrong employer or restricted project charges, visible even when the total difference is zero.
Work through a balanced journal with two hidden defects
Run R100 has $100,000 of gross wages, while off-cycle O101 and void V102 add two different accounting events to the same close. These fictional U.S.-dollar figures demonstrate controls; they are not statutory tax rates or a complete accounting model. Finance has approved recognizing wages and employer payroll tax expense through payroll; employee withholding and benefit deductions create liabilities. Net pay is credited to a clearing account and settled through a separate payment entry.
Regular run R100. The finalized payroll amounts are:
Gross wages: $100,000.
Employee tax withholding: $22,000.
Employee benefit deductions: $8,000.
Net pay: $70,000.
Employer payroll tax expense: $9,000.
Off-cycle O101. This separate run has no benefit deduction in the example:
Gross wages: $12,000.
Employee tax withholding: $3,000.
Employee benefit deductions: $0.
Net pay: $9,000.
Employer payroll tax expense: $1,080.
Void V102. This event reverses an earlier included payment:
Gross wages: negative $2,000.
Employee tax withholding: negative $500.
Net pay: negative $1,500.
Employer payroll tax expense: negative $180.
Assume the reversal is appropriate for this fictional accounting cohort. Actual void and tax-correction procedures depend on the payment's state and the applicable payroll requirements.
Expected combined payroll recognition. Wages are $100,000 + $12,000 - $2,000 = $110,000. Employer tax expense is $9,000 + $1,080 - $180 = $9,900. Total expense debits are therefore $119,900.
Credits comprise $77,500 net-pay clearing, $24,500 employee tax withholding payable, $8,000 employee benefit deductions payable and $9,900 employer payroll tax payable. The credits total $119,900. Withholding is already included in gross wages; adding it again to expense would double count that portion of employee compensation.
For clarity, separate tax and benefit liabilities in actual account-level testing even though this illustration aggregates categories. Provider charges, employer benefits, other deductions, settlements and foreign currency are excluded. Reconcile any such items in your real population using the appropriate approved accounts.
Defect one: O101 never posted. Accounting contains R100 and V102, both balanced. The posted expense is $106,820: $98,000 wages plus $8,820 employer taxes. Its debits equal its credits. The run manifest nevertheless identifies missing O101, whose expense effect is $13,080.
The difference is not a $13,080 unexplained accrual or a reason to plug wage expense. Locate O101 in the interface and receiving ledger. If no portion was accepted or posted, correct and process it through the approved route; if acceptance was partial, isolate the missing subset. Retain its journal reference and repeat the population reconciliation after correction.
Defect two: $5,000 went to the wrong department. After O101 is correctly included, all $119,900 of expense is present. However, an old override charged $5,000 of wages to Sales instead of Support. Total wages, total expense and the debit-credit check all pass.
At the department level, expected wages are Sales $40,000 and Support $70,000. Actual wages are Sales $45,000 and Support $65,000. The two $5,000 variances cancel at company level. A finance-approved reclassification debits Support wage expense and credits Sales wage expense for $5,000, preserving total expense while correcting allocation.
The reclassification resolves this period's reporting only. Correct the underlying override with the proper effective date and test a subsequent affected result. If payroll costing must also be corrected, coordinate that route before allowing a later costing adjustment to duplicate the GL reclassification.
Add the accounting-period bridge. Suppose finance also needs a $6,000 ending wage accrual and has reversed a $4,000 opening wage accrual in this period. With the corrected payroll cohort fully posted, wage expense is $110,000 - $4,000 + $6,000 = $112,000. Add $9,900 employer payroll tax expense for $121,900 of combined expense in this deliberately simplified example.
These accrual amounts cover wages only. Finance must separately assess any associated employer taxes, benefits, capitalization or other costs under its policy. The $121,900 result assumes no additional related adjustments; it is not a complete accrual template for every employer.
The proof sheet should now show three distinct resolutions: O101 included once, Sales and Support corrected without changing company expense, and the $2,000 net wage accrual movement supported by two identifiable accounting entries. A single “ties after adjustment” comment would conceal all three.

A department error can cancel at company level. Compare each approved allocation before accepting the total; the figures are fictional.
Explain period bridges without hiding posting errors
Keep a payroll-cohort tie-out and an accounting-period bridge as separate views. The first asks whether every selected payroll event was posted as intended. The second explains why the period's ledger expense differs from that payroll cohort, using supported accounting entries and explicit date differences.
For an expense account, start with the payroll amount assigned to the cohort. Add or subtract the approved items needed to reach the ledger's accounting-period activity: opening accrual reversals, ending accruals, late or early payroll postings, reclassifications and other relevant entries. Show their signs, journal references and affected periods. Reclassifications may net to zero across accounts while remaining important within an account or dimension.
Oracle's transfer setup guidance provides several possible accounting-date bases and separate treatment for reversals and payment costs. Check the actual date rule and any authorized override in your platform. Never assume that the pay date, period end and accounting date are interchangeable.
A late off-cycle belongs on a named bridge line only when its source event, intended period, actual posting state and accounting treatment are established. Give it an owner and a clearing event. Calling an item “timing” does not establish that it will reverse, that the next period contains it, or that the current period is correctly stated.
For accruals, retain the supported estimate, relevant earning period, approval and reversal plan. Oracle's partial-period accrual documentation illustrates that payroll costing can generate estimates as well as actual costs. Identify which entries are estimates and which are actuals before combining them, and check whether the platform creates its own reversal.
When the following payroll posts, match the prior accrual reversal and actual expense to their references. Do not add a manual reversal merely because one was expected; first check whether an automated reversal already posted. Retain the explanation of estimate-to-actual differences rather than carrying the old estimate forward indefinitely.
Balance-sheet liability reconciliation has a different objective: explaining the opening balance, recognized obligations, settlements, corrections and remaining obligation. A wage-expense tie-out cannot establish that taxes or benefits were remitted. Link the posting review to those account reconciliations without representing one as a substitute for the other.
Complete the GL Posting Proof Sheet
Start the GL Posting Proof Sheet with the employer, ledger, currency and reviewed events in section A. Sections B through D connect those events to posted journals and the period bridge. Section E records finance's reliance decision and remaining work. Add supporting schedules for detail; put their locations beside each result so the next reviewer can reproduce it.
A. Population and date basis
Review identifier and accounting period: ____.
Legal employer, ledger and currency: ____.
Payroll source report, filters and extraction time: ____.
Included run and exception identifiers: ____.
Pay-date, earning-period and accounting-date rules: ____.
Excluded or late events, reason and receiving period: ____.
Explain any population change after initial review. A report name without its filters does not define the cohort.
B. Transformation and coverage
Costing version and accounting/export rule version: ____.
Source-to-export debit and credit totals: ____.
Accepted, rejected and superseded batch references: ____.
Posted journal identifiers, status and timestamp: ____.
Source events lacking a final accounting outcome: ____.
Duplicate-event search and summarization keys: ____.
Attach the run-to-journal cross-reference. Reconcile partial acceptance before any resubmission and distinguish unposted imports from posted entries.
C. Classification and allocation
Approved mapping register and effective date: ____.
Changed codes, overrides and combinations tested: ____.
Expected versus actual account results: ____.
Expected versus actual dimension results: ____.
Suspense/default activity and unresolved causes: ____.
Currency, rate basis and explained rounding: ____.
Record the test population and limitations. A sample pass should not be labeled a complete review of untested elements.
D. Period bridge and corrections
Payroll expense subtotal for the defined cohort: ____.
Accrual, reversal and timing lines with signed amounts: ____.
Reclassification and correction journal references: ____.
Expected versus actual ledger-period expense: ____.
Remaining differences, causes and affected scope: ____.
Source fix, period fix and duplicate-prevention owner: ____.
Keep the wage, employer-cost and liability schedules distinguishable. Each correction needs a documented relationship to the original event and any future system-generated adjustment.
E. Reliance and follow-through
Decision: ready, limited reliance or hold: ____.
Reviewer, review time and approved accounting basis: ____.
Unresolved item owner, due date and escalation: ____.
Restrictions on reporting or posting still required: ____.
Retest evidence and next-run result reference: ____.
Final evidence location and access owner: ____.
“Limited reliance” must state what remains usable, what is restricted, and who authorized that decision. It is not permission to ignore a known payroll, accounting, tax or employee-pay obligation.
Correct the failed stage and prevent a second entry
Choose the remedy from the observed failure and the current transaction state. Preserve the original result and failed comparison first. Changing payroll calculations to make a GL report agree can create a new pay or tax error when the original problem was only account allocation.
Wrong source payroll result. Route the issue to payroll's authorized correction process, including any affected payment, employee communication and reporting steps. Assess its accounting effect as part of the correction. A finance-only reclassification cannot resolve an incorrect employee payment or withholding result.
Wrong costing or account derivation. Determine whether the result is still editable, whether a costing adjustment is supported, and whether corrected costing will generate another accounting entry. Oracle's costing correction guidance distinguishes a current-result cost adjustment from changing setup and calculating retroactive costing. Verify the supported route and future-run effect in your own system.
Rejected or missing import. Correct only the unprocessed scope after reconciling acceptance. Retain the original attempt, the rejection reason and the replacement reference. If the receiver's state is uncertain, obtain evidence before retrying; an integration timeout alone is not proof of failure.
Posted accounting error. Have finance approve the correction method, accounting date and references, including whether a reversal and replacement or a reclassification is appropriate. Respect closed-period controls. Do not erase the original journal or silently alter a retained source export to make the history appear consistent.
GL-only repair with a later system fix. Record how the later costing correction will be identified and how finance will prevent duplicate expense or double reclassification. The period fix and source fix may have different owners and dates. Close each only when its own evidence exists.
An adjustment that makes the total equal is not automatically an explained correction. Require the affected event or account population, the cause, the authorized treatment and the final posted outcome. Use an aged differences log for unresolved items; a journal description such as “payroll true-up” does not supply that analysis.
After the repair, re-extract the relevant ledger activity and repeat the failed check plus any dependent totals, dimensions or period bridges. Preserve before-and-after evidence. Repeating an unrelated full payroll approval adds work without showing whether the actual defect was corrected.
Assign the close decision and retain reproducible evidence
Payroll owns the completeness and meaning of finalized payroll events. Accounting owns ledger classification, recognition periods and journal approval. The integration owner explains transformation versions, acceptance and error handling. Name individuals or accountable roles for your environment; outsourcing payroll does not identify who within the employer accepts the accounting result.
Arrange review so that the person changing mappings or posting adjustments does not silently approve the same result. Where staffing makes full separation difficult, have an authorized independent reviewer examine the changed rules, evidence and journal outcome. Document the compensating review rather than claiming a separation that does not exist.
Ready. Finance can use the reviewed payroll posting for the purpose named on the sheet once the population, mapping, dimensions and period bridge are supported. Record the extraction time and any limits on that reliance. Tax filing, settlement and other financial-statement assertions require their own checks.
Limited reliance may be appropriate only when the accounting owner can identify a bounded unresolved issue and authorize a defensible restriction or treatment. State which reporting output is affected and what remains unverified. A wrong entity, unexplained duplicate, missing material run or unknown population generally prevents reliance on the affected posting until addressed.
Hold. Identify the journal import or reporting output that is restricted, the unresolved issue, the action deadline and the person authorized to release it. Keep payroll and funding decisions separate: a GL hold does not authorize delaying employee pay or tax and benefit obligations. Escalate any effect on those obligations promptly.
Keep the proof sheet, source report versions, manifest, mapping approval, actual export, acceptance results, posted journal detail, bridge schedules and review evidence together through controlled references. Limit employee-level access to people who need it. Apply the relevant retention schedule and any hold; duplicating sensitive payroll files into every finance folder is not an evidence strategy.
If a reviewer cannot reconstruct a difference because the export was overwritten, obtain a preserved system result or other reliable evidence and disclose the limitation. Do not recreate a convenient historical file and label it as the original. A contemporary explanation and a system audit trail are different types of evidence and should remain identifiable.
Retest mapping changes and choose proportionate automation
Treat a new earning code, department reorganization, account closure, provider upgrade or export-rule change as a trigger to revalidate the affected route. Record the approved change, effective date and first affected payroll event. Then test the resulting posting, including at least one relevant exception or override where the change can affect it.
Use a small regression set that covers the actual risks: a normal wage, a changed code, a split dimension, a reversal, a separate employer cost and a deliberately invalid combination in an appropriate test environment. Expected results should be defined before the test. Never inject an invalid production journal just to see whether controls reject it.
During a provider or accounting-system change, reconcile the old and new outputs on the same population and accounting basis. Differences in summarization, account labels or timing may be intentional, but each requires an approved explanation. A parallel payroll calculation that matches net pay does not prove the new GL export maps employer costs or department allocations correctly.
Automation is useful when it compares stable keys, retains rule versions and exposes rejected or unmatched items. Start with repeatable checks for missing runs, duplicate event references, debit-credit totals, unexpected account combinations and blank dimensions. Keep a visible exception queue and a reviewer who understands the accounting meaning of each alert.
Do not automate away the expected-result register. If the comparison reads the same changed mapping on both sides, it may consistently approve the wrong account. Preserve the independent approved basis, and require review when a new code or dimension value falls outside it.
For a small employer with one stable route, a well-controlled export and proof sheet may be more maintainable than a complex custom integration. For multiple ledgers or frequent changes, ask providers to demonstrate versioned mapping, exception handling, event-to-journal traceability and correction behavior using your scenarios.
The next close is a useful proving point. Pick one employer and payroll cohort, assemble its manifest, complete the five proof-sheet sections, and track the first real defect through correction and retest. Expand the control after the team can reproduce that result, rather than signing off on a dashboard whose underlying population remains uncertain.
Questions about payroll GL posting validation
Can a balanced journal still be wrong? Yes. A missing balanced run, a duplicated balanced run, wrong account classification or wrong department can all preserve equal debits and credits. Use population, mapping and dimension checks alongside the balance check.
Should payroll gross wages equal the wage expense account? Only after the population, recognition basis and account scope are aligned. Accrual reversals, new accruals, capitalization, separate manual entries or postings in another period can create supported differences. List those items explicitly; do not assume any unexplained difference is an accrual.
Is a suspense balance of zero enough? No. Review the activity, the source events and any default dimensions as well. Offsetting errors or a temporary clearing entry can produce a zero balance while leaving the accounting classification unresolved.
How often should we review the mapping? Validate each posting population at the level needed for reliance, and re-test affected mapping after changes. A broader periodic mapping review can support that work, but an annual review does not address a new code introduced between reviews.
Does a GL reclassification fix payroll costing? It may correct ledger reporting while leaving payroll's costing records and future behavior unchanged. Coordinate the source correction and any later accounting output so the same amount is not corrected twice.
What if the provider only sends a summary? Request a reproducible supporting schedule and clear grouping rules. If event-level lineage cannot be established, record that limitation and have the accounting owner determine what reliance is justified.
Continue with Payroll Operations & Controls. Explore the full Decision Guides library.

About the author
Ben Scott writes and maintains payroll decision guides for founders and operators. His work focuses on execution realities and how decisions hold up under growth, complexity, and controls and documentation pressure. He works hands-on in HR and leave-management roles that intersect with payroll-adjacent workflows such as benefits coordination, cutovers, and compliance-driven process controls.