
Payroll-Accounting Reconciliation: Prove the Run, Posting, and Settlement

Updated: 2d

Payroll can agree with the bank and still be wrong in the books. A duplicate journal can overstate wages while employees receive the right pay. A tax payment can clear the bank while the liability remains on the ledger. Department totals can sum correctly while a cost sits in the wrong department.
Payroll-accounting reconciliation connects three proofs: the complete set of final payroll runs, their posted accounting entries, and the settlement of the resulting obligations. Month-end adds a fourth question: which costs and balances belong in the reporting period?
For finance and payroll teams, the practical decision is how much detail to retain, who checks each connection, and what evidence permits close. The model below uses a run inventory, a worked journal, and a reusable Payroll-to-GL Close Board. It works whether payroll reaches accounting through an integration, a file import, or a manual entry.
The examples assume a U.S. employer and an accrual-based management close. Figures are invented to explain the controls, not actual tax calculations, statutory rates, or product test results. Your accountant should approve the account structure, recognition policy, estimates, and correction entries.
Table of contents
Establish the comparison before opening a spreadsheet
Write a short comparison note at the top of every reconciliation. Include the legal entity, payroll population, pay dates, accounting period, currency, included run types, and the exact report versions. Identify whether each total represents gross wages, net employee pay, employer expense, provider funding, or a liability.
Those amounts answer different questions. Gross wages do not include every employer cost. Net pay has employee deductions removed. A provider withdrawal may combine employee pay, taxes, and fees, or fund transactions that settle later. Comparing two numbers called “payroll total” without defining them creates a difference that arithmetic cannot resolve.
Use final payroll registers as the source for completed runs. A preview can support review before release, but it should not silently replace the final record in the close package. If payroll changes after the export, retain the superseded version and identify the replacement or correction run.
On the accounting side, compare against posted entries and posted account activity. An import file that balances is still only a proposed journal. A successful transmission message is evidence about delivery, not proof that the correct entry appears in the ledger.
Keep the dates separate:
Service period: when employees earned the compensation.
Pay date: when the payroll payment is made.
Posting date and period: where the journal appears in accounting.
Funding or settlement date: when money leaves the employer or reaches the recipient.
For federal employment-tax reporting, this distinction has a specific consequence. The IRS's Form 941 instructions say monthly liability reporting follows the dates wages were paid, rather than when liabilities were accrued or deposits were made. An accounting accrual does not move that tax liability into an earlier month.
Define “pass” before reviewing. A comparable source amount should match its mapped ledger amount after identified, approved reconciling entries. Each remaining difference needs an amount, cause, evidence, owner, and next action. “Close enough” without those fields is a judgment that the reviewer cannot reproduce.
Prove that every final run reached the ledger once
Build one inventory row for every regular run, off-cycle payment, reversal, and correction included in the review. Use a stable run identifier from payroll. Where no stable identifier exists, agree on a reference combining entity, pay date, run type, and sequence, and carry it into the journal description.
Record the final register version, gross wages, employer taxes, net pay, and the expected accounting entry or entries. Add the posted journal identifiers after the import or posting completes. A run can legitimately produce several entries; the inventory should show the complete group and explain their roles.
Count coverage in both directions. Starting from payroll, locate every expected journal. Starting from payroll-related ledger activity, identify the source of every entry. This second pass catches entries that have no corresponding run, including a manual journal left in place after an automated repost.
A monthly summary can work for a simple business if the underlying run detail remains available. Keep a schedule showing how each run contributes to the monthly totals. A single monthly number without that schedule makes a missing run difficult to distinguish from a correction or mapping change.
Prefer run-level posting when the company needs frequent investigation, separate entity records, department reporting, or visibility into off-cycle work. More detail brings more rows to review, so give the reviewer a concise control-total summary and access to the supporting detail.
Example: a balanced duplicate. Run R-104 produced one $43,500 journal. The integration posted it, and a bookkeeper also entered the same amounts manually. Both journals balance. Employees still received only one payment. The inventory must identify the extra journal before anyone tries to explain the doubled wage expense through bank reconciliation.
Review off-cycle payroll as part of the same population. Its urgency can change approval routing, but it should not remove the payment from the run inventory. Give a reversal its own reference and connect it to the original run so the reviewer can see both the original event and its treatment.
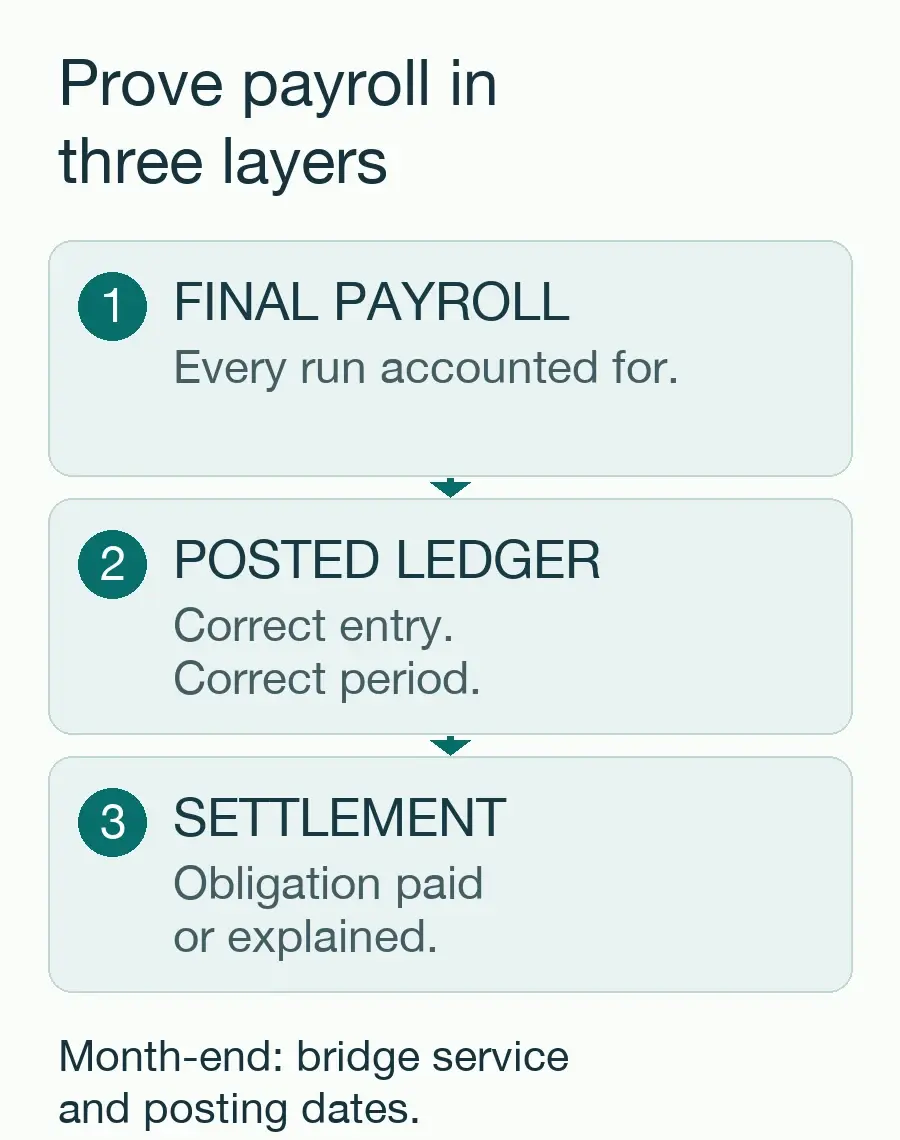
Trace the same run through all three layers. Month-end checks the reporting period across them.
Separate wages, deductions, employer costs, and cash
A payroll journal should express what happened to expenses, obligations, and payments. It should not treat every amount withheld from an employee as a second employer expense.
Consider one fictional run:
Gross employee wages: $40,000.
Employee tax withholding: $10,000.
Employee benefit deductions: $2,000.
Net pay: $28,000.
Employer payroll taxes: $3,500.
For this example, employee deductions reduce gross pay to net pay: $40,000 minus $10,000 minus $2,000 equals $28,000. Employer taxes add a separate cost. The employer expense represented here is $43,500, excluding benefits paid by the employer and any other costs outside the example.
The recognition entry
Assume this company records the obligations before their separate settlement. Its simplified journal has these debits:
Wage expense: $40,000.
Employer payroll tax expense: $3,500.
It has these credits:
Net pay payable: $28,000.
Employee taxes payable: $10,000.
Employee benefit deductions payable: $2,000.
Employer payroll taxes payable: $3,500.
Debits and credits both equal $43,500. The example separates payable buckets to make their later settlement visible. An actual chart of accounts may split tax accounts by agency or combine particular employer and employee taxes into the relevant agency account.
When the $28,000 employee payment settles, the illustrative settlement entry debits net pay payable and credits cash. When a tax payment settles, it reduces the appropriate tax payable. Paying an obligation already recognized should not create the same wage or tax expense again.
An integration may instead credit cash or a clearing account in its payroll journal. Document that route and how settlement entries complete it. Do not copy the example's payable entry on top of an automated entry that already recorded the same obligation.
Intuit's instructions for manually recording outside payroll in QuickBooks Online distinguish wage expense, employer tax expense, liabilities, and net-pay entries. They also warn that manually entering those payment totals does not create the employee W-2 data. Accounting records and payroll tax records need their own reconciliation.
Mapping the detail without losing the total
Write a mapping rule for each earning, employer cost, deduction, reimbursement, and settlement category that reaches accounting. Include the destination account, entity, department or project treatment, and effective date. Assign a person who approves changes.
Reimbursements need their own definition. Determine whether the payroll report includes them within the displayed payment total and how the company records the underlying expense or payable. Do not force them into wage expense merely because they travel with employee pay.
When department or project allocations matter, first prove the company-wide amount, then prove its distribution. The allocated amounts must sum to the approved source. Separately check whether the right amount reached each intended destination.
For example, splitting $40,000 as $24,000 to Operations and $16,000 to Sales preserves the total. Reversing the department labels also preserves it. Compare the allocation to approved employee or time-based support, rather than relying on a total-only check.
A missing dimension should create an exception with an owner. Sending every unmapped item to a default department can make the journal look complete while weakening budget and margin reporting.
Bridge the service period to month-end
A pay period can cross a month boundary even when the journal correctly follows the pay date. Finance needs a separate recognition policy for costs earned but not yet recorded in the reporting period.
Use a schedule that identifies the service period, applicable employees, estimation basis, accounts, posting period, reviewer, and reversal method. Your accountant should decide which costs to accrue and how to measure them. Do not assume a provider's pay-date journal independently produces the company's accrual-based month-end result.
Illustrative cutoff case: a payroll paid in early October includes $20,000 of wages and $1,600 of employer tax cost. The approved estimate for the portion earned through September 30 is $12,000 of wages plus $960 of employer taxes. These amounts are assumptions, not a prescribed allocation method or tax rate.
Under the assumed reversing-entry policy:
September records $12,000 wage expense and $960 employer tax expense, with corresponding accrued payroll liabilities.
October reverses that September accrual.
October records the complete actual payroll journal, including $20,000 wages and $1,600 employer taxes.
October therefore retains $8,000 wages and $640 employer tax expense from these entries, assuming the estimate equals the actual September portion.
The September and October expenses together equal the full $21,600 cost. If the estimate differs from the actual September portion, finance needs an explicit true-up under its accounting policy. It should not hide that difference by changing the final payroll register.
Reconcile the accrual separately from tax and benefit remittance accounts. The estimate recognizes an accounting cost; it does not establish that employee withholding occurred on September 30. Keep the service-period bridge distinct from the paid-wage tax-reporting bridge.
Record the reversal identifier in the schedule. A missed reversal can duplicate expense when the actual run posts. A reversal in the wrong period can leave one month overstated and another understated while the year-to-date total looks plausible.
Set a cutoff for late journals and corrections. If accounting reopens a closed period, update the reconciliation version and obtain another review of the affected schedules. If the correction is posted in a later period under approved policy, show that treatment rather than presenting the earlier close as though nothing changed.
Match settlement to the obligation it actually reduces
For each payment, identify the recipient, amount, payment reference, related obligation, settlement evidence, and ledger entry. A bank debit establishes that money left the bank. Additional evidence may be needed to establish which tax agency, benefit provider, or employee received it.
When a payroll provider first collects funds from the employer, distinguish funding from final remittance. A prefunding withdrawal should not automatically be labeled “taxes paid to the agency.” Follow the company's approved accounting treatment and retain evidence showing where the funds are in the process.
Some companies use a clearing account to connect grouped provider withdrawals with individual payroll obligations. Write down which transactions enter that account and what settles each one. Other companies can match direct payments without a separate clearing account. Choose the route that permits clear tracing for the actual payment model.
A clearing account need not be zero on every reporting date. It may contain supported timing items. The requirement is an itemized explanation of the balance, with expected clearing dates and evidence, rather than a journal that forces it to zero.
An outstanding payment is not automatically an error
Suppose a $900 employee check has been recorded but has not cleared the bank. If the check remains valid and supported, it is a bank reconciliation timing item under the company's process. Do not issue another payment solely because the withdrawal is absent.
If the original payment was returned, rejected, voided, or replaced, connect those events before clearing the item. A replacement check and a returned deposit can occur on different dates. Review both the employee-pay status and the accounting treatment so a tidy ledger does not conceal an unpaid employee.
Watch for double expense through the bank feed
If payroll already recognized wage expense and a payable, categorizing its bank settlement as wage expense again duplicates the cost. Match the cash event to the existing obligation or approved clearing route.
If a bundled withdrawal includes a service fee, separate that fee from payroll obligations according to the invoice and account policy. Otherwise, the team may repeatedly “solve” a small reconciliation difference by leaving it in a tax account, even though it belongs elsewhere.
Explain liability balances with a rollforward
For each material payable category, calculate:
Opening balance + new obligations - settlements + signed corrections = expected closing balance.
Compare that result with the ledger closing balance. A positive correction increases the obligation; a negative correction decreases it. Explain corrections separately from normal payroll additions and payments.
Use this fictional tax-payable example, with all settlements assumed to be direct, supported agency payments:
Opening payable: $3,000.
Employee withholding plus employer taxes from the run: $13,500.
Supported settlements recorded during the period: $12,500.
Corrections: $0.
Expected closing payable: $4,000.
The $4,000 is not automatically an overdue balance. Identify which obligation remains, its relevant due date, and why it is still payable. Those facts determine whether it is normal timing or a problem requiring action.
If the GL shows $5,500 instead, investigate the $1,500 difference. Suppose a confirmed $1,500 agency payment cleared the bank but was omitted from both the payment schedule and ledger. Include it in the schedule and record its approved settlement entry. Total settlements become $14,000 and the expected payable falls to $2,500, while the ledger falls from $5,500 to $4,000.
That result still leaves a $1,500 variance. The newly found payment alone did not explain the original difference because it was missing from both sides. Continue investigating the original ledger-to-schedule mismatch. Do not call an item resolved merely because its amount equals the variance.
By contrast, if the $12,500 schedule already included that payment but the ledger omitted it, correcting only the ledger lowers $5,500 to the expected $4,000. The reconciliation passes when both the cause and the two sides of the comparison are established.
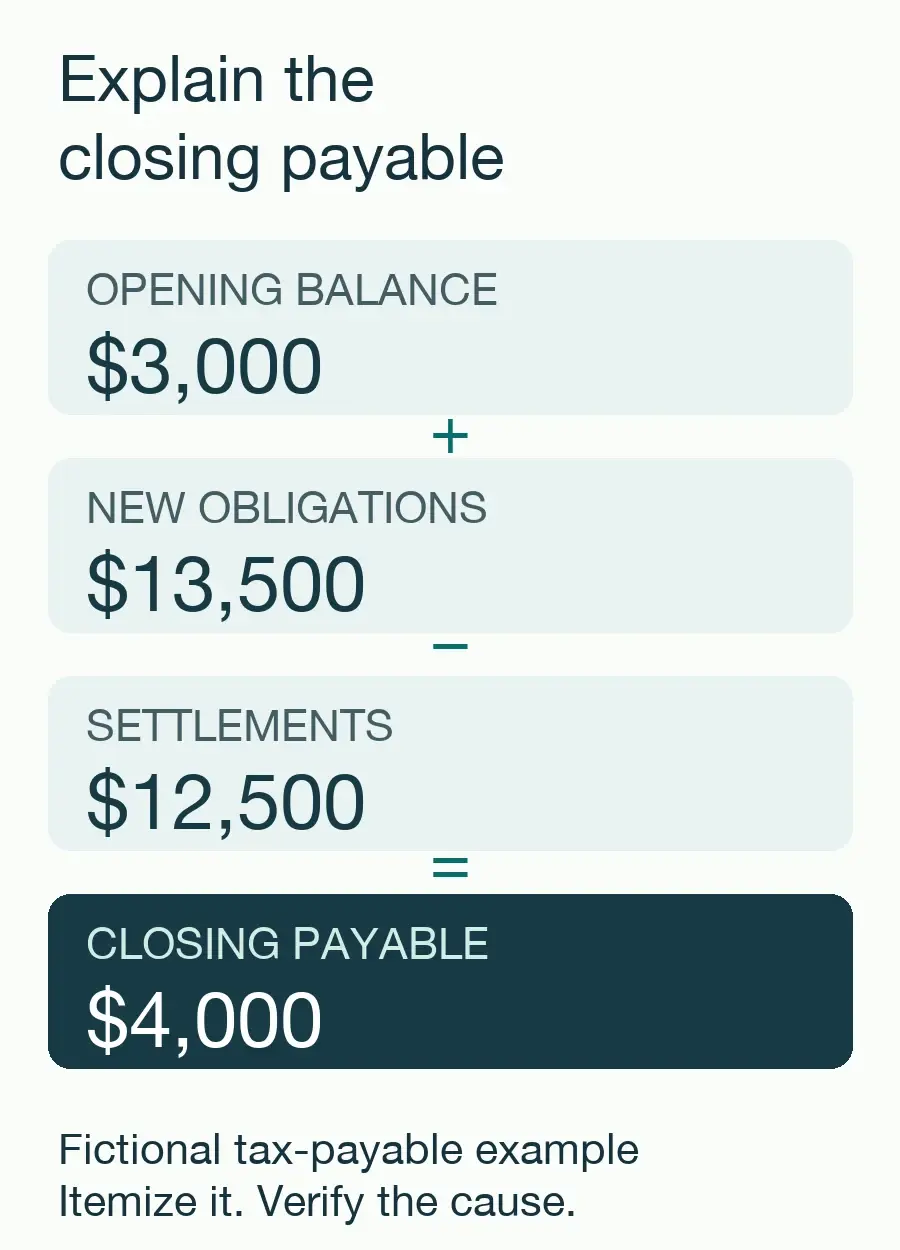
The $4,000 balance needs an itemized explanation. An equal-sized payment is not proof of the cause of a variance.
Build separate schedules for obligations whose evidence or payment route differs. A tax account, benefit deduction account, and employee-pay account can have different recipients, due dates, and settlement documents. Combining them into one unexplained payroll liability defeats the purpose of the rollforward.
For Form 941 filers, liability and deposit reporting are also distinct: line 16 is a liability record, not a deposit summary. At year-end, use the relevant payroll and tax-reporting reconciliation rather than expecting every accounting wage total to equal every tax-form box.
IRS Publication 15 explains the Form W-3 comparison with employment-tax returns. Those returns include employer and employee Social Security and Medicare taxes, while Form W-3 reports the employee amounts; Additional Medicare Tax has no employer share. Retain a reasoned bridge for valid differences rather than forcing an incorrect match.
Use the Payroll-to-GL Close Board
Complete one board for each entity and accounting period in a worksheet or close task. For every block, record whether the comparison is complete, a supported item remains open, or work prevents release.
Mark a block Ready after its comparison passes with evidence. Use Explained open item for a supported timing or policy-approved item, recording its owner and next action. Mark Hold when the comparison is unresolved or a correction, evidence, or approval is missing. The close lead decides whether documented open items permit release under the company's policy.
1. Population and version
Owner: payroll prepares; finance reviews coverage.
Check: every included final run, reversal, and correction has a reference, source version, and corresponding accounting treatment.
Evidence: run inventory and final registers, linked to the posted journal identifiers.
Record: entity; period; included pay dates; run count; unmatched runs or entries; preparer; reviewer; status.
Hold when: a preview replaces final data, a run has no accounting treatment, or an unexplained journal has no source.
2. Entry and mapping
Owner: finance prepares; the designated accounting reviewer approves.
Check: debits equal credits, expense and payable totals tie to defined source amounts, and allocations reach approved accounts and dimensions.
Evidence: posted entry detail, source control totals, effective mapping rules, and allocation support.
Record: journal identifiers; account totals; dimension exceptions; mapping version; correction identifiers; reviewer; status.
Hold when: a balancing line has no business explanation, an entry is duplicated, or a missing dimension is concealed in a default account.
3. Period recognition
Owner: finance, with the accountant-approved close policy.
Check: the service-period schedule explains costs crossing month-end, and the accrual and reversal appear in their intended periods.
Evidence: estimation basis, approved accrual, posted reversal, actual payroll comparison, and any true-up.
Record: service dates; estimated and actual amounts; posting periods; reversal identifier; estimate variance; reviewer; status.
Hold when: the policy is unclear, the reversal is missing, or the estimate was changed merely to make payroll and accounting appear equal.
4. Cash and clearing
Owner: treasury or the bank-reconciliation owner, coordinated with payroll.
Check: every payment or funding movement has the correct accounting route, and each open clearing item has a specific explanation.
Evidence: bank activity, provider funding detail, recipient settlement confirmation where applicable, and return or replacement records.
Record: payment references; obligations settled; funding still awaiting remittance; open-item amounts; expected clearing dates; owner; status.
Hold when: a bank debit is treated as final remittance without support, a replacement could duplicate pay, or an unknown balance is forced to zero.
5. Liability and filing bridge
Owner: finance prepares; payroll or the tax-filing owner confirms the relevant reporting basis.
Check: each material liability rollforward agrees with the GL, with identified remaining obligations and applicable reporting differences.
Evidence: opening detail, payroll additions, supported payments, correction records, closing detail, and the relevant tax-reporting reconciliation.
Record: account; expected balance; GL balance; variance; remaining obligation; due date; supporting reference; reviewer; status.
Hold when: a difference has only a vague “timing” label, a payment lacks the correct period or recipient, or unlike tax-form amounts are forced to agree.
6. Exceptions and close release
Owner: the close lead reviews the completed board and unresolved issues.
Check: each exception has a cause, affected records, amount, approved treatment, owner, due date, and closure evidence.
Evidence: issue log, correction entries, payroll case references, supporting confirmations, and the reviewed close package.
Record: unresolved issue IDs; effect on reporting or employee pay; approved open items; escalation decision; final reviewer; review date.
Hold when: unresolved work could change the reported amount or payment status and the authorized reviewer has not approved its treatment.
Use the board as a control matrix with explicit responsibilities, not a request for everyone to approve everything. In a small business, an owner or external accountant may provide the second review. Where one person performs several tasks, document the compensating review rather than inventing a segregation of duties that does not exist.
Route exceptions by the record that is wrong
Start with the first failed connection. A missing journal requires a different response from wrong employee pay or an unsettled tax payment.
Correct source, wrong ledger: investigate posting status, duplicate imports, mapping, account selection, or period. Obtain an approved accounting correction and repeat the affected tie-out. Do not alter correct payroll data to accommodate the books.
Wrong source payroll: route the case through payroll's correction process. Identify employee, tax, payment, and reporting consequences before deciding which entries to adjust. An accounting journal alone cannot repair the employee's payroll record.
Correct obligation, failed settlement: determine whether funds were returned, a payment was rejected, or remittance remains incomplete. Coordinate payment resolution with payroll or treasury and retain confirmation of the eventual result.
Supported timing difference: identify the specific event and expected resolution date. Check it at that date. A balance that was reasonable last month needs current support if it remains open.
Unknown difference: preserve the evidence, assign the investigation, and escalate according to the company's close and error policy. A small dollar amount does not justify ignoring possible employee underpayment, an unpaid agency obligation, or a recurring control failure.
Keep a record of each correction's effect on both sides. If an entry is deleted or reversed, connect it to the original identifier. Reconcile the corrected posted ledger, not the journal that someone intends to post tomorrow.
Close the issue only when its owner can show the corrected source, posting, or settlement and the repeated comparison passes. Retain the investigation even when no entry is needed; the explanation may be essential during the next review.
Decide whether to repair the process or replace the posting path
Choose a manual model when payroll is simple, the entry volume is manageable, and a reviewer can reliably trace each run and payment. Keep the source-to-journal references and approved mappings. Manual work becomes risky when exceptions depend on memory or one person's undocumented adjustments.
A file import can reduce rekeying, but it still needs validation for rejected rows, duplicate uploads, date handling, and missing dimensions. Require evidence of what actually posted. Save the import version and rejection report beside the final journal.
An integration can reduce routine handling when it supplies the needed detail and a usable correction route. Before relying on it, ask the vendor to demonstrate a normal run, an off-cycle run, a reversal, a changed department, and a period boundary. These are evaluation requests, not claims that a particular product passes them.
Repair the process first when reports and entries are available but ownership, definitions, or review timing are weak. Consider changing the posting path when required detail is inaccessible, failures cannot be traced, or repeat manual work persists despite a stable control design.
During a payroll provider cutover, specify which system supplies each period's runs, balances, and tax records. Compare opening liabilities and first posted entries before treating the new connection as routine. A successful first import does not settle historical obligations.
A first-month implementation sequence
Before the next run, assign owners, define the comparison note, and build the run inventory. At the next posting, complete the entry and mapping block with actual journal identifiers. After settlement, match payments and itemize clearing balances.
At month-end, add the accrual bridge and liability rollforwards, then have a second person review the complete board. Use the first close to identify missing evidence or unclear responsibilities. Improve those specific controls before adding more spreadsheet columns or changing software.
The recommendation is a traceable model matched to the company’s actual complexity: every run accounted for, every posted total explained, every remaining obligation supported. Release close through the completed board and the authorized review of any open items.
Questions finance and payroll teams ask
Does a balanced journal prove reconciliation?
No. It proves equal debits and credits in that entry. Population completeness, account selection, allocations, period recognition, and settlement still need their own evidence. A duplicate balanced entry is an error even though it passes the arithmetic check.
Should clearing be zero at month-end?
Only when the company's transactions and timing support that result. An itemized, documented outstanding balance can be appropriate. An unexplained zero created through an unsupported adjustment is weaker evidence than a supported open item.
How frequently should these checks happen?
This model recommends source-to-posting checks for each run, cash checks as settlement occurs, and a full period review at month-end. Add quarterly and annual tax-reporting checks on the applicable filing basis. This is an operating cadence, not a replacement for statutory payment or filing deadlines.
Can the bank withdrawal replace the payroll register?
No. It can include different obligations, fees, or funding movements, and it does not establish earning or deduction detail. Use the register to explain the payroll event and the bank evidence to explain the cash movement.
What should the reviewer retain?
Keep the completed comparison note and close board with final reports, posted entries, rollforwards, payment support, exception resolutions, and review evidence. Link related records so another person can reperform the checks. Apply the retention rules relevant to each record category.

About the author
Ben Scott writes and maintains payroll decision guides for founders and operators. His work focuses on execution realities and how decisions hold up under growth, complexity, and controls and documentation pressure. He works hands-on in HR and leave-management roles that intersect with payroll-adjacent workflows such as benefits coordination, cutovers, and compliance-driven process controls.
Browse the Payroll Operations & Controls hub, explore all decision guides, or use Payroll Templates & Resources.


