
Payroll Software for QuickBooks: Prove the Posting Before You Buy

Updated: 2 days ago

A payroll service sends a green success message, but the bookkeeper cannot find the wages in the intended company file. Another connection creates a balanced entry while placing every employee in the same department. Both can be described as working integrations. Neither proves the accounting result the buyer needs.
Before choosing payroll software for QuickBooks, specify the exact connection and ask it to produce a traceable posting in the intended file. Reconcile a normal run, a meaningful correction and the associated funding records. Decide who will do the remaining work before treating compatibility as a reason to buy.
This guide is for U.S. employers and their finance reviewers evaluating a payroll-to-QuickBooks posting route. It includes a fictional posting example and a reusable QuickBooks Posting Trial Card. The examples are fictional, and this guide does not report a hands-on test of a named payroll connection. Have the accountant approve the actual account structure and treatment for the company.
Table of contents
Specify the connection you are actually buying
Write down the QuickBooks product, country version, subscription, company file and payroll product on the same page. QuickBooks Online and QuickBooks Desktop are different destinations. A sales answer about one does not establish support for the other, and a connector's name alone does not identify which company will receive the transactions.
Distinguish payroll attached to the accounting product, a separate payroll service with a direct connection, and a file export that someone imports. Record any intermediate connector and the party responsible for its setup, fees and support. An export can be usable, but the person checking and importing it is part of the operating process.
Intuit's standalone payroll export instructions describe direct export to QuickBooks Online and an IIF export/import route for QuickBooks Desktop. They also state that standalone payroll cannot export to a QuickBooks Online account that already has payroll. That is a restriction on the documented Intuit route, not a rule covering every third-party connection.
The same instructions require the Primary Admin to set up that export and describe an additional restriction for a Primary Admin who is a Firm user. Confirm the applicable setup role before arranging a trial. Do not assume the employee who runs payroll can also authorize the accounting connection.
Ask what records are transferred: summarized accounting entries, individual paychecks, tax payments, contractor payments, time or employee information. Record excluded items explicitly. The accountant needs to know whether the posting records an obligation, its payment, or both. A connection that sends wages does not necessarily send the later liability payment.
Intuit's manual third-party paycheck guidance explains that a manually entered payroll journal tracks payment totals but does not create the employee W-2 data. Keep the accounting transfer separate from responsibility for payroll calculations, tax filings and year-end forms.
Agree on when the transfer starts. Is it triggered by payroll submission, final processing, a scheduled task or an operator action? Ask for an expected availability time and the person who checks for missing output. Include how a failed authorization or unavailable company file is reported. A screenshot taken just after clicking Connect answers none of those timing questions.
Finally, define the demonstration environment. Use authorized test access and fictional data when available. If a safe test environment cannot reproduce an essential event, ask for documented provider evidence and keep that limitation visible. Do not create a real payment, tax instruction or destructive accounting change just to obtain a demonstration.
Reconstruct one pay run in the company file
Give the provider a small expected-result example before the demonstration. Identify the account names or identifiers finance expects, the reporting period, necessary departments and the records that should support the posting. This makes a missing field observable rather than leaving the reviewer to interpret a finished entry.
Consider a fictional run with $10,000 gross wages, $2,000 employee tax withholding and $300 employee benefit deductions. Net pay is $7,700. Add $800 employer payroll taxes and $200 employer benefit contributions. The employer's payroll cost in this example is $11,000. These are supplied trial amounts, not tax rates or a calculation for an actual employee.
For this trial, assume finance approves a recognition entry that debits wages expense $10,000, employer payroll-tax expense $800 and employer benefit expense $200. The credits are net-pay clearing $7,700, tax payable $2,800 and benefits payable $500. Both sides total $11,000.
Employee withholding and employee benefit deductions are already included in gross wages. Recording them as additional employer expenses would overstate this example's cost. The liability amounts instead explain where the withheld portion of gross pay will go. Employer contributions are separate costs and also contribute to the amounts payable.
The clearing-account design here is a fictional acceptance target. Actual services may post directly to a bank account or use a different approved settlement structure. Finance should supply the expected account treatment for the route being demonstrated, rather than copy this entry into live books.

In this fictional trial, $11,000 of employer cost equals $7,700 net-pay clearing plus $2,800 tax payable plus $500 benefits payable. The allocation is an accounting example, not a tax calculation.
Follow the posting to the report finance uses
Open the resulting QuickBooks transaction and the relevant report, not just the connector's success screen. Match the company, date, source-run reference, total and account distribution. Save the transaction identifier and the report settings so a second reviewer can reproduce the result.
Check gross wages separately from net pay. Confirm that employer costs appear in the intended expense accounts and that deductions remain explainable as liabilities or other approved accounts. A balanced $11,000 posting to the wrong account still fails the agreed example.
Intuit documents customizable payroll accounting preferences for its own QuickBooks Online Payroll transactions. A different service needs its own demonstrated mapping method. Ask who can change the mapping, what happens when an account is inactive and whether an unknown pay code is rejected, held or sent to a default.
Test one earning or deduction that is not already covered by the default map. A new reimbursement, benefit contribution or correction code can expose a fallback that the ordinary salary run never exercises. Require an explanation of that code's intended accounting treatment and the record that shows it was applied.
Reconcile funding without recording the cost twice
Now assume the fictional provider withdraws $10,600: $7,700 for net pay, $2,800 for taxes and a separately documented $100 service fee. The $500 benefit obligation will be paid separately. The withdrawal is not the same amount as the $11,000 payroll cost and does not replace its expense-and-liability detail.
Under this example's clearing design, settlement reduces net-pay clearing by $7,700 and tax payable by $2,800; the separate $100 fee is an expense. The bank credit is $10,600. The benefit liability remains $500 until its separate payment is accounted for. Obtain the funding breakdown instead of forcing the withdrawal into one wage-expense line.
Intuit's guidance on matching existing bank records warns against creating a new transaction when an existing record should match. During the trial, establish which accounting record represents the downloaded withdrawal and how finance will match or otherwise reconcile it without adding the payroll cost again.
Not every route creates the same bank records or supports the same matching workflow. Have the demonstrator show the actual supported method, including grouped funding, separate fees and an amount that does not match the first suggested record. Do not accept an invented adjustment that makes the bank amount agree while leaving the underlying obligation wrong.
Ask the connection to fail and recover once
An ordinary run shows the intended path. A controlled exception shows whether the team can recover without guessing. Choose a correction representative of the employer's real payroll, such as an off-cycle payment, a void-and-reissue sequence or a changed department allocation. Identify which records should change and which should remain intact.
Ask the provider to distinguish a replacement, a reversal and an additional payment. Record the original payroll identifier, the correction identifier and the expected net accounting effect. Two positive entries can be correct for two payments and wrong for a replaced payment. Similar dates and amounts do not settle that distinction.
Test what happens when a transfer appears to fail after some output may already have reached QuickBooks. Before retrying, search the intended file for the original event and inspect the connector's history. Ask whether a retry updates an existing record, creates another one or requires a controlled manual recovery. Obtain that behavior from the specific route; do not assume every connector prevents duplicates.
Separate a mapping rejection from a missing posting. If the record exists under a default account, retransmitting it may compound the problem. If nothing was created, the next action may be a retry after correcting the cause. The acceptance evidence should identify the failure, the permitted action and the final accounting result.
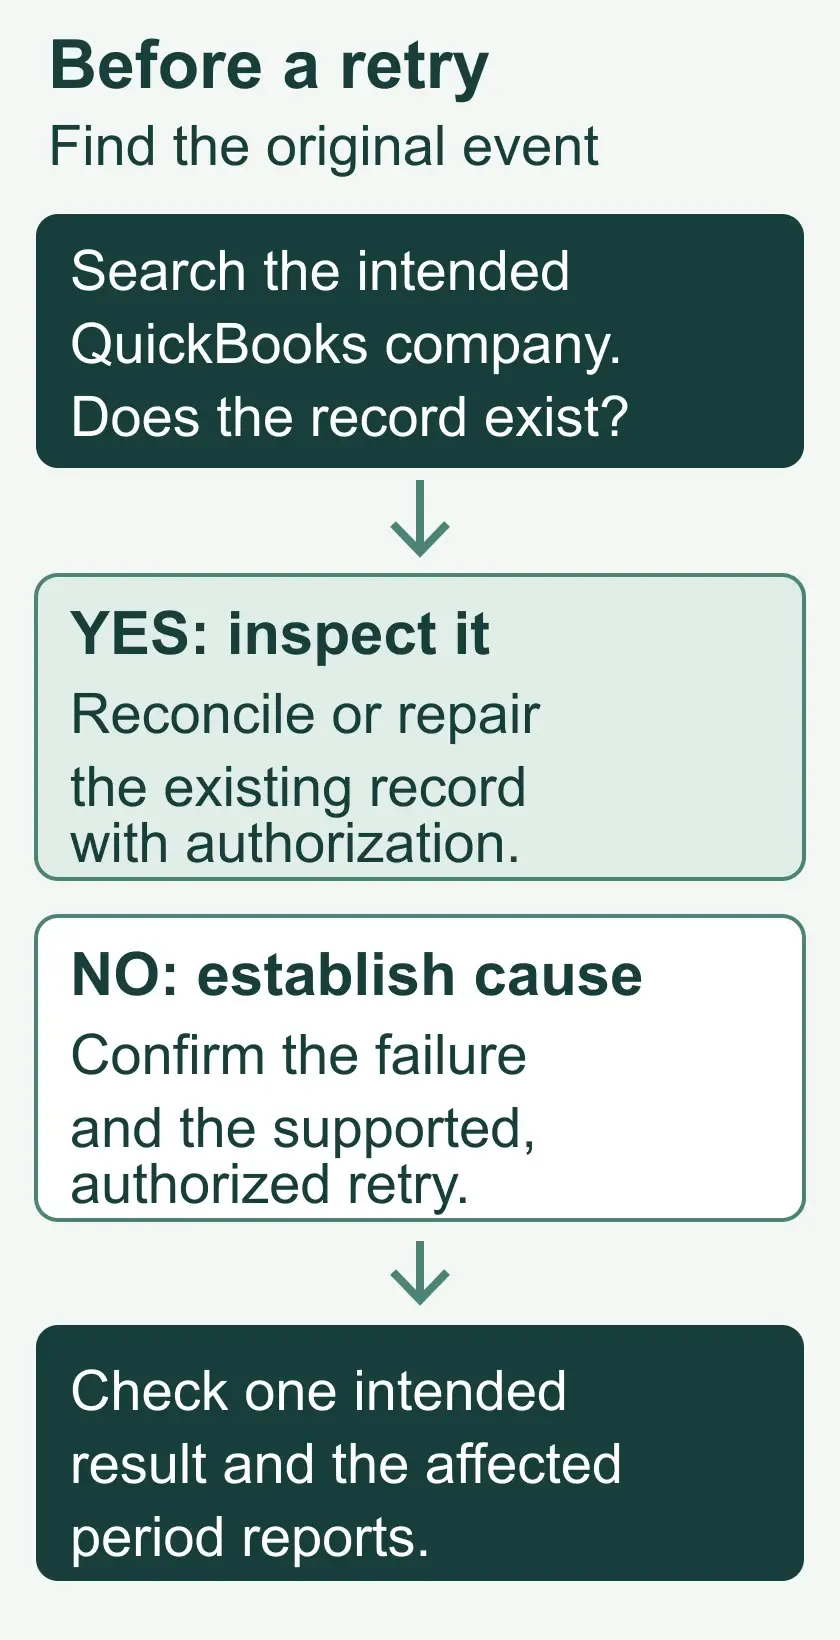
Search for the original event before replaying it. A missing record and an existing incorrect record need different recovery actions.
Include a prior-period correction if that event matters to the business. Intuit's QuickBooks Online closing-date settings can require a warning or a password for changes, depending on configuration. Ask the accountant to approve the correction period and have the provider demonstrate the supported behavior; do not remove the close protection merely to make an import succeed.
Intuit also documents an Exceptions to Closing Date report for reviewing changes after closing. Decide which person will review affected periods and reports when a historical transaction changes. A posting status of complete does not establish that the already issued financial reports remain appropriate.
Use QuickBooks history alongside the payroll and connector records. Intuit says third-party app changes appear as System Administration events in the Online audit log. That label alone does not identify the person who approved a payroll correction. Retain the instruction and the cross-system reference that explain why the app changed the transaction.
Make department reporting a separate acceptance task
A correct company total can conceal an unusable departmental result. If finance needs a class, project, job or location, specify that exact requirement. Similar labels in payroll and accounting are not proof that the same dimension reaches the same report.
Intuit's class-tracking setup documentation identifies QuickBooks Online Plus and Advanced for Online class tracking. Its payroll instructions describe assigning the same class to employees or different classes to different employees. Verify the actual accounting and payroll subscriptions in the proposed configuration before assuming a class setting will be available.
A separate Intuit article describes paycheck allocation by classes and projects in QuickBooks Online Payroll Premium and Elite. It distinguishes salary percentages, hourly hours and dollar allocations for commission or other pay types. This is documented product-specific behavior, not evidence that a third-party connector transfers the same detail.
For a useful trial, put two employees in different departments and have one employee work across both. Check the company's total first, then the department report. Identify whether wages, employer taxes and benefits follow the same allocation rule, different rules or a manual finance allocation.
Include a mid-period assignment change. Ask whether the posting follows the employee's current department or the allocation associated with the original work. Require a report showing the intended outcome. A correct employee default at setup can still produce the wrong historical cost distribution.
Do not assume changing a setting repairs the past. Intuit's class-tracking guidance says enabling class tracking applies to new and future payroll transactions. Its accounting-preference article provides a separate past-transaction reclassification route, excludes bank accounts from that account change and notes a 200-transaction limit per date range. Confirm which supported action fits the actual correction instead of extrapolating from a new-run setting.
If the route cannot supply an essential dimension, describe the workaround precisely. Who prepares the allocation, what source supports it, who approves it and which report confirms it? Reject a proposed workaround that requires payroll to invent a distribution that the time or cost records do not support.
A correction that changes allocation without changing pay
Suppose the trial's $10,000 wages were initially reported as $7,000 Operations and $3,000 Support. Approved time records show the intended distribution was $6,000 and $4,000. The required correction moves $1,000 between those departments without changing total wages or creating another employee payment.
Ask the demonstrator to show the supported correction and both department reports. Check that the original and revised transaction references explain the movement, that company wages remain $10,000 and that no additional funding instruction was created. If employer taxes or benefits also need allocation, specify their approved treatment separately; this wage example does not prescribe their distribution.
A current employee-class change is not enough evidence for this case. The buying question is whether the particular route can produce the approved historical reporting result, or whether finance must perform a documented reclassification. Record that limitation and its recurring workload before accepting the connection.
Record four decisions on a Posting Trial Card
The QuickBooks Posting Trial Card captures the acceptance result of one proposed configuration. Copy it into the evaluation record and repeat it when the company file, route, mapping or essential reporting requirement changes. It is a buying and implementation acceptance tool, not a substitute for the recurring payroll close process.
Copyable trial record
Configuration: QuickBooks product, country version, subscription and company file; payroll product and any intermediate connector: ____________________.
Route owner: Who authorizes the connection, triggers the transfer, monitors it and owns a failure; automatic or manual steps: ____________________.
Trial identity: Payroll run/version, pay date, source amounts, posting date and correction event being demonstrated: ____________________.
Approved output: Account map, required dimensions, expected transaction types and the finance reports used for acceptance: ____________________.
Created records: QuickBooks transaction references, connector history and evidence that the intended event reached the file once: ____________________.
Amount comparison: Gross wages, employer costs, deductions, net pay, liabilities and any explained differences: ____________________.
Settlement comparison: Funding components, bank record, fees, separate payments and any balance legitimately still outstanding: ____________________.
Recovery and reporting: Exception tested, original-versus-corrected result, effect on periods and department reports, unresolved limitations: ____________________.
Buying decision: Accepted route, named manual conditions, evidence still needed or rejected requirement; finance approver and decision date: ____________________.
Four decisions to make from the evidence
Destination and scope: Did the supported route send the required records to the exact company file, with the expected timing and authorized access?
Accounting result: Can finance reproduce the approved account, amount, period and dimension comparisons from the created QuickBooks records?
Recovery result: Does the selected exception have a demonstrated, authorized path to a correct result without an unexplained duplicate or historical change?
Operating commitment: Are all manual steps, monitoring duties and essential limitations accepted by named owners before purchase?
Do not average these decisions into a score that hides a missing essential result. Mark the configuration as accepted, accepted with specified operating conditions, awaiting essential evidence or unsuitable for the requirement. A demonstration promised for after signing remains an unresolved condition.
Keep the supporting register, posting output, report settings and recovery evidence with the card. Use restricted payroll storage for employee-level detail. The purchasing record can identify where that evidence is held without copying sensitive employee information into an unrestricted vendor-comparison document.
Price the work that the connector leaves with finance
The subscription quote is only part of the purchase. Ask finance to estimate the recurring steps shown by the trial: exporting, validating, importing, allocating departments, matching funding, correcting exceptions and monitoring failed transfers. Include the accounting subscription or connector charge needed for the agreed configuration.
Use measured trial effort where available and label estimates where it is not. Avoid assigning zero minutes to a task simply because the salesperson calls the connection automatic. Conversely, a predictable manual import with a clear owner may be preferable to a direct connection whose unexplained failures regularly reach close.
For a fictional cost comparison, suppose routine transfer review takes 12 minutes for each of 52 weekly runs. That is 624 minutes. Two correction reviews per month at 25 minutes each add 600 minutes. Four mapping reviews at 40 minutes add 160 minutes. The total is 1,384 minutes, or 23 hours and four minutes annually.
At an illustrative loaded labor rate of $45 per hour, that workload costs $1,038 per year. It is an operating estimate, not a software price or promised saving. Replace the frequencies, minutes and rate with the employer's evidence, and include additional work if the trial revealed it.
Give each workaround a trigger and an owner. If an employee changes departments, who checks the mapping? If a correction is issued, who confirms the revised posting? If a task depends on one bookkeeper's memory, record the coverage arrangement before treating the configuration as dependable.
Use the card to compare acceptable routes on the same required outcome. One may preserve more detail automatically but need a higher accounting subscription. Another may need a scheduled import but provide the exact reports finance uses. The choice depends on the demonstrated result and accepted work, rather than on the presence of a marketplace badge.
Set up the first live close to confirm the decision
The accepted trial should become the starting point for implementation. Preserve the configuration, account map and examples that were approved. Name the last payroll handled by the old route and the first payroll handled by the new one. Specify whether historical transfers are excluded or require a separate controlled plan.
Do not use a fresh connection to import an unspecified historical range. Compare the proposed range with transactions already in the file, including manual entries and outputs from the outgoing service. Assign responsibility for opening liabilities and clearing balances so a new posting does not silently recreate an old obligation.
For the first live run, compare the actual register with the agreed account and dimension output, then confirm funding and exception handling. Review the first close report finance actually relies on. If the live result differs from the accepted demonstration, record the first unsupported difference and the action required, rather than approving the configuration because employees were paid.
Retain access to the outputs the employer will need if the connection changes or the provider is replaced. Ask which histories and reports remain available, how they can be exported and who controls that access. A useful purchasing decision includes the ability to explain the posted result after the original operator or vendor is no longer involved.
Start with the exact company file and a realistic pay-run example. Obtain the created transactions, the reports that prove the intended accounting result and one relevant recovery demonstration. Approve only the route and operating responsibilities the evidence supports. That gives the purchase a clear acceptance record and leaves the first live close with something specific to confirm.
Questions to settle before approving the route
Is payroll built into QuickBooks automatically the best choice? It can simplify the connection, but that does not settle pay-calculation fit, needed reports, service responsibilities or exception handling. Evaluate the exact proposed payroll and accounting configuration using the same acceptance requirements as an external service.
Can a file export qualify as compatible? Yes, if its supported destination, account and dimension results, import process and recovery behavior meet the requirement. Record the recurring human work and review controls as part of the accepted route. Do not present that route as a fully automatic connection.
Should employee-level detail appear in every accounting report? Decide what detail the company needs for reconciliation and cost reporting, and what should remain in restricted payroll records. Require a usable reference back to the source without exposing more employee information than the accounting purpose requires.
Explore the Decision Guides library.
Continue with payroll operations guides.

About the author
Ben Scott writes and maintains payroll decision guides for founders and operators. His work focuses on execution realities and how decisions hold up under growth, complexity, and controls and documentation pressure. He works hands-on in HR and leave-management roles that intersect with payroll-adjacent workflows such as benefits coordination, cutovers, and compliance-driven process controls.


