
Payroll Liability Reconciliation Checklist: Prove the Closing Balance

Updated: Oct 25
Carry a payroll liability into close with a specific explanation of who is owed, how the amount arose and what happens next. A completed reconciliation should identify outstanding obligations separately from settled payments awaiting posting and unexplained ledger differences. The reviewer can then decide which accounting exceptions remain and which payment or filing task requires immediate action.
Use this checklist to reconcile the movement in each liability category, then explain its closing balance item by item. Start with the approved opening position, add the obligations created, account for settlements and authorized adjustments, and compare that expected result with the general ledger. Keep the payment deadline attached to the underlying obligation throughout the review.
The workflow is for U.S. employers and their payroll, accounting and payment owners. It supports monthly and quarterly close without substituting for payroll calculation, tax preparation or a plan administrator's legal decisions. A balance can legitimately remain payable at close. An unexplained difference, a missed deadline and a payment waiting for accounting are different situations and need different actions.

Reconciliation access and payment evidence matter when evaluating a payroll service. Discuss your evidence requirements in a free advisor conversation with SelectSoftware Reviews. Ask each candidate which liability reports, agency confirmations and historical exports it supplies; verify the answer for your own service arrangement.
Define the obligation before grouping the account
Begin with the employer and the recipient, not a single total labelled payroll liabilities. Federal income tax withheld, employer payroll taxes, employee benefit deductions, employer contributions and amounts withheld under orders can share a funding process while representing different obligations. A useful category identifies who is owed, which employing entity incurred it, how it arose and where the supporting detail lives.
Separate the employee and employer portions where the source reports distinguish them. Keep the liability's calculation support even if the general ledger combines both portions in one account. Conversely, several accounts may support one remittance. Create a crosswalk between the payroll categories, ledger accounts and payment recipients so the reconciliation can work in either direction.
Choose enough detail to expose an unpaid or misapplied item. For a benefit payment, the invoice period and participant-level deduction support may matter. For a garnishment, the employee and order reference may be essential. For taxes, the agency, employer identification and tax period matter. Do not store unnecessary full identifiers in a shared worksheet; use controlled references to the underlying records.
Keep wage expense accruals and cash clearing accounts identifiable alongside this review. An accrual for work performed but not yet paid can use a different accounting basis from a tax liability reported by wage-payment date. A clearing account may track movement between systems rather than the amount ultimately owed to an agency. Combining them without a bridge can produce a matching total with the wrong meaning.
Keep the accounting cutoff and payment deadline separate
Write down the close date, report extraction time and comparison basis before collecting totals. The payroll register may use check date, the ledger posting date, the bank settlement date and the recipient's application date. These dates describe different events. Preserve each date and explain the relationship rather than forcing every report into an undocumented common month.
Start from the last approved reconciliation, including its outstanding items. Tie that opening balance to the ledger's opening balance for the same accounts and entity. If a prior period has been reopened, identify the entries posted after the earlier sign-off and rebuild the opening bridge. A new spreadsheet should not silently accept a different opening number.
Then identify payments and journals posted around the cutoff. A payment settled on the last business day may reach the ledger through a later feed. A future-dated payment instruction may appear in a provider report before funds move. Save the actual status at the extraction time and mark subsequent evidence separately, so later settlement does not rewrite what was known at close.
The close schedule is an accounting timetable, not permission to delay a remittance. Record the applicable due date from the responsible tax, benefits or order reviewer. A liability may need daily attention between closes when a payment is approaching its deadline or its status is uncertain. Escalate the obligation on that timetable even while finance finishes the month-end explanation.
Rebuild the balance from movements with a consistent sign
Use one sign convention in the working paper. For the examples here, a positive amount means a credit liability, or an amount owed. Start with opening liability, add new obligations and approved increases, then subtract settlements and approved decreases. The result is the expected closing liability. Compare that expected amount with the closing ledger balance before deciding whether either record needs correction.
Keep new obligations separate from adjustments. Current payroll deductions and employer contributions belong in creation activity. An approved reversal of an earlier posting, a reclassification or a corrected amount needs its own reference and explanation. Combining both categories into a single net payroll entry can hide an old item being removed while a new one is added.
Use settlement amounts consistently. A payment file can include service fees, several employers, multiple periods or more than one deduction category. Match the portion that reduces this particular obligation. Record the rest elsewhere in the crosswalk. Do not subtract a provider's total bank withdrawal from each liability account simply because all the accounts were funded together.
Calculate a residual: closing ledger balance minus expected closing liability. A zero residual means the movements agree under the chosen basis. It does not prove that every liability was paid on time or that the original payroll calculations were correct. A nonzero residual identifies an accounting or source-data difference that needs an explanation before anyone treats the balance as supported.
Investigate debit balances separately. A debit might represent a genuine recoverable amount, an advance, a duplicated payment or an erroneous posting. It is not automatically a negative obligation that can be netted against another recipient's credit. Have the accounting owner decide its classification and supporting treatment, keeping any recovery or refund action visible.

Rebuild the expected balance, then compare it with the ledger. A matching rollforward does not establish that each payment met its deadline.
Read settlement evidence from the destination backward
For each amount described as paid, trace the recipient or agency evidence back to the payment instruction and then to the ledger relief. Retain the employer reference, destination, period, amount, payment status and confirmation reference. This gives the reviewer a chain to examine rather than a folder containing unrelated reports that happen to total the same amount.
A bank debit shows money left an account. Depending on the arrangement, it may show funding to a provider rather than delivery to the eventual tax agency, plan or other recipient. Ask the payment owner what the debit represents. A scheduled, submitted, accepted or completed label should be supported by the provider's definition and the relevant downstream confirmation.
IRS guidance on outsourced payroll explains that employers generally retain employment-tax responsibilities when using a payroll service provider, with different rules for some arrangements such as certain CPEO relationships. Establish which arrangement applies before assigning responsibility. Keep access to employer-specific filing and payment evidence rather than assuming the service contract transfers every obligation.
Match payment reversals, rejected instructions and refunds to the original item. If a deposit was sent to the wrong period or recipient reference, a successful transfer alone does not answer where it was applied. Assign the person who can obtain the correction evidence. Avoid an unverified repeat payment while the original transaction is still being located.
Where the recipient has received the right amount but the ledger has not cleared it, retain that settlement proof and identify the exact missing posting. The remaining task is an accounting entry with an owner and expected posting date. Paying again would create a new problem; posting an unexplained offset would leave the original reconciliation incomplete.
A $3,400 balance with only $3,000 explained
The fictional employer in this case reviews an ordinary benefit-premium liability at month-end. Its approved opening liability is $2,400. Payroll creates $9,600 of new supported obligations during the month. Payments of $9,000 are applied to that same employer, benefit and coverage population. There are no approved increases or decreases. The expected closing liability is therefore $3,000: $2,400 plus $9,600 less $9,000.
The ledger instead closes at a $3,400 credit. The $400 residual is not evidence that another $400 must be paid. It means the ledger contains $400 more liability than the rollforward currently supports. Finance retrieves the complete journal activity and finds a separate $400 credit posted by a manual close journal. The journal's amount must be investigated on its own evidence.
Meanwhile, the benefit administrator supports the $3,000 remaining obligation with coverage-period detail and the agreed payment calendar. Assume, only for this fictional example, that it is not yet due under the applicable arrangement. That evidence supports carrying $3,000 as unpaid. It does not support the extra $400 or establish the deadline for a retirement-plan contribution or another benefit.
If review establishes that the $400 journal duplicated an obligation already included in payroll, the authorized accounting correction can remove that duplicate. Reference both entries and record who approved the conclusion. After the correction, the ledger and expected balance agree at $3,000. The case still has an unpaid obligation to monitor, even though its accounting residual is zero.
If the evidence instead shows that a valid $400 employer charge was omitted from the source schedule, update the supported creation or adjustment record and its payment instruction. The expected balance would then change. The useful control is the documented explanation of what the amount represents, not a preference for the lower number or an automatic reversal whenever reports differ.
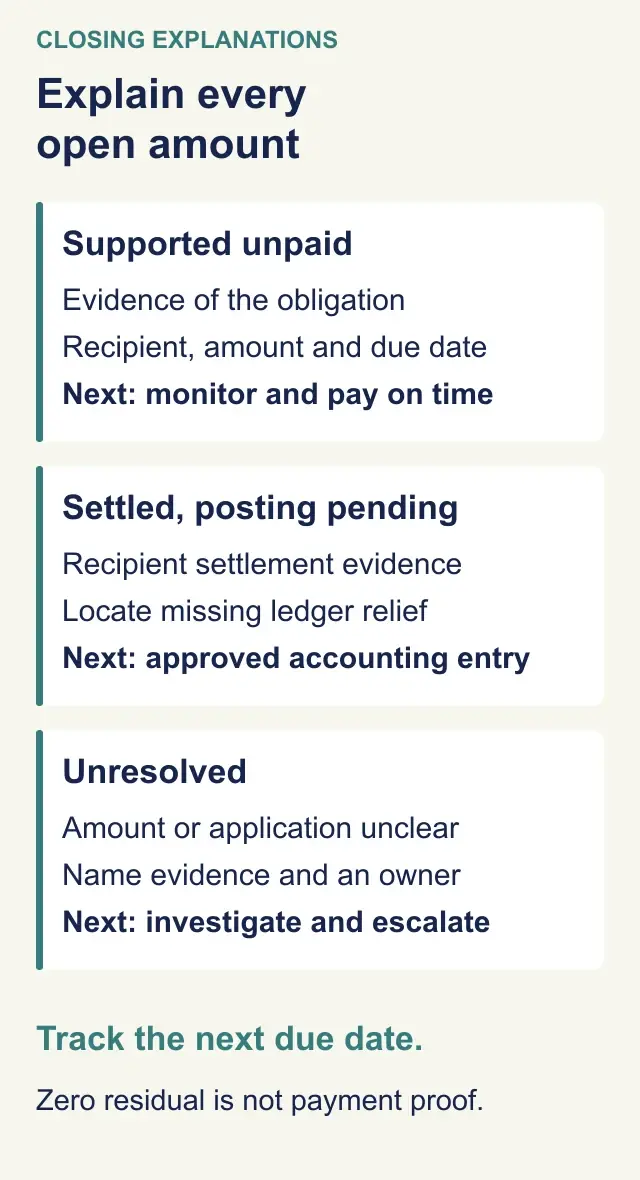
Give supported unpaid obligations, settled items awaiting posting and unresolved amounts different next actions. Keep each deadline visible.
Complete a Liability Balance Review Sheet
Use one review sheet per employer, liability category and reconciliation period. Keep a separate settlement crosswalk when several payments or recipients support the balance. Copy the six fields below into a controlled worksheet or case record. Preserve links to evidence instead of putting full bank accounts, employee tax identifiers or sensitive order details in the shared summary.
Scope and opening position.
Employer: ____;
liability category and recipient: ____;
ledger accounts: ____;
period and extraction time: ____;
reporting basis: ____;
approved opening balance: ____;
prior reconciliation reference: ____.
List any change to the opening position since the previous approval.
Movement calculation.
Opening liability: ____;
new obligations: ____;
approved increases: ____;
settlements applied: ____;
approved decreases: ____.
Expected closing equals opening plus new obligations plus increases less settlements less decreases: ____.
Actual closing ledger balance: ____;
residual, ledger less expected: ____.
Settlement crosswalk.
For each payment, enter instruction reference: ____;
employer and destination: ____;
obligation period: ____;
amount applied to this category: ____;
actual settlement or recipient-application evidence: ____;
ledger relief reference and posting date: ____.
Identify reversals, returns and unapplied amounts separately.
Closing-balance explanation.
Supported unpaid items: ____;
settled items awaiting ledger posting: ____;
unresolved amounts: ____.
For every item, include its amount, origin, evidence reference and owner. Show how the supported items and identified differences relate to the closing balance without counting the same payment twice.
Deadline and next action.
For each open obligation, record the reviewer responsible for the applicable rule: ____;
confirmed due date or decision needed: ____;
payment or correction owner: ____;
next action and checkpoint: ____;
escalation if the date or evidence is missing: ____.
Flag any suspected late remittance independently of the accounting residual.
Close review and later clearance.
Preparer and date: ____;
independent reviewer and date: ____;
entries approved or rejected: ____;
exceptions accepted for accounting close under company policy: ____;
remaining payment or filing tasks: ____.
On follow-up, add actual clearance evidence and date: ____.
Retain the originally signed version and the later resolution.
The sheet is complete when another reviewer can reproduce the arithmetic, identify the remaining obligation and follow each exception to its next decision. A blank deadline is an unresolved decision, not a statement that nothing is due. Where one account contains several categories, complete the supporting detail first and then reconcile its combined total to the account.
A provider report should let your team trace an obligation to its settlement evidence. Use a free advisor conversation with SelectSoftware Reviews to discuss services against the questions on your review sheet. Ask the provider to demonstrate the report and destination evidence you need.
Match tax reporting without replacing liabilities with deposits
For the Form 941 component, distinguish the liability generated during the quarter from deposits, credits and the amount remaining unpaid. The current IRS Form 941 instructions say line 16 summarizes tax liability rather than deposits. Monthly schedule reporting uses the month wages were paid, not the month the expense was accrued or the deposit was made. Semiweekly depositors use the required Schedule B reporting.
Build a specific bridge from the payroll tax reports to the applicable return fields and liability schedule. Keep accounting accruals, posting-date differences and other liability categories outside that tax total unless the reviewer establishes the correct connection. A general ledger account containing benefits and taxes cannot be compared directly with one federal return line.
Separately reconcile the deposits and other amounts applied to the return. Retain the employer, form, period, amount and confirmation for each item. Check whether an amount treated as a payment belongs to another quarter, was reversed or represents a credit handled separately on the return. Ask the tax preparer to resolve the filing treatment; do not use a ledger journal as a substitute for that decision.
If the reconciliation reveals an error on an already filed Form 941, route it through the appropriate correction review. The IRS identifies Form 941-X as the correction form. Record which filing, accounting and payment records actually require change, since a correct payment with a wrong posting is different from an incorrect filed tax amount.
Use the quarter-end tie-out to connect the monthly work rather than starting a new unexplained total. Carry forward each month's open-item references and later resolutions. The filing reviewer should be able to distinguish a still-open obligation from a settled item awaiting posting, and both from a genuine tax-reporting error.
Give plan contributions and order deductions their own timing review
A shared deduction account does not create a shared legal payment calendar. Payroll withholding, employer contributions, insurance premiums and amounts withheld under orders need their own responsible reviewer and destination evidence. Use the plan, contract, order and applicable law to establish what must be sent, when and with which identifying details.
Current Department of Labor guidance for retirement-plan employers says payroll-withheld employee contributions must be forwarded to the plan as soon as possible. Employer matching and discretionary contributions follow the plan documents. A month-end review therefore cannot serve as permission to hold all plan money until the next close. Have the plan administrator determine the applicable requirements and any late-contribution response.
For insurance premiums, reconcile the participant and coverage-period support with the carrier or administrator's billing and receipt evidence. A payroll deduction and a carrier charge can differ because of enrollment timing, arrears, employer contributions or another documented item. Investigate that difference before treating a vendor invoice as authority for an additional employee deduction.
For amounts withheld under an order, preserve the employee and order reference in restricted support and keep its remittance instructions visible to the responsible operator. A combined payment may need allocation among several orders. The liability review should expose missing or rejected allocations; it should not invent an order priority, a universal remittance interval or an employee charge.
If money has already left the employer but the participant or order-level application is unresolved, retain both facts. The accounting reviewer needs the payment trail, while the benefits or order owner needs to locate the application and decide the required response. A zero ledger balance does not resolve an employee-facing remittance problem.
Approve the close with an explicit exception list
Prepare a short conclusion for each category: the supported closing liability, amounts settled but not posted, unresolved residuals and any payment or filing action still open. Attach the rollforward and exception references. Avoid a single status reading reconciled when it means only that two totals agree.
The controller or authorized accounting reviewer decides whether the available evidence and exceptions support close under the company's accounting framework and policies. Record that decision and any limitation. Acceptance for financial close does not authorize a late payment, cancel a statutory obligation or make an unsupported deduction permissible. Escalate those matters through their own responsible reviewer.
Review every manual journal affecting the liability accounts. The evidence should show its purpose, source amount, affected employer and period, approval and expected effect on the next reconciliation. Distinguish a reclassification between accounts from a reduction of the underlying amount owed. If a reclassification crosses categories, carry the obligation's identity into the destination account.
Track subsequent clearance without replacing the signed close record. Add the payment application or posting evidence, completion date and person who checked it. If the expected clearance date passes, reopen the exception or change its next action. Repeatedly copying a timing label into a new month without fresh evidence gives the reviewer no useful explanation.
Keep the evidence usable after staff turnover. IRS employment-tax recordkeeping guidance specifically includes deposit dates, amounts and acknowledgment references, along with filed returns and confirmation numbers. Apply the appropriate record-type retention rules and legal holds to the full evidence pack. An account reaching zero is not a document-destruction trigger.
Preserve open obligations through a mapping or provider change
Before a mapping change, retain the last approved liability rollforward, account crosswalk, unsettled payment list and open exceptions. Identify the effective date and which payroll runs use the old and new mapping. The opening position in the new structure needs a documented bridge back to the previously approved obligations.
Test one representative creation, settlement and adjustment through the proposed route using an authorized demonstration or controlled example. Confirm which account each event changes and where the recipient evidence can be retrieved. This is acceptance evidence to obtain from the provider or system owner, not a claim that a particular product has been tested for this guide.
During a provider departure, assign the owner of payments, refunds and corrections that remain with the previous service. Keep access or exports sufficient to identify the employer, period and actual application of each outstanding item. Funding a new provider should not erase the old provider's unresolved balances or cause the same obligation to be paid twice.
After the change, compare the first completed movement with the approved baseline and inspect the exceptions directly. A correctly mapped new run can coexist with an incorrectly carried opening balance. Resolve those problems separately, and retain the reason for any corrected opening amount rather than describing every difference as migration timing.
Use three review cadences, each with a different purpose
Reconcile payroll liabilities at three cadences: validate each payroll event as it posts, monitor open obligations against their deadlines between runs, and complete the full rollforward at every accounting close. After each payroll event, validate the liabilities created and their ledger posting. Include off-cycle runs, voids and approved corrections that affect the category. This makes source and posting errors visible while the operators still have the transaction context. The check can be proportionate to the event; it does not require rebuilding the entire quarter every payday.
Between payroll runs, monitor obligations against their actual payment and filing deadlines. The payment owner should know what is scheduled, what was accepted, what settled and what still lacks evidence. Increase attention when a deadline is close, a return occurs or a provider's confirmation is missing. The appropriate interval follows the obligation's risk and requirements.
At each accounting close, prepare the full rollforward and review its closing explanations. At quarter-end, connect those records to the relevant filings and recipient reconciliations.
Start the next review with the prior signed sheet and its unresolved items. Confirm the opening position, check the next approaching obligation deadline and obtain the evidence needed for the largest unexplained movement. That produces a specific worklist for the next operator rather than another request to investigate payroll generally.
Assign payment, filing and accounting responsibilities before changing a service. For help comparing services before a switch, request a free SelectSoftware Reviews advisor consultation. Confirm reporting access, outstanding-item ownership and any separate fees directly with each provider.
Explore the Decision Guides library.
See the Payroll Operations & Controls hub.

About the author
Ben Scott writes and maintains payroll decision guides for founders and operators. His work focuses on execution realities and how decisions hold up under growth, complexity, and controls and documentation pressure. He works hands-on in HR and leave-management roles that intersect with payroll-adjacent workflows such as benefits coordination, cutovers, and compliance-driven process controls.


