
Payroll Close Handoff SOP: Deliver the Right Run to Finance

Updated: 6 hours ago

A register in the close folder shows $101,200 of gross pay. The journal was built from a $100,000 preview. Both files look final, and the journal balances. In this fictional case, finance has received reports but cannot yet identify the payroll result it should use.
A payroll close handoff SOP defines the package payroll delivers, the checks finance performs on receipt, and the response when the package is incomplete or replaced. Its output is an accepted version of a specific run, with enough support to start the agreed accounting work and an explicit record of anything still pending.
The package does not have to prove that every payment has settled before finance can receive it. It does have to distinguish an approved calculation, an accepted package, a posted journal and a settled cash movement. Treating all four as “payroll complete” hides the work that remains.
Use the Run Package Receipt below to record that distinction. The procedure suits a small payroll team handing work to an external accountant as well as separate payroll and finance departments. Adapt the acceptance authority, accounting treatment and payment deadlines to your organization.
Contents
Define the work finance can accept
Finance accepts a package for a stated purpose. Receipt may allow the accountant to prepare a journal, review a proposed posting or begin reconciling liabilities. It does not automatically authorize all three, and it does not replace the employer's approval to pay employees.
Write the handoff objective as a sentence with a run, a version and an allowed action: “Finance accepts package R-24 version 2 for journal preparation for Entity A.” Add the limitations that matter, such as a pending debit confirmation. A reviewer should be able to read that sentence without searching an email thread for what “done” meant.
Separate the receiving check from the accounting review. On receipt, finance checks that the expected entities and runs are present, that the reports describe the approved version, and that the index leads to usable support. Finance then performs the journal, balance-sheet or cash review assigned by its close procedure. A receipt showing all files arrived does not establish that those later checks passed.
This distinction also prevents payroll from being asked to certify accounting decisions outside its authority. Payroll can identify the approved earning result and explain a correction. Finance decides the posting period, account treatment and any approved estimate under the organization's accounting policy. Payroll documents the wage result; finance documents the accounting treatment it authorizes.
For a one-person business office, the same employee may prepare much of the package. Still identify the person authorized to accept the work, such as the controller or external accountant, and preserve what they reviewed. If staffing prevents a separate review, have management approve a practical alternative rather than recording a review that nobody performed.
Give every package a run identity and a version
Create an index that identifies the employer, payroll system, run reference, pay group, pay period, pay date and package version. Include off-cycle or supplemental runs separately. A filename saying “October payroll final” is inadequate when two entities have different pay dates or a correction creates a second result in the same month.
Record the report generation time and the payroll status when the report was produced. A report downloaded after approval can still use a filter that excludes a location. An export created before a final correction can still sit in a folder named for the completed run. The index should state the scope and connect each output to the accepted calculation.
List the actual files or controlled links, their purpose and their owners. The useful unit is a specific retained version, not a link to a dashboard whose contents change whenever someone reruns a report. If the system cannot preserve an immutable export, agree how to retain a dated copy and identify later replacements without implying that the software has a feature it lacks.
Show the population and control totals the receiver should expect. Employee or payment counts, gross pay, net pay and relevant liability totals help detect an omitted run or an incorrect filter. Define each count: one person can have two payments, and a void can affect payment counts differently from the active employee count.
Do not combine currencies into a meaningless grand total. For multiple employers, retain entity-level evidence even if a summary presents a group view. Identify which accounting organization receives each run and who confirms the complete entity list. A package that reconciles overall can still put one employer's liability in another employer's accounts.
Make access part of the delivery check. Ask the actual receiver to open the controlled links using their ordinary permissions. A sender's screenshot of an accessible folder does not prove that finance can retrieve the journal or supporting register when the preparer is absent.
Organize the evidence around four finance uses
The package should let finance understand the result, post it, track money and investigate exceptions. It need not attach every report the payroll system can produce. Use a short index with the evidence required for these four uses, and link detailed employee support only where the recipient needs it.
Explain the approved payroll result
Include the approved register or equivalent retained result and the approval reference. State the included entities, groups and payments, the comparison basis, and the significant movements that the preparer investigated. Explain whether an increase comes from a bonus run, a different payroll population or a correction, rather than labelling every movement “timing.”
Retain approval evidence for manual adjustments and identify any unresolved result. An email saying “approved payroll” should be connected to the version the approver saw. If a changed deduction or earning remains under investigation, describe its affected population and the action taken to meet payment obligations. The handoff does not make an unresolved wage question disappear.
The receiving accountant may need aggregate totals and a reference to restricted employee detail. That is different from needing a broad email attachment containing every employee's bank account or tax identifier. Design the package around the recipient's work and the access controls discussed below.
Support the intended posting
Provide the journal or export, its source run and the mapping version used to create it. State whether the file is a proposed posting, an already imported batch or a report of a posted journal. Include the accounting reference when one exists, so the next person does not import the same file again.
Give finance a way to bridge the register to the journal. The bridge should explain included employer costs, deduction liabilities, cash or clearing accounts, and any excluded items relevant to the organization's configuration. A balanced journal establishes equal debits and credits; it does not establish that the amounts, entity or period are right.
If a new earning code appeared, identify the reviewed mapping rather than asking finance to infer its intended account from the label. If the journal was changed after export, preserve the original, the authorized adjustment and the resulting accounting record. Avoid a handoff in which the payroll report and finance spreadsheet both claim to be the original result.
Identify cash and liability follow-through
Provide the payment or funding schedule with dates, amounts, responsible parties and current statuses. Distinguish employee net pay, tax movements, benefit or retirement remittances, and provider fees when those use different routes. If the provider bundles several amounts into one debit, retain the detail needed to explain it.
A payroll debit confirmation is different from evidence of each downstream remittance. A released payment instruction is not yet a settled movement. Similarly, a calculated liability is different from a completed deposit. Mark future or unconfirmed movements as pending with an owner and a due date. Do not attach a successful payroll submission message as if it proved that a tax agency received money.
The IRS employment-tax record list includes deposit dates and amounts, EFTPS acknowledgment numbers, filed returns and confirmation numbers. Use that distinction when choosing support: the register, deposit evidence and filing acknowledgment serve different purposes and may become available at different times.
An outsourced payroll arrangement also needs an identified monitoring owner. The IRS describes different third-party payer responsibilities, including situations in which employer liability remains and certain CPEO exceptions. Confirm the actual arrangement rather than assuming a provider contract transfers every filing or payment responsibility.
Carry the unresolved work
Include an exception list that states the issue, affected run or amount, current evidence, owner, next action and decision deadline. Distinguish an accounting classification question from a potentially incorrect employee payment or missing remittance. They can require different reviewers and different urgency.
Explain the accounting consequence of an open item without inventing a final answer. For example, finance may receive a supported total while a cost-center allocation is still being resolved. The package can identify what remains usable and what must not be posted yet. An unexplained difference should not acquire a harmless “timing” label merely because close is approaching.
When the same issue appears in several runs, use one durable issue reference with links to each affected package. That makes the continuing work visible without implying that it was fixed simply because the next run completed.
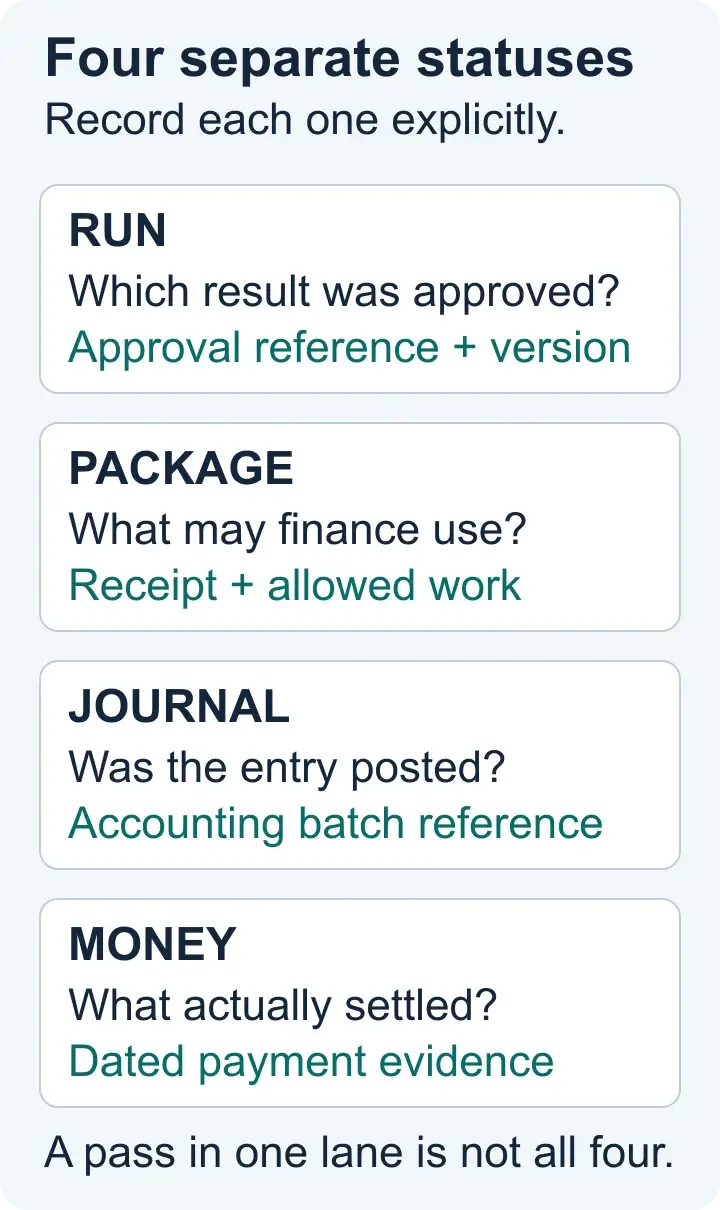
Record each status separately. One completed action does not certify the others.
Choose an acceptance decision with a clear boundary
Use three receipt outcomes: accepted for the stated work, accepted for a defined portion, or returned for correction. These are operating decisions about finance's use of the package. They are not permission to ignore a payment deadline, postpone earned wages or certify a tax deposit without evidence.
Accept the full package when the identity, scope, required evidence and usable access support the intended work. Record the receiver and acceptance time. If payment settlement will occur later, leave that status pending and assign its follow-through. A correctly disclosed pending event is different from a missing required record.
Accept a portion only when the boundary is genuine. Suppose Entity A's package is complete but Entity B's journal uses an unconfirmed mapping. Finance may accept the independently supported Entity A work while returning B's affected posting package. The receipt should name both populations and prevent a group-level status from making B look accepted.
Return the affected work when the version is unclear, required support is absent, totals conflict without an explanation, or the receiver cannot access the evidence. Name the failed condition and what will satisfy it. “Finance rejected payroll” is too broad to tell the preparer whether to replace a register, repair a journal reference or obtain access.
An unresolved issue does not always block every accounting task. Finance's authorized decision-maker should specify whether an approved estimate, restricted posting or other treatment is appropriate under policy. Record that decision and the later reconciliation it requires. Do not let a preparer solve an accounting uncertainty by silently changing the payroll output.
Urgent employee-pay or tax problems need their own timely response while the package is being repaired. The close calendar is an internal deadline; it does not settle external payment obligations. Escalate to the responsible payroll, treasury, tax or legal reviewer with the actual affected amount and date.
Trace a replacement through the receipt
Return to the fictional $100,000 preview and $101,200 approved register. Assume the $1,200 increase is an approved earning correction and the earlier journal has not been posted. This is an illustration of version control, not a wage calculation or a tax-rate example.
The first package, version 1, points to the preview. Payroll then approves version 2 with $101,200 gross but replaces only the register in the shared folder. The journal remains based on $100,000. Finance's first useful check is whether both outputs come from the same accepted result. The fact that the old journal balances cannot cure their $1,200 gross mismatch.
Payroll should mark package version 1 as superseded, identify the approved correction and issue a new index. Finance returns the mismatched posting component. The journal preparer generates or repairs the journal under the approved process and retains its connection to version 2. The receiver then checks the replacement evidence and records a new acceptance decision.
Do not erase the first receipt or overwrite its acceptance time. The history should show what finance had accepted, what changed afterward and which work must be reopened. If an accepted file has already been imported, the posting reference matters: the responsible accountant must determine the authorized correction or reversal route rather than importing a second full payroll as an extra expense.
Extend the correction notice to every affected use. A changed earning may affect net pay, employer costs, liabilities or funding; a changed cost center may affect allocation without changing wages. Identify the actual consequences from the corrected outputs instead of assuming that every correction requires the same downstream action.
A replacement notice can be brief: “R-24 package v2 replaces v1; approved earning correction changes gross by $1,200; journal regenerated; funding effect awaiting treasury confirmation; finance must reaccept the posting component.” The notice is useful because it names the changed evidence and pending action, not because it claims everything is final.
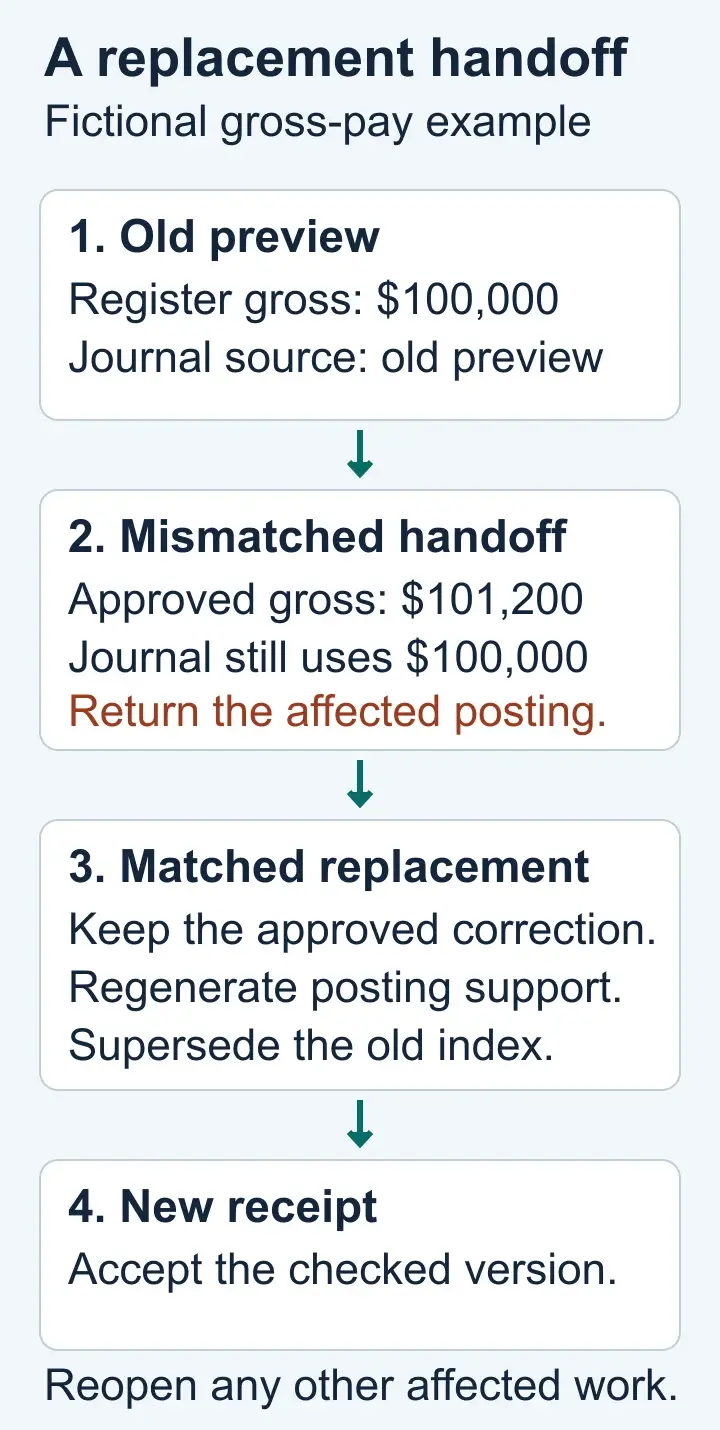
In this fictional case, replacing the register alone leaves the old journal unusable. Reaccept the matched replacement.
If recurring report replacements or missing exports are driving a provider review, bring a representative run package to the discussion. Ask which outputs the proposed service supplies and which review tasks remain with your team.
Handle period ends and unusual runs explicitly
Keep the pay period, pay date and accounting period as separate fields. A run paid after month-end can relate partly to work performed before month-end. Finance must determine the appropriate accounting treatment under its policy; the handoff should supply the dates, population and support needed for that decision.
If finance records a separate payroll accrual, identify its basis, owner and relationship to the later actual run. An accrual estimate is not an additional payment instruction. Retain the reference used to reverse or reconcile it so a person seeing both records does not treat them as two unrelated payroll expenses.
For off-cycle payments, manual checks, voids and reissues, explain how the item relates to the regular run. Include the original reference and whether the action replaces an earlier payment, adds a new obligation or records money already paid outside the normal payroll route. Avoid merging a reissue into a total without showing the canceled or returned original.
A zero-pay run may still require evidence of its scope, status and any affected liabilities. Conversely, no employee payment in a selected report does not establish that no payroll event occurred. The package index should distinguish a genuinely empty run from a filter that omitted the population finance expected.
Multi-entity organizations need a receiving owner for each employer and a clear route for shared-cost questions. Payroll should identify the originating employment and payment records. Finance owns the approved intercompany or cost-allocation treatment. A consolidated summary should not remove the underlying entity evidence.
At quarter-end or year-end, connect the run packages to the separate tax and annual reporting reviews. Preserve corrections made after the ordinary close deadline and identify the reviewer responsible for any reporting consequence. This SOP supplies the run history; it does not replace the tax return review or annual readiness procedure.
Assign the sender, receiver and unresolved work
Name a payroll package owner and a finance receiver, with authorized backups. Put delivery and response points into the payroll and close calendars relative to approval, report availability and the work finance needs to perform. There is no single handoff hour that works for every provider, pay frequency and accounting timetable.
The sender assembles the index, verifies its scope and reports the actual statuses. The receiver acknowledges access and completeness, identifies the permitted next work and returns specific defects. The person who owns an exception remains accountable until the agreed evidence resolves it, even if the package has been accepted for other work.
Keep acceptance authority separate from system access. A user able to upload a journal may not have authority to approve it. A payroll administrator able to regenerate a report may not have authority to change its source calculation. Record the decision-maker and the operator when those are different people.
Agree how the team responds when the usual receiver is absent or a deadline is at risk. A backup needs the retained evidence and the authority to make the defined decision, not a colleague's shared login. Escalation should identify the unperformed check and the next authorized reviewer rather than converting silence into approval.
Where a provider supplies part of the package, put report availability, version identification, correction notifications and access after termination into the service discussion. A promised “GL integration” does not itself describe these operating details. Ask for a representative output and a clear responsibility statement before relying on it.
Run Package Receipt
Copy this receipt into a controlled document or work item for each run package. The fields describe the evidence to record; they are not a score. Keep the receipt connected to the index and use a new version or linked acceptance record when the package changes.
Package identity
Employer and population: Identify the employing entity, pay group, currency and included regular or additional runs.
Run and dates: Record the system run reference, pay period, pay date and intended accounting-period review.
Package version: Name the retained index version, generation time and approved register or result it represents.
Sender and access: Record the package owner, controlled location and confirmation that the named receiver can open the required evidence.
An entity, run or access mismatch returns the affected work for correction.
Evidence and pending work
Result and approval: Link the approved result, approval record, expected counts and control totals used on receipt.
Posting support: Identify the journal or export, source-run match, mapping version and proposed, imported or posted status.
Money and obligations: Link the dated funding or remittance schedule, current evidence and owner of each pending movement.
Exceptions and replacements: Record open issue references, affected work, amounts or populations, replacement notices and response deadlines.
Do not describe a pending settlement or unresolved difference as complete merely because the reports arrived.
Acceptance and continuation
Receiving decision: Record accepted, accepted portion or returned; name the precise work allowed or held.
Reviewer and time: Identify the authorized receiver, acceptance or return time and checks actually performed.
Next action: Name each unresolved task, accountable owner, deadline and evidence needed to finish it.
Posting and closure references: Add the accounting batch, later settlement or reconciliation evidence, and any replacement receipt that supersedes this one.
The receipt records the handoff decision. Later posting and settlement results remain separately identifiable.
Retain the proof without distributing every payroll detail
Retain the index, the accepted source versions, the receipt, correction notices and the later evidence required by the organization's record schedule. An index is not sufficient if its links disappear when the provider changes, the preparer's account closes or a shared-drive cleanup removes the reports.
U.S. federal record requirements differ by record type. DOL Fact Sheet 21 describes at least three years for payroll records and two years for records underlying wage computations under the applicable FLSA rules. The finance handoff is one route to usable support; it is not a substitute for maintaining the employee and wage information the rule requires.
The recordkeeping section of IRS Publication 15 generally calls for keeping employment-tax records for at least four years and identifies longer periods for certain credit-related records. Have the responsible adviser establish the applicable start dates, longer requirements and any legal hold. Do not turn one general period into an automatic deletion date for every item in the package.
Give each recipient the information needed for their task. Aggregate posting support may be sufficient for one reviewer while a restricted wage investigation requires employee-level evidence. Use an internal identifier where appropriate; do not copy Social Security numbers or bank details into a broad close tracker merely because they exist in the payroll system.
The FTC's business guidance on protecting personal information recommends keeping needed information, limiting access by job need and maintaining a written retention policy. Apply those principles to the retained detail as well as the index. A safe link with unusable permissions and an unrestricted email attachment are both poor delivery designs for different reasons.
Check export and retrieval arrangements before a provider transition. Retain usable approved versions, the relationships between runs and journals, and the people responsible for pending items. Test retrieval with an authorized receiver. The purpose is continued access to required evidence, not retaining unnecessary copies of every sensitive field.
Use the receipt in the first month-end close
At the first month-end using this SOP, have finance trace one accepted run from its receipt to the posted accounting batch. Include any related accrual and reversal references. Check that the entity, accounting period and retained source version agree across those records. A receiving check may have passed even though the later accounting treatment still needs correction.
Next inspect a package replaced after acceptance. Confirm that the replacement notice identifies which posting or estimate must be reopened and who authorizes the repair. If the original journal was already posted, retain the accountant's correction reference alongside the replacement receipt. The file history should explain why the new package did not become a second expense.
Read the pending-money list against the evidence available at close. An accepted posting package can still have a returned payment or an unconfirmed remittance. Keep the affected balance and follow-through owner visible until the responsible reviewer obtains the required evidence. Acceptance of the reports should never become the explanation for leaving that item unattended.
Have the controller or external accountant identify any point where the trace breaks: an inaccessible source, an unexplained bridge, a missing reversal reference or a replacement that never reached the posting owner. Repair that specific connection. Resolve accounting-policy, mapping and payment questions through their assigned review routes instead of treating every close problem as a missing payroll report.
When a change in systems or service could help, use those concrete gaps to define the purchase. Request the particular reports, correction history, access and support ownership finance could not verify. Retain evidence from the proposed arrangement before committing to it.
Browse the Decision Guides library.
Continue with Payroll Operations & Controls.
Explore the Payroll Operations Resource Library for related processes and practical tools.

About the author
Ben Scott writes and maintains payroll decision guides for founders and operators. His work focuses on execution realities and how decisions hold up under growth, complexity, and controls and documentation pressure. He works hands-on in HR and leave-management roles that intersect with payroll-adjacent workflows such as benefits coordination, cutovers, and compliance-driven process controls.


