Payroll Provider Requirements: Build a Rubric You Can Defend

Updated: 16 hours ago

Two payroll providers can earn the same score for very different reasons. One may demonstrate a reliable approval process and usable exports. The other may collect points for convenient features while leaving a required control unanswered. An average hides that difference unless the rubric separates eligibility from preference.
Build the evaluation in this order: define the work you are buying, identify requirements that every finalist must meet, then score the remaining differences using the same evidence and weights. A high total should never override a failed essential requirement. An unanswered question should remain visible until someone resolves it.
This guide provides a Payroll Requirements Line Sheet, a twelve-area evidence rubric and a worked scoring example for U.S. employers evaluating a payroll provider. Use it to prepare a shortlist, run comparable demonstrations and preserve the reasons behind a selection. It does not name a universal winner or replace advice about your particular employment tax arrangement.

A free SelectSoftware Reviews advisor consultation is an optional way to identify payroll providers to evaluate. Bring your required workflows and service boundaries, then ask each finalist to show how its proposed package meets the rubric below.
Table of contents
Define the purchase before writing the scorecard
Start with a one-page account of the payroll work: legal entities, employee groups, pay frequencies, jurisdictions, earning and deduction types, upstream systems and the people who currently prepare, review and release payroll. Include work that happens less often, such as an employee move, a corrected wage statement or an accounting export repair. These events reveal service boundaries that a routine demonstration may leave untouched.
Separate the product from the service. A provider might supply software, process a submitted payroll, perform particular filing tasks or deliver a broader arrangement. Write who supplies each input, who checks it, who resolves a rejected output and who holds the evidence. Your decision about which payroll tasks to transfer should precede the package comparison.
The IRS distinguishes payroll service providers, reporting agents, section 3504 agents and certified professional employer organizations. Employment tax liability depends on the arrangement and circumstances. With an ordinary payroll service provider, outsourcing does not remove the employer's responsibility for federal employment tax payments and returns. Certain CPEO arrangements have different liability treatment. Use the IRS third-party payer guidance to establish the actual relationship rather than treating every provider as interchangeable.
Assign one internal owner to the evaluation and one approver for the final purchase. Payroll should judge whether the process works, finance should judge the close outputs and costs, and the appropriate security or IT reviewer should assess access and data handling. A small employer can combine roles, but should still identify who will challenge an assumption before it becomes a contract term.
Define the period you are buying for. A planned second state or second entity may be relevant next year; a speculative international expansion may not be. Mark each requirement current, committed future or optional. Require pricing and implementation dependencies for the committed future items. Keep speculative capability out of the essential gates unless there is a real business commitment to use it.
Decide how many finalists you can evaluate properly. Three detailed proposals with comparable evidence can be more useful than ten incomplete feature lists. Send the same requirements packet to each provider and allow the same clarification opportunity. Maintain a version number so a late scope change does not leave one finalist answering a different question.
Set essential gates that a total cannot erase
A gate is a requirement whose absence makes the proposed arrangement unacceptable. It is an employer selection rule, not a claim that every organization must buy the same control. Specify the evidence and acceptance condition before demonstrations, and use three statuses: PASS, HOLD or FAIL.
PASS means the required condition is confirmed for the proposed package. HOLD means a relevant answer or acceptance check is still outstanding. FAIL means the evidence establishes that the condition is not met. Only providers with all essential gates at PASS can enter the final ranking. A HOLD can remain on the shortlist while the named owner obtains evidence; it cannot quietly turn into approval because the sales deadline is approaching.
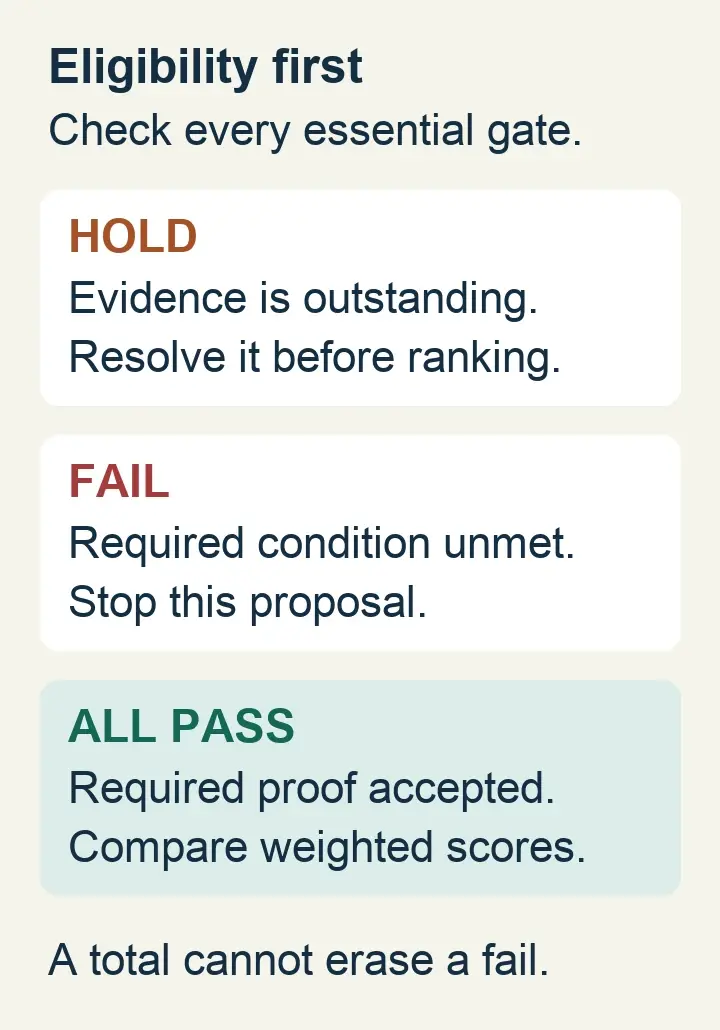
Possible gates include supported entities and jurisdictions, an acceptable release approval process, independently usable tax evidence, required exports, acceptable administrative access and a feasible first-payroll plan. The specifics should match your organization. A five-person employer and a multi-entity finance team may need different approval arrangements, but both need to know what they are accepting.
Write a gate as an observable condition. “Strong controls” is too open to interpretation. “A preparer can create the payroll, a named reviewer can approve it, and the saved record identifies the approval before release” gives the provider a testable request. If separate roles are impractical for your team, define an acceptable compensating review and ask whether the proposal supports it.
For a required integration, list the exact source system, destination, fields, frequency and exception owner. An integration logo is not acceptance evidence. For required states, distinguish calculation support, account registration work, filing scope and who handles an employee location change. Geography belongs in the purchase packet before a provider claims nationwide coverage.
Do not declare an ordinary preference essential merely to make your favored provider win. Gate decisions need a reason: a legal obligation, an internal control requirement, an unavoidable workflow dependency or an implementation constraint. Preserve that reason next to the requirement. If management accepts a different arrangement, revise the requirement openly and reevaluate every affected proposal under the same version.
Turn twelve requirement areas into requests for proof
The following rubric supplies starting questions. Convert the relevant ones into Line Sheets with your actual scenario, acceptance condition and owner. Remove an area from the shared evaluation only when it is genuinely outside the purchase. Add specialized requirements, such as tipped wages or collective bargaining rules, when your workforce needs them.
1. Pay calculation and exception handling
Provide a small fictional pay packet with the earning types, deductions and changes you expect to use. Ask the provider to show the inputs, calculation result, review screen and exception handling. Keep any legal calculation assumptions separately approved; a successful demonstration does not establish that your classification or pay policy is legally correct.
Include one awkward but realistic event, such as a retroactive rate change or a correction after an initial payroll approval. Ask what can be edited, what requires a new run and what evidence remains. Score the actual workflow and remaining employer effort, rather than counting how many earning codes appear in a catalog. Record whether the demonstrated feature is included in the quoted package.
2. Tax activity and employer visibility
Ask what confirms a deposit or filing, which employer account it relates to, how failures are surfaced and who follows up. Distinguish a calculated tax amount, a scheduled payment and evidence that the relevant action occurred. Include responsibility for notices and for periods handled by the prior provider.
The IRS encourages employers to use EFTPS to monitor payment history for deposits made under their EIN. Ask how independent deposit monitoring fits the proposed arrangement, especially if the payer uses an aggregate filing arrangement. Keep the employer's access and verification tasks in the scope. A contractual promise to handle taxes is not itself confirmation of a particular deposit.
3. Preparation, approval and release
Test who can change inputs, approve a payroll and release funds. Ask whether an edit after approval invalidates that approval or creates a visible review step. Walk through the absence of your usual reviewer and determine what happens when a payroll reaches cutoff without approval.
Describe role separation using the actual staffing plan. A demonstration of separate preparer and approver accounts is useful only if those permissions are available in your package and sustainable with your people. Record any manual review outside the platform, its owner and the evidence it creates. This work belongs in the cost and workload comparison.
4. Administrative access and account recovery
Have the security reviewer inspect administrator privileges, authentication options, account recovery, offboarding and access logs. Ask how a departed administrator's access is removed without locking out the employer. Demonstrate what a support representative can access and how sensitive changes are authorized.
NIST's digital identity guidance defines AAL2 using two distinct authentication factors and requires a phishing-resistant option at that assurance level. That is a useful authentication benchmark to discuss with your reviewer; it is not a universal payroll product certification or legal requirement. Request the supported methods and package conditions instead of accepting “secure” as a scored answer.
5. Change history and reconstructable evidence
Choose a pay-rate or bank-detail change and ask the provider to reconstruct it. The change history should establish what changed, when it changed, who performed it and what approval or verification accompanied it. Check whether this history can be exported in a usable format.
Do not score a screenshot of a current value as proof of its history. Ask what happens to those records after a reversal, account closure or permission change. Your payroll change evidence requirements should determine which fields matter. A generic activity log may be sufficient for one task and inadequate for another.
6. Records, exports and exit access
Request a sample export of the records you need, including historical payroll, employee identifiers, earning and deduction detail and relevant filing evidence. Inspect whether the files preserve relationships and dates. Ask about extraction charges, access after termination and any dependence on the provider to produce an archive.
Federal FLSA recordkeeping rules generally require covered payroll records to be preserved for at least three years. Employers required to keep specified supplementary records, such as basic time and earnings records, must generally preserve those for at least two years. These rules do not supply your complete retention schedule. Confirm applicable tax, state, contract and legal-hold requirements, then test whether the provider supports the resulting retention and export needs.
7. Interfaces and failed transfers
Supply a representative import or export specification. Ask the provider to show accepted records, rejected records, duplicate handling and a correction. Identify who owns a field mapping and who notices a failed transfer before it affects payroll or accounting.
Treat a file download, a supported connector and a custom integration as different arrangements. For each, establish setup work, running work, monitoring and fees. Translate the relevant source fields before accepting a migration or interface estimate. Do not give credit for a future connector until its current availability and your required behavior are demonstrated.
8. Finance outputs and reconciliation
Give the provider the entity, department and account dimensions finance actually uses. Request the proposed journal output, the supporting payroll detail and an example of a correction or reversal. Ask finance to determine whether those outputs can be reconciled without an undocumented spreadsheet repair.
Avoid assigning the same benefit points three times under reporting, integration and accounting. Define the boundary: the interface requirement tests the transfer, while the finance requirement tests whether the resulting entries and supporting records are useful for close. Preserve distinct evidence for each score and identify any remaining manual allocation.
9. Implementation responsibilities and acceptance
Ask for a plan showing data owners, conversion scope, validation work, dependencies, first-payroll acceptance and escalation. Specify prior-period data and filing boundaries. “Implementation included” should resolve into named work and acceptance conditions, with any charge or employer task identified.
Check the calendar against your people's availability. If a proposal depends on clean historical data that you do not have, record the remediation and timing rather than awarding a point for an optimistic date. Carry implementation acceptance checkpoints into the eventual project plan. A provider can satisfy a functional requirement while still presenting an infeasible transition proposal.
10. Support during a payroll problem
Use a specific incident and time: a rejected file shortly before cutoff, for example. Ask which channel is available, which team owns the case, what information you supply and who performs the repair. Separate access to an answer from responsibility for completing a task.
Request written service scope, applicable hours and escalation terms for the quoted tier. Score whether that scope fits your operational needs; do not invent a response guarantee because someone answered the sales call quickly. If the proposal depends on premium support, include its price.
11. Fees and recurring employer workload
Obtain a quote that identifies base charges, employee or entity charges, required add-ons and relevant event fees. Use your expected off-cycle runs, year-end work, corrections, integrations and exit needs to ask what is included. Distinguish a contractual fee from an assumption in your cost estimate.
Estimate employer effort separately: data preparation, approval, exception repair, reconciliations and administration. Name the task, frequency, responsible role and estimated time. Use the same assumptions across proposals and label them estimates. A lower subscription price may remain the right choice when the retained work is manageable; the rubric should make that tradeoff visible.
12. Required growth and service changes
Test one committed change, such as adding an entity or moving into a new state. Ask what must be reconfigured, contracted, registered or implemented and who owns those steps. Avoid giving points merely because a provider sells a larger product elsewhere in its catalog.
Record the trigger for reassessing the arrangement. A changed workforce, required control or service boundary may justify a new requirements version. Ordinary feature announcements do not automatically require a purchase review. Keep the rubric tied to the next decision you actually expect to make.
Your evidence requests may reveal that the shortlist needs a different service model or package. Use a free SelectSoftware Reviews advisor consultation to discuss those boundaries, then verify the revised proposal with the provider before scoring it.
Copy the Payroll Requirements Line Sheet
Copy this block into notes or a spreadsheet and make one record for each requirement and each provider. Keep a shared requirement list so the identifier, weight and acceptance condition mean the same thing across finalists. The provider-specific evidence and result can then differ without changing the question.
Requirement definition
Requirement ID and short name:
Business scenario and population affected:
Current, committed future or optional:
Required outcome and acceptance condition:
Essential gate, weighted criterion or both:
Weight and reason for that weight:
Provider assessment
Provider, package and quote version:
Evidence requested and date requested:
Evidence received, date and retrievable location:
Evidence reviewer and outcome:
Gate result: PASS, HOLD, FAIL or not a gate:
Score: 0, 1, 2, 3, UNKNOWN or not weighted:
Remaining employer task, owner and estimated effort:
Open question, responsible person and due date:
That produces fourteen fields per line. For a gate-only requirement, mark the weight and score not weighted and exclude that line from the weighted denominator. UNKNOWN applies to a weighted requirement whose evidence is missing. Store sensitive demonstrations and exports in an approved location rather than a widely shared scorecard. Use fictional or appropriately protected data for demonstrations. The scorecard can point to evidence without carrying bank details or employee information itself.
Use this score scale for the weighted criteria:
0: Evidence shows the proposed arrangement does not meet the requirement.
1: An acceptable workaround meets the outcome, with identified employer work or limitations.
2: Evidence shows the proposed arrangement meets the defined outcome through the expected workflow.
3: Evidence shows it meets the outcome and supplies an additional benefit your team defined and values.
UNKNOWN: The evidence is insufficient to assign a score. Record the unresolved question and owner.
A three is not a reward for extra features nobody will use. Define the additional benefit before seeing the providers. For example, a finance export that meets the required dimensions earns two; one that also produces a correction trail that removes the accepted manual reconciliation step may earn three if that distinction was part of the agreed scoring rule.
Keep the type of proof separate from the score. A written statement may establish service scope, while a workflow demonstration may be needed to establish behavior. Neither is always superior. Use the evidence appropriate to the requirement, record its limits and require clarification where the documents and demonstration disagree.
For essential gates, the acceptance condition still decides eligibility. A score of one can pass a gate if the specified workaround is acceptable under that gate. If your gate requires a native approval record, an external spreadsheet workaround fails that gate even if another weighted criterion gives it partial credit. Make this relationship explicit so reviewers do not substitute a score for the required condition.
Calculate a comparable score without hiding unknowns
Assign weights before provider results. A simple starting scale is five for a major operational consequence, three for an important workflow and one for a convenience. Those are suggested selection weights, not measured risk probabilities. Use another scale if it is easier for your team, provided the reasons are documented and the same weights apply to every proposal.
For each scored requirement, multiply its weight by its score. Add those products. Divide by three times the sum of the shared weights, then multiply by 100. The result is the percentage of the available weighted points earned under this rubric.
Weighted percentage = 100 × sum of (weight × score) ÷ (3 × sum of weights).
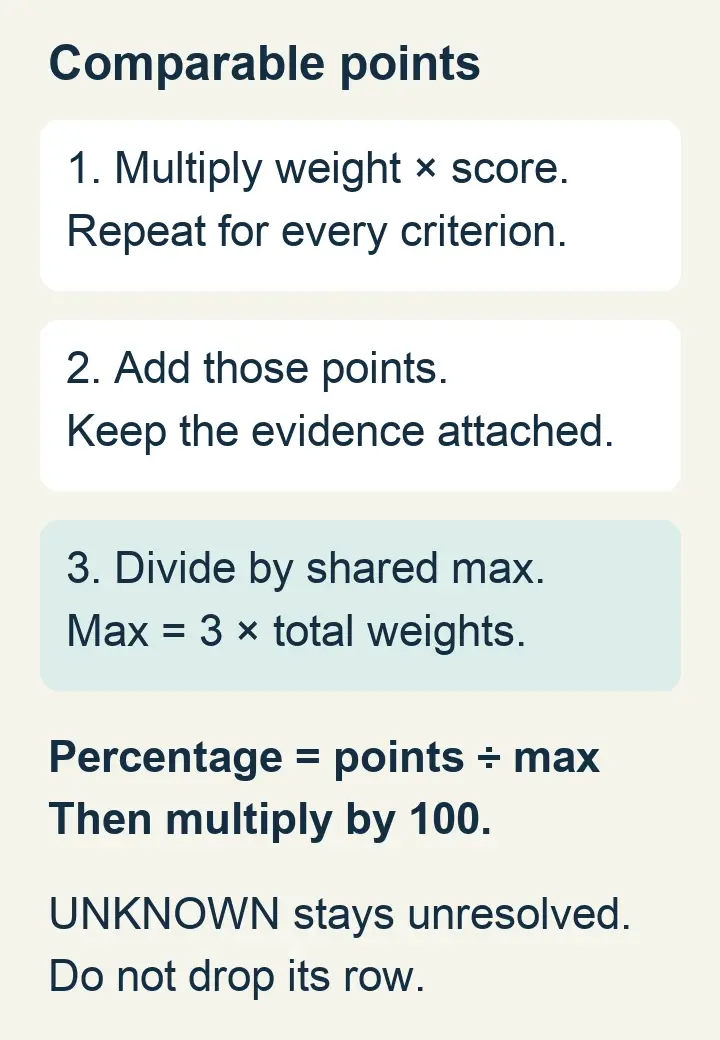
Do not calculate a final ranking while a scored requirement remains UNKNOWN. You can display a provisional point subtotal and list the unresolved rows, but do not present a normalized final percentage as though the evidence were complete. Dropping an unanswered high-weight row from one provider's denominator can make that proposal look artificially stronger.
Set the same clarification deadline for every finalist. If it passes without enough proof to score a line, exclude that proposal from the final ranking and record the unanswered requirement. Document any shared deadline extension for all finalists.
If a requirement becomes genuinely unnecessary, remove it from the shared rubric and recalculate every finalist. If it remains necessary but a provider does not meet it, the result is zero, not “not applicable.” A gate failure stays a gate failure. Treat a material requirements change as a new version, with an explanation and updated provider answers.
Worked example: a higher score with no eligible winner
The following providers and results are fictional. Four criteria illustrate the calculation; they are not a complete selection packet.
Approval workflow has weight 5. Alder scores 2 and Birch scores 3.
Current-run accounting export has weight 3. Both providers score 2.
Incident support has weight 3. Alder scores 3 and Birch scores 2.
Scheduling convenience has weight 1. Alder scores 1 and Birch scores 2.
The shared weight total is 12, so the maximum is 36 points. Alder earns 10 + 6 + 9 + 1 = 26, or 72.2%. Birch earns 15 + 6 + 6 + 2 = 29, or 80.6%. Those percentages describe the four weighted criteria only; they do not describe compliance, overall safety or the probability of a successful implementation.
Now add the gate review. Alder has an essential tax-evidence question at HOLD. Birch has failed the required exit-export condition because the available archive omits records the employer must preserve. That gate concerns the post-termination archive, a different output from the current-run accounting export scored above. Neither proposal is eligible for final selection yet. Birch's higher score cannot erase the failed gate. Alder needs a resolved answer, not an assumed pass.
Suppose Alder later proves the tax-evidence condition and all its gates pass. Its weighted result remains 72.2%. It becomes the eligible proposal in this example, subject to the full evaluation and commercial approval. Birch returns to consideration only if it demonstrates a solution that satisfies the existing export gate, or the employer transparently revises that gate for a defensible reason and reevaluates both proposals.
Resolve close results through tradeoffs and signed conditions
Treat the score as a summary of judgments you can inspect. If two eligible providers finish close together, look at the lines that differ most and ask whether their weights reflect actual consequences. Do not add decimal precision to subjective scores to manufacture a winner. Keep the underlying evidence, retained workload and quoted cost alongside the total.
Run a simple sensitivity check before presenting the recommendation. Change one disputed weight to another plausible value and recalculate all finalists under that same alternative. If the preferred provider changes, the choice depends on that priority judgment. Explain it to the approver and agree the priority instead of concealing it in arithmetic. Keep the original and alternative versions.
Have reviewers score independently before reconciling differences. When one person gives a two and another gives a one, compare the acceptance condition and evidence. One may have overlooked a required employer task; the other may be treating an acceptable workaround as unacceptable. Resolve the reason, rather than averaging the two scores and losing the operational distinction.
Document a short selection recommendation: eligible providers, weighted result, cost assumptions, employer work, important tradeoffs and outstanding purchase conditions. Attach the evidence locations and quote version. A remaining contract condition can be legitimate, but it should not disguise an unresolved essential capability. Require its resolution before the purchase is approved.
Translate the winning claims into written scope. Identify included work, package, implementation responsibilities, required configuration and the acceptance evidence. A favorable demonstration does not amend the contract. Have the appropriate commercial reviewer address any gap between what was shown and what the proposed agreement supplies.
After selection, transfer the relevant Line Sheets into implementation acceptance and the ongoing operating review. Keep the provider's evidence and your final decisions. Check the promised outputs during the agreed validation work, then revisit the rubric when the workforce or operating requirements materially change. This makes the purchase record useful after the sales meeting is over.
Choose the provider whose documented arrangement fits the work you can operate. For a small team, an acceptable manual step may be cheaper and sustainable. For a complex payroll, that same step may consume scarce review time or leave evidence fragmented. The recommendation should name the tradeoff, the person who will own it and the condition that would make you reassess it.
Continue with related resources:
If no finalist passes every essential gate, a free SelectSoftware Reviews advisor consultation is one way to find providers to test against the same Line Sheets. Keep the final choice tied to each provider's evidence, written scope and the workload your team accepts.

About the author
Ben Scott writes and maintains payroll decision guides for founders and operators. His work focuses on execution realities and how decisions hold up under growth, complexity, and controls and documentation pressure. He works hands-on in HR and leave-management roles that intersect with payroll-adjacent workflows such as benefits coordination, cutovers, and compliance-driven process controls.