
Payroll Software for Small Business: Choose for Your Operating Stage

Updated: 22 hours ago

Choose a payroll setup your team can finish, review and support within the time actually available. For a stable payroll run handled by one operator, a focused service with a clear tax arrangement and accessible records may be enough. When managers supply changing hours or finance depends on detailed payroll output, the purchase also needs to reduce and coordinate those handoffs. Headcount alone cannot tell you which setup fits.
Look at the work that remains with your business after the software is installed. Who gathers missing hours? Who approves a change? Who checks the funding instruction, resolves an employee question and produces the bookkeeper's report? A package can contain every advertised feature and still leave too much work with the person who runs payroll.
Use the Small Business Payroll Workload Card below to compare an ordinary run, a busy run and a planned change. The examples are fictional. The card measures your proposed allocation of work and available capacity; it does not assign an independent rating to a vendor. This guide covers U.S. small employers choosing a payroll operating setup, with public product documentation checked on October 12, 2026.
Table of contents
Describe the stage by the people and work involved
An owner-led stage has one person preparing most payroll information, authorizing the run and dealing with problems. The inputs may be predictable, but coverage is thin. A suitable package makes the ordinary tasks easy to review, provides a usable correction route and lets a properly authorized backup retrieve the information needed to continue. Adding a complicated configuration has little value if no one can maintain it.
At the manager-input stage, the payroll operator depends on other people before starting. Supervisors approve hours, a benefits contact supplies a deduction change and the owner authorizes funding. The main constraint is getting complete, approved information into the correct run. A useful system shows missing approvals and changes clearly enough that the operator does not have to reconstruct them from messages.
At the coordinated stage, payroll must serve several recurring dependencies. Finance needs an allocation report, managers expect permissions for their teams, and a second work location brings another setup process. The purchase needs defined responsibilities and retrievable output across those dependencies. It might be a larger software package, a service that performs more processing, or a smaller package supported by a dependable external specialist.
These stages describe how the business operates. They are not employee-count limits, legal classifications or a requirement to buy a certain tier when the eleventh employee arrives. A six-person business with several work locations can need more coordination than a twenty-person office with stable salaries. Identify the actual change in the work before changing the software budget.
Ask each person involved to describe one recent payroll run and one difficult run. Record where time was spent, which information arrived late and what had to be repaired afterward. Keep the cause specific. An unapproved timesheet, a confusing pay-code setup and an accounting report that omits departments call for different remedies.
Include the person who will take over during an absence. Someone knowing the owner's password is not an acceptable coverage plan. The backup operator's permissions, instructions and approval authority should be established through the business's normal access process. Evaluate whether the proposed package lets that person perform the necessary work without giving unrelated access to employee information.
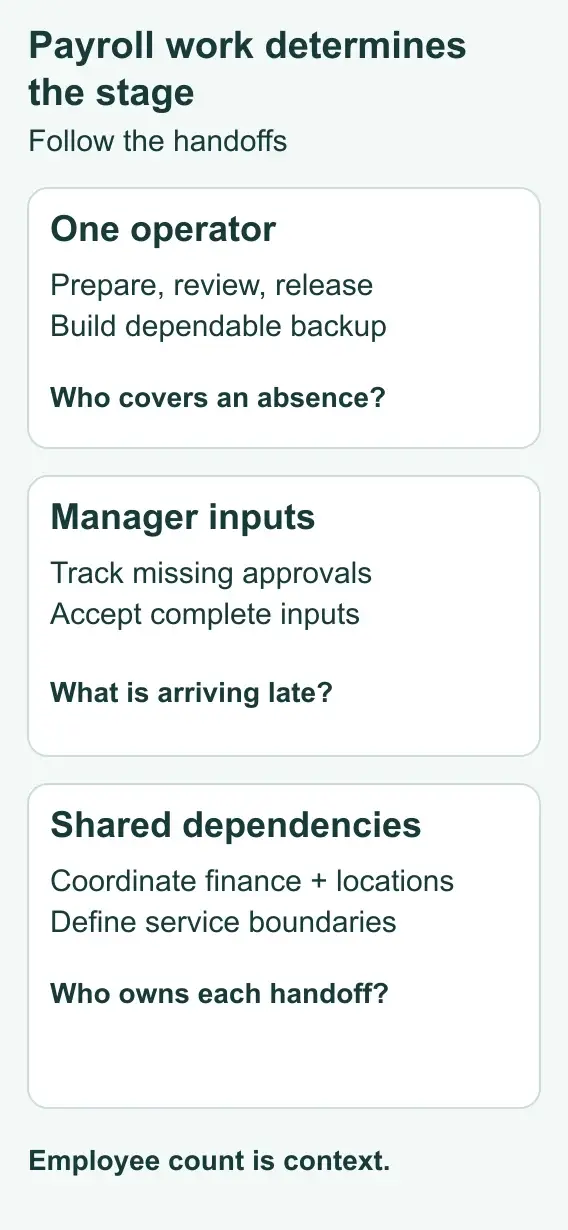
These operating descriptions follow the handoffs that must work, rather than an employee-count threshold.
Specify the service before comparing the interface
Payroll software and a person performing payroll work are different purchases. A subscription may calculate and submit an approved run while leaving data collection, review and correction decisions with the employer. An assisted or managed arrangement may perform additional tasks, but its boundaries need to be written down. Ask which tasks the provider performs, which it only advises on and which remain with your team.
Resolve the tax arrangement early. The IRS distinguishes payroll service providers, reporting agents, appointed agents and certified professional employer organizations. The type of arrangement affects responsibility. An employer using an ordinary payroll service provider generally remains responsible for timely federal tax deposits and returns. Do not treat a statement that taxes are automated as proof that every employer obligation has moved to the provider.
Request a plain description of what gets filed, under which employer identification number, when payment evidence becomes available and who receives agency notices. If a third party handles a notice, establish how you will know the matter is resolved. A payroll operator should be able to locate the relevant confirmation without depending on a former employee's login or a sales representative's recollection.
Check the package rather than the brand. For example, Gusto's current multi-state payroll page identifies Plus and Premium as the plans that include multi-state payroll. That is a reason to verify the actual subscription and work locations in the offer. It is not a general finding that every small employer needs one of those plans.
Intuit's current QuickBooks Workforce Premium page describes time tracking with submission and approval tools. A business evaluating that package should still demonstrate its own manager-to-payroll sequence, permissions and relevant conditions. The feature description establishes a candidate capability; it does not prove that your payroll operator's remaining workload will fit the cutoff.
Use the same distinction for an accountant or local payroll service. Get the person, scope, turnaround and backup arrangement identified. A responsive specialist can make a modest package workable. An undefined promise of help leaves the owner with the same unresolved tasks, even if the subscription itself looks inexpensive.
Write down the six jobs that stay with the business
Collect and complete inputs. Identify time, salary changes, new hires, departures and benefit instructions that must reach payroll. Specify who checks completeness and who chases missing information. When managers approve hours, test the manager approval cutoff separately from the provider's submission deadline. A faster payment feature cannot recover an afternoon spent locating unapproved time.
Check the proposed pay. Decide who compares the current run with the relevant instructions and previous run. Review the reason for a changed amount, not just whether the grand total looks familiar. The required check depends on the business: a stable salary payroll may have few changes, while variable hours require careful attention to the supplied time and earning detail.
Authorize funding and submission. Identify who may release the run and what that person reviews. Ask about the funding timetable, bank verification, account limits and fallback payment route applicable to the proposed service. Preserve the distinction between approving payroll, initiating a debit and employees receiving wages. Get the account-specific requirements confirmed before relying on an advertised payment speed.
Handle changes and corrections. Pick an example your team actually encounters, such as a missing-hours correction or an approved benefit deduction taking effect in the wrong run. Determine who can identify the original instruction, authorize the remedy, execute it and confirm the result. Reserve time for this work instead of assuming every future run will follow the clean demonstration.
Produce and reconcile the output. Have the bookkeeper name the register, tax detail, payment information and accounting dimensions needed. Review the actual posting or export in the intended accounting setup. For a QuickBooks-based business, request a posting in the intended edition and company file. If someone must add departments in a spreadsheet afterward, identify that person and the time required. A successful connection message does not establish a usable month-end result.
Maintain access, records and employee service. Include employee questions, address or bank-detail changes, report retrieval and backup coverage. For employees subject to the FLSA's minimum wage provisions or its minimum wage and overtime provisions, federal rules specify records of hours, pay and deductions. A convenient portal must still let the business obtain the relevant records. Keep the legal scope and retention instructions with the person responsible for the employer's records.
These jobs need not all belong to the same employee or happen during the same window. Separate preparation, pre-submission review and work due after payday. That separation prevents a task that can happen next week from crowding out today's release, while making sure later work is assigned rather than forgotten.
Estimate effort from a known run where possible. If the proposed workflow has only been described in a sales meeting, mark the time as an assumption and request a representative demonstration. Do not convert a provider's claim of a five-minute payroll into a five-minute budget for all six jobs. Time spent preparing inputs and handling exceptions belongs in your assessment even when it happens outside the software.
Complete a Small Business Payroll Workload Card
Copy the fields into a document for each proposed setup. Keep the ordinary and busy versions of a run distinct. For each of the six work rows, write the person who retains the task, the minutes expected in the relevant window, the evidence supporting that estimate and any assistance included in the quote. Use separate cards when the allocation of responsibilities differs.
Setup identity: Provider, exact package, separate services, employing business and proposed first pay date: ____________________.
Operating stage: Owner-led, manager-input or coordinated; the handoffs that establish that description: ____________________.
Required conditions: Work locations, worker and pay types, necessary approvals, funding requirements and service responsibilities that must be confirmed: ____________________.
Available windows: Preparation window, pre-submission window and later reporting window; responsible person and usable minutes in each: ____________________.
Input work: Retained owner; ordinary and busy minutes; completeness check, missing-information route and supporting sample: ____________________.
Pay-review work: Retained reviewer; ordinary and busy minutes; changes to inspect and the report or screen used: ____________________.
Release work: Authorized person; ordinary and busy minutes; funding review, submission requirement and backup: ____________________.
Correction work: Retained owner; ordinary and busy minutes; example, approval route, provider assistance and confirmation: ____________________.
Output work: Retained owner; ordinary and busy minutes; accounting destination, reconciliation work and required report: ____________________.
Access and service work: Retained owner; ordinary and busy minutes; employee requests, record retrieval and backup access: ____________________.
Capacity result: Total retained minutes for each person in each relevant window, available minutes and any excess or spare capacity: ____________________.
Unresolved assumptions: Missing demonstration, uncertain scope or estimated task time; person obtaining the answer and decision date: ____________________.
Next-stage change: A dated likely change, additional setup or recurring work, package or service change required and its owner: ____________________.
Chosen allocation: Work the employer accepts, work another named person or service accepts, and the documented reason the setup fits: ____________________.
Implementation check: Required first-payroll validation, retained records, training and the condition for accepting the operating arrangement: ____________________.
Add minutes only when they belong to the same person and window. Two people each having an hour does not give the payroll operator two hours. Likewise, a bookkeeper's availability after payday does not help the owner meet a funding cutoff this morning. Show the relevant window beside each total so the result can be checked.
A positive time balance is useful evidence, not a guarantee. Check whether the estimated steps can happen in the required sequence and whether the proposed backup is actually available. A task may depend on a report arriving from another service. Ten spare minutes do not resolve an unavailable input or an unanswered responsibility.
Keep a busy-run allowance grounded in a named situation. Examples include a late-approved timesheet, a new employee, a corrected deduction or a changed department. You do not need to estimate every imaginable incident. Choose the situations that already occur or follow from the next planned change, then establish who will act when something different happens.
Do not approve a setup while a required condition remains unresolved. A time total cannot compensate for an unsupported work location, an unacceptable permission arrangement or a missing tax responsibility. Carry that condition as an open question with an owner. If the purchase involves a formal requirements process, move the supporting details into that process rather than inventing another vendor ranking from the workload card.
Compare three small teams with different constraints
An owner working within a 75-minute window
Consider a fictional four-employee office with stable salaries and an established bookkeeper. The owner can devote 75 minutes to the pre-submission work. Under a proposed arrangement, completing inputs takes 10 minutes, reviewing pay takes 15, release work takes 5, correcting a small change takes 10 and necessary administrative work takes 15. The bookkeeper's later accounting work is assigned separately.
The owner's ordinary total is 55 minutes, leaving 20 minutes within the 75-minute window. The assumed busy version adds 25 minutes for an unusual instruction and confirmation. That produces 80 minutes, five more than the owner has. The ordinary run fits, but the busy version needs a specific adjustment.
The owner could arrange a trained backup to complete an eligible task earlier, move an input deadline or obtain assistance that actually removes five or more minutes from the relevant window. The proposal should identify the work being moved and the responsible person. Keeping the same package may be reasonable once the busy version has a workable route.
The lesson is narrow: a focused setup can fit a small owner-led business, but normal-run convenience is insufficient evidence of coverage. The fictional estimates do not establish the speed of any named provider. Use demonstrated tasks and actual availability to decide whether the proposed allocation fits your office.
Three supervisors supplying hourly time
A fictional service business with eighteen hourly employees and three supervisors has 60 minutes of payroll-operator capacity before submission. Its proposed busy run needs 30 minutes to complete inputs, 20 to review pay, 5 to release, 15 for changes, 20 for necessary output work and 10 for administration. All six tasks are assigned to that operator within the same window.
The total is 100 minutes. The gap is 40 minutes, not a small inconvenience that a cleaner screen can automatically fix. The buyer should identify the tasks creating that gap. If the first 30 minutes mostly involve chasing supervisors, an approval routine needs repair whether or not the software changes.
Suppose a demonstrated time workflow reduces the operator's input work from 30 minutes to 10. The new total is 80 minutes. It still exceeds the available 60 by 20. The team must identify another real change, such as the bookkeeper accepting the 20-minute output task in the agreed window, before declaring the package workable.
That is a different purchase from the office example. The important feature is a manager-input route that reduces documented retained work, together with a believable division of responsibilities. A plan upgrade may help, but only when the buyer identifies which task it removes, what it costs and who maintains the new workflow.

All minutes in this example belong to the same operator and window. A demonstrated task reduction must close the remaining gap.
A stable team adding a second work state
A fictional professional-services firm has six employees and a stable routine, but plans to add an employee working in another state. Its current payroll effort does not answer whether the package supports the new location, which registrations are needed or who supplies the setup instructions. The headcount remains small while the responsibility pattern changes.
Have the appropriate payroll or tax adviser establish the requirements for that location. Ask the provider to identify included service, excluded work, registration assistance, effective dates and any additional fee. Confirm the proposed subscription supports the arrangement before using an estimate of routine payroll minutes as the reason to keep it.
Make a separate next-stage card for the initial setup and another for the recurring run. One-time registration or configuration work should not be spread across a year's payrolls in a way that conceals next month's deadline. A stable routine may remain owner-led after setup, provided the specialist work and ongoing checks have defined owners.
These three companies need different evidence even though all could reasonably call themselves small businesses. The right recommendation is the allocation of work each can sustain, together with the package and assistance that support it.
Make the demonstration reveal retained work
Give each candidate the same fictional sample: an ordinary run, one meaningful change and the output your bookkeeper needs. Use representative pay types and departments while keeping real employee bank details, tax identifiers and sensitive personnel records out of a general sales exercise. Ask for a suitable demonstration environment or a sanitized sample.
Follow the task through the person who will perform it. Have the prospective operator identify the changed amount, the instruction authorizing it and the result after approval. When another party performs a step, request the handoff and expected response. A polished demonstration run entirely by the salesperson can show available functions without establishing whether your own team can use them.
Capture the remaining actions in the workload card. If the demo stops before a report is exported or a correction is confirmed, mark those tasks as unresolved. Distinguish an available function from a configured workflow and a demonstrated workflow from a contractual service commitment. Each answers a different question about the proposed purchase.
Review support at the point where the team would actually need it. Ask how the proposed service handles an issue shortly before the relevant cutoff, what the business can fix itself and how an unresolved matter is escalated. Do not infer response times from a support channel existing. Obtain the applicable hours, scope and any promised turnaround in the offer.
Bring the findings back to the people who will own the work. A bookkeeper can reject an export that looks convenient to the owner but cannot support the required allocation. A manager can identify an approval step that does not fit the shift schedule. Resolve those observations before treating the workload estimate as a finished buying decision.
Price the next change and preserve the way out
Get a quote for the setup that passed the capacity review, including the necessary package, separate services and recurring charges. Identify setup costs, worker charges, payroll-related add-ons, reporting or year-end services and the conditions for changing or ending the agreement. A headline monthly amount is incomplete when a required task depends on an extra service.
Keep the workload and cash comparisons separate. A provider that costs more may fit because it demonstrably removes a task your team cannot perform in time. A cheaper package may fit because the owner and bookkeeper deliberately accept a small manual step. Neither conclusion follows from a feature count or an untested estimate of future savings.
Choose one or two changes you genuinely expect, such as another work location, more variable time or the bookkeeper needing an additional accounting dimension. Request the package, service and implementation consequence of each. Avoid buying a complex configuration for speculative growth while ignoring a change already scheduled for next quarter.
Ask what happens to access and records when the service ends. IRS Publication 15 generally requires employment-tax records to be kept for at least four years, with longer rules for some credit-related records. The employer's retention schedule may also reflect other applicable requirements. Do not assume an account cancellation ends those responsibilities or that employee portal access is a substitute for an employer's retrievable archive.
Establish how the team will obtain records after leaving, including detailed pay history, tax returns and confirmations, and the information necessary to explain adjustments. Test the proposed export or request a representative example before accepting a portability promise. Name who will retain the archive and manage any continuing access needed for unresolved matters.
When changing providers, define the switching timetable around actual payroll, funding and reporting obligations. Identify who handles earlier-period corrections and who verifies the first run under the new arrangement. A purchase can meet future needs and still fail during implementation if the old and new services assume the other party owns a task.
Decide whether to repair, upgrade or replace
Repair the process when the problem is a missing approval, an unclear instruction or an unassigned review that the existing system can support. A replacement will not make a supervisor supply accurate time without an agreed routine. Confirm the repair on a representative run and update the workload card with observed effort.
Upgrade the package or add help when a demonstrated capability or a defined service removes the specific constraint. Check the new price and responsibilities before accepting the change. More features may create setup and maintenance work of their own, so include that work in the revised card rather than counting only the task supposedly saved.
Replace the provider when a necessary work location, pay treatment, control, output or service arrangement cannot be supplied acceptably, or when the retained work remains beyond the team's realistic capacity after practical repairs. Keep the failed requirement and supporting evidence in the decision record. This gives implementation a clear target rather than a vague expectation that the new system will be easier.
After the first runs, compare the real allocation with the accepted card. Confirm that the reports are obtainable, the backup can continue the work and the promised service handles the assigned tasks. Revise an estimate that proved wrong. Review the setup again when a material operating change occurs, using the changed task and available capacity to decide the next action.
Explore the Decision Guides library.
Continue with payroll operations and controls.

About the author
Ben Scott writes and maintains payroll decision guides for founders and operators. His work focuses on execution realities and how decisions hold up under growth, complexity, and controls and documentation pressure. He works hands-on in HR and leave-management roles that intersect with payroll-adjacent workflows such as benefits coordination, cutovers, and compliance-driven process controls.


