
Payroll Review Checklist: Reconcile the Run Before Release

Updated: 5 hours ago

A payroll total can match last cycle while two employees are paid incorrectly. A reviewer can approve the right register while someone releases a later version. A sufficient bank balance can still sit in the wrong account for the provider's debit. Final review has to connect the calculated results, the supporting decisions and the actual payment instructions.
Final review ends in one of three decisions about a specific calculated run: approve the verified version, return it for correction, or escalate a defined issue with a timely payment response. Perform it after the inputs have been accepted and payroll has been calculated, while corrections can still follow a supported process. A list of completed tasks without that decision leaves the release operator guessing.
The checks assume routine US employer payroll. They do not supply a jurisdiction's wage rules, an employer's tax calculation or a bank's acceptance deadline. Apply the rules for the workers, work locations and payment arrangements involved. The original Payroll Release Review Record below helps retain the evidence without turning a shared checklist into a copy of everyone's private payroll data.
Contents
Read the review packet as a description of one run
Start with the employer or entity, pay group, pay period, payment date and payroll identifier. Add the calculation version or report export time. Establish whether the packet includes regular pay only, an off-cycle payment, manual checks or several batches. A familiar report name is insufficient when the application can regenerate its contents under the same name.
Open the register, change report, exception list and funding instructions together. They should describe the same calculation. If a tax report came from an earlier preview, or a funding notice excludes a manual payment included in the register, establish the difference before treating the packet as internally consistent. Label intentional differences rather than making every report appear to agree by changing its scope.
Input acceptance establishes what payroll was asked to process. Final review establishes whether the calculated result reflects those instructions correctly. Keep the input acceptance reference available, but avoid repeating every intake question. Where an expected source is still missing, return that question to its owner and decide what the gap prevents you from reviewing.
Identify the person who prepared the run and the person reviewing it. Use a reviewer with enough access and knowledge to challenge the calculation, with independence appropriate to the risk. In a small team where one person performs several functions, arrange a documented second-person check of sensitive changes and the release totals. Do not label a self-review independent merely because it happens later in the day.
Record the latest usable provider or bank acceptance point and the time reserved for correction and renewed review. These are operational constraints to verify with the actual service. They do not replace the applicable wage-payment deadline. A review that finishes after the only workable payment window needs an escalation response, even if every number is correct.
Account for every expected payment
Compare the calculated population with the people expected to receive pay, including new hires, departures, leave cases, one-time payments and prior corrections. Use stable worker identifiers in a restricted report. Names alone can hide duplicate records or confuse two people with the same name.
Distinguish a person count from a payment count. One employee may receive a direct deposit and a separate check, or allocations to two accounts. An unchanged number of payment records does not prove the same employees are present. Conversely, an additional payment does not necessarily mean an extra person was paid.
Build a short population explanation: who was added, who was excluded, whose payment method changed and why. Confirm that an exclusion is supported by the actual circumstances. A termination status does not establish that no wages remain due, and a leave status does not determine every benefit, salary or statutory-pay result.
Examine zero and negative net results separately. Zero may be correct for a genuinely unpaid period, but it may also reflect a missed earning, duplicate deduction or failed calculation. A negative result requires a supported treatment and an explanation of what will actually happen to the employee's payment. Do not assume that a negative preview automatically creates an authorized debt collection.
Look for duplicate employee records, duplicate payments and unexpected recipients. A previously paid correction can appear again when a manual check was entered without the appropriate offset or status. Trace the original payment and the current record before removing anything. The goal is to establish both the wages recorded and the money already delivered.
For covered nonexempt employees, federal recordkeeping rules identify information such as hours worked, pay basis, additions, deductions, total wages and payment dates. That is a useful starting point for the evidence a review needs. It is not a federal requirement to use this particular checklist, and additional worker-specific or state requirements can apply.
Explain change without letting offsets cancel
Compare the run with an appropriate baseline. The preceding payroll is useful only after accounting for different working days, payment frequency, bonuses, seasonal populations and other known changes. A monthly salary run and a bonus run should not be expected to have the same relationship between headcount, gross pay and net cash.
Work from the employer total down through pay groups, earning categories and employees. Suppose the previous comparable gross was $116,000 and the current run is $120,000. An initial explanation identifies $3,000 for new hires, $1,800 of additional overtime and an $800 reduction for departures. Those movements bridge the $4,000 increase, but each explanation still needs its underlying evidence.
Next, test whether the bridge hides offsetting mistakes. In a fictional case, Employee A's gross is $300 too high because a one-time earning was duplicated. Employee B's gross is $300 too low because an approved earning was omitted. Their combined variance is zero. The employer's $120,000 total and the $4,000 bridge can both remain correct while the individual results are wrong.
Review changed and unusual results at employee level, including amounts below a company reporting threshold when their nature warrants attention. An internal dollar threshold can prioritize investigation; it does not authorize an underpayment, an unlawful deduction or a suspicious payment destination. Define both amount-based flags and event-based flags, such as a new bank account or an unexplained zero payment.
Close an investigation with a reason, evidence reference and result: the difference is expected, the calculation has been corrected, or a specific unresolved issue requires a decision. Descriptions such as "variance reviewed" do not tell the approver whether an amount was explained or merely noticed. If several cases share a cause, verify that the correction reaches the whole affected population.
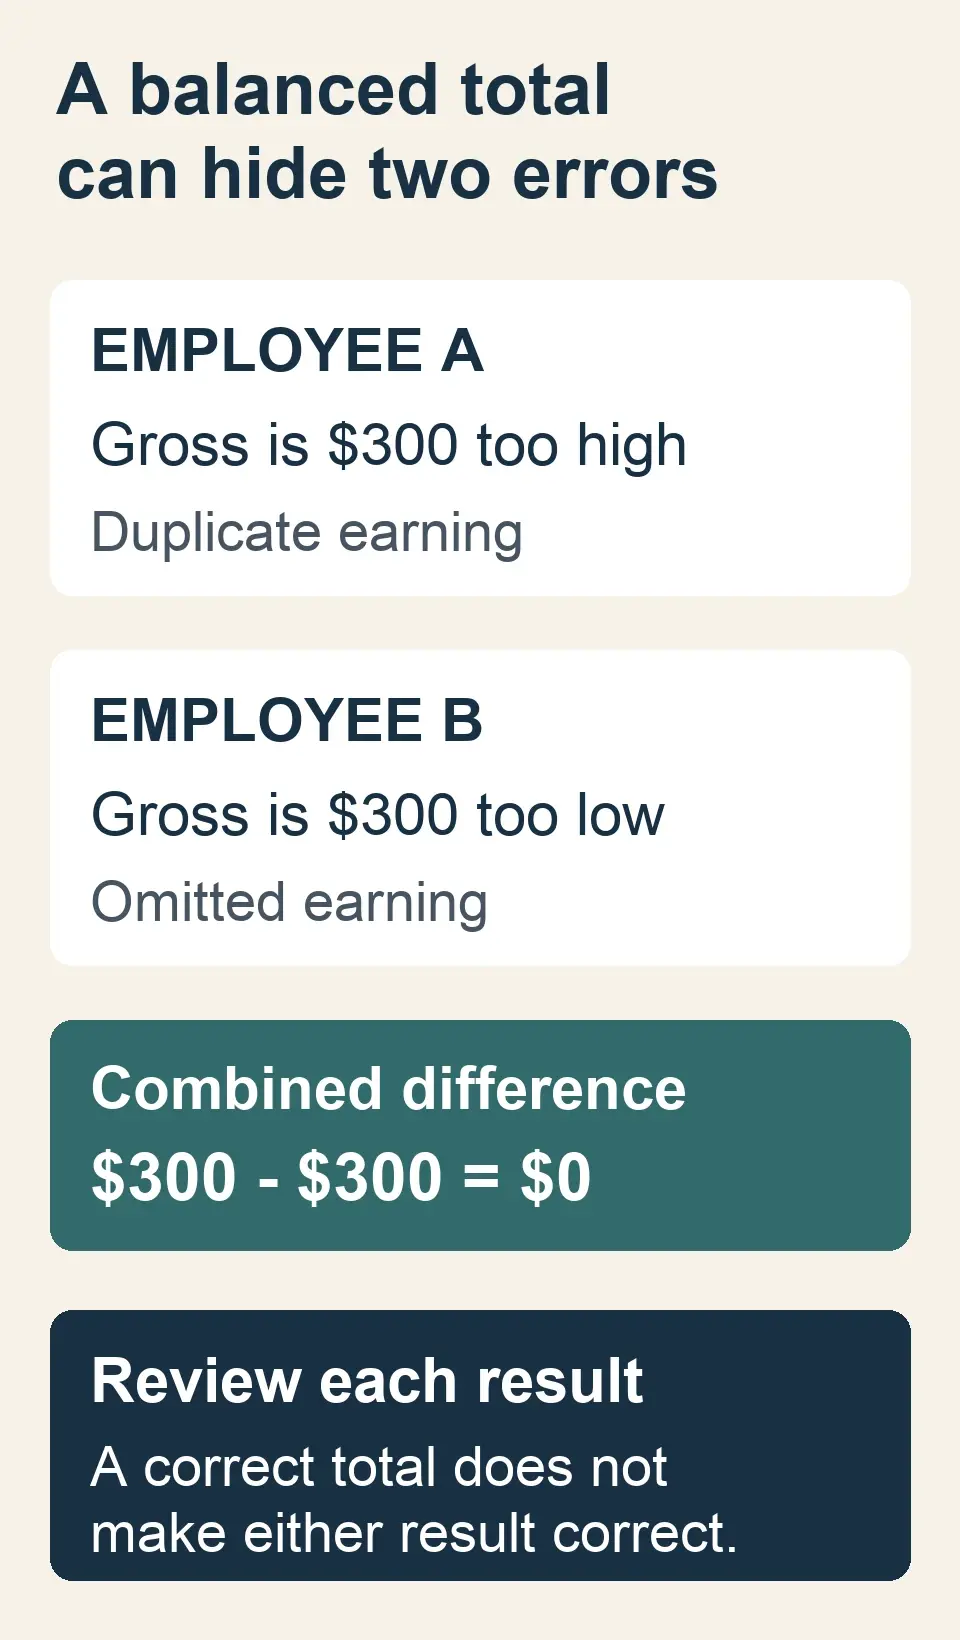
Review the employee results behind an apparently balanced total. The fictional amounts above illustrate offsetting errors, not an acceptable error threshold.
Test the wage calculation at its boundary
Select calculations that could expose an incorrect rule or setup, rather than choosing only large, familiar salaries. Appropriate checks can include a changed rate, overtime across assignments, a nondiscretionary payment, a mid-period start or departure, and a correction to previously paid time. Determine the expected treatment before comparing the system output.
The federal default for covered nonexempt workers uses the workweek, not the total hours in a biweekly payroll period, to determine overtime. Averaging hours across two or more weeks is not permitted under that general rule. Exemptions, special arrangements and applicable state rules require their own analysis; a payroll review cannot infer the correct treatment simply from an employee's job title or a software label.
For a deliberately simple fictional example, an employee earns $25 an hour and works 50 hours in the first workweek and 30 in the second. Assume ordinary federal overtime applies, there are no other includable earnings and no additional state requirement affects the example. Eighty hours at straight time produce $2,000. The ten first-week overtime hours also require a half-time premium of $125, for $2,125 gross.
Reviewing only the 80-hour pay-period total would miss that premium. The evidence must preserve the division between workweeks. If the worker has several rates, bonuses or another relevant earning, the regular-rate calculation needs a broader check than this illustration. A salaried payment also needs the correct legal and factual treatment rather than an automatic assumption that salary eliminates overtime.
Trace a changed rate from its authorization and effective date to the affected hours and earning code. Check the resulting gross, not merely the presence of a new rate in the employee profile. A correct current profile can coexist with a run calculated before the change. Keep the earlier and corrected outputs distinguishable when the review sends the run back for recalculation.
Trace deductions and withholding to their basis
Start with the applicable tax setup, current employee instructions and the treatment of each earning or benefit. Federal income tax withholding depends on the relevant withholding method and Form W-4 information. A deduction described as "pretax" does not, by itself, establish identical treatment for every federal, state or local tax.
For an unexpected result, compare the actual wage base, employee election, effective date and calculation method with the expected setup. Use the current IRS withholding instructions for the method involved. Do not force a tax amount to match the prior payroll solely because the current amount looks unfamiliar. A change in taxable wages or a valid employee instruction can produce a legitimate difference.
For benefit deductions, reconcile the result to the applicable enrollment and payroll instruction. Check starts, stops, catch-up amounts, arrears and cases where available pay is insufficient. Separate the employee deduction from an employer contribution. Their effect on employee net pay and the employer's cash obligation is different, even when a carrier invoice combines them later.
Review orders and statutory deductions using their applicable requirements, including limits and priorities where relevant. An employee authorization is not a universal answer to whether a deduction is permitted. Federal wage protections can restrict deductions for the employer's benefit, and state law can add requirements. Route uncertain treatment to the appropriate specialist before imposing it through payroll.
Record the basis of a corrected deduction or withholding result and verify the recalculation. Where a prior-period error is involved, identify whether tax reporting, benefit records or a later remittance also needs action. Changing this run's net pay can resolve the employee's immediate result while leaving another record incorrect. Assign those follow-up obligations explicitly.
Match the register to dated cash movements
Reconcile employee net payments and the other cash obligations separately. Gross wages are not normally the same amount as the payroll provider's debit, and the provider may take several debits on different dates. Establish what each requested amount contains, which account it will use and who will verify that money is available when required.
Consider a fictional run with $120,000 of gross wages and $1,500 of separately identified cash reimbursements. Assume $28,200 of employee tax withholding and $8,300 of employee benefit or other deductions. These are invented, already-validated control totals for an arithmetic example, not tax rates or a model for classifying reimbursements.
The cash payable to workers is $85,000: $120,000 plus $1,500, less $28,200 and $8,300. Suppose $80,000 will go by direct deposit and $5,000 by checks. The two payment methods must add to the same $85,000, with the relevant recipients and payments accounted for.
Now assume $10,400 of employer payroll taxes and a separate $250 provider fee. The tax cash obligation represented by these example totals is $38,600, combining $28,200 withheld from employees and $10,400 owed by the employer. The $8,300 of deductions still needs its appropriate remittance or other supported disposition; it is not additional wages.
If all those obligations require cash, the example totals $132,150 across worker payments, tax remittances, deduction remittances and the fee. The same amount is $120,000 gross wages plus $1,500 reimbursements, $10,400 employer taxes and $250 fee. Do not add employee withholding and deductions on top of gross wages again. They are already included in the gross-to-net relationship.
Use actual dated instructions to replace this simplified picture. A provider might debit net pay and taxes together while checks are funded through another route. An employer contribution, noncash earning, prior credit or retained deduction balance can change the reconciliation. Mark amounts already paid or intentionally remaining as liabilities so that an arithmetic total does not become a duplicate payment instruction.
Federal employment tax deposit schedules are distinct from payroll frequency. IRS Publication 15 bases the relevant deposit rules on tax liabilities and applicable schedules, including special rules. A payroll run being approved today does not establish when every tax must be deposited. Confirm the actual obligations and provider acceptance requirements rather than copying the employee payday onto all remittances.

The calculation is a control illustration. Replace its assumed obligations with the actual supported amounts, debit dates and payment routes.
Inspect where the money will go
A correct net amount can reach the wrong account. Review payment destinations, recent changes and permissions as a separate check from wage calculation. Match the payment file or provider batch to the reviewed employee records using the information the authorized reviewer can safely access.
Independently verify sensitive account changes through an established route. A message claiming to come from an employee, even inside a familiar email thread, is not sufficient evidence by itself. The Minnesota Office of the State Auditor recommends contacting the employee directly in person or using a reliable phone number when verifying a direct-deposit request. Do not use a new phone number supplied only in the suspicious request as its own verification.
Keep full bank details out of the general review record. Use a restricted evidence reference and enough masked information to distinguish the approved destination. An unusual shared account or identifier is a reason to investigate, not automatic proof of fraud; legitimate household arrangements and setup errors require different responses.
Confirm file and batch controls: entity, payment date, payment count, total amount and intended funding account. Use the provider's supported review or validation facility. A local file that looks correct is not proof that the provider accepted it, and a screenshot of a successful upload may omit a rejected payment within the batch.
If a destination cannot be verified before the acceptance window, identify a supported, lawful alternative for paying the worker on time. Do not release unverified instructions simply because the wage calculation passed. Equally, do not treat a security investigation as permission to leave a wage obligation without a named payment response.
Document a decision for every unresolved result
Use clear outcomes with explicit scope. Approve means the identified version and payments have the required evidence. Return for correction means a specified result must be rebuilt and checked again. Escalate means a named decision maker must resolve a question that the reviewer cannot responsibly settle. These are review outcomes, not a claim that every payroll application implements the same workflow.
Separate an unresolved employee result from uncertainty that affects the whole run. One incorrectly calculated payment may be capable of correction or separate handling through a supported process. An incorrect tax mapping or an unexplained register-to-file difference may affect many people. Establish the extent of the problem before deciding whether an unaffected portion can move.
Do not assume that an application can split a run safely. Verify the supported route, its effect on wages, deductions, taxes and funding, and the authorization needed. Retain a complete record of who is paid through each route. A spreadsheet note saying "hold this person" does not prove that the submitted file excludes the payment or that the remaining wage obligation will be met.
A hold on an instruction is not a new wage-payment deadline. Applicable state rules can impose different requirements for regular and final wages; California's published payday guidance is one example of why those rules need separate review. Obtain advice for the actual jurisdiction and circumstances, including how to pay established amounts while another component is being resolved.
For every issue still open at approval time, identify the affected payment or obligation, the unresolved fact, the decision owner, the latest usable action time and the fallback. If the matter has been accepted under a documented policy, record what that acceptance covers and the evidence supporting it. An approval cannot convert an unlawful treatment into a lawful one.
Payroll Release Review Record
Use one record per run or genuinely separate release scope. Keep the answers in native document rows or a restricted working file, with evidence linked by reference. Do not paste full Social Security numbers, bank accounts or sensitive employee narratives into a broadly shared checklist.
Use the same version reference throughout. Enter actual findings and amounts rather than checking a box labelled "reviewed." Where a field does not apply, state why. An unanswered field remains unresolved until the reviewer can explain its effect on the release decision.
Run and review scope
Employer, pay group and pay date: ____________________
Period, run ID and calculation version: ____________________
Reports and input acceptance reference: ____________________
Preparer, reviewer and review coverage: ____________________
Acceptance cutoff and correction window: ____________________
Keep separate scopes separate. Record whether manual checks, off-cycle payments or other batches are included in these answers.
Calculated results
Population differences and payment counts: ____________________
Gross movement and employee outliers: ____________________
Hours, rates and wage-calculation evidence: ____________________
Withholding and deduction support: ____________________
Open findings, owners and dispositions: ____________________
Refer to the detail that supports each answer. A reconciled employer total does not replace the employee checks needed to explain a known difference.
Money and destinations
Net payments by method and batch: ____________________
Tax, deduction and other cash obligations: ____________________
Funding accounts, amounts and debit dates: ____________________
Sensitive destination-change verification: ____________________
Register-to-payment control agreement: ____________________
Distinguish an amount requested for funding from a payment that has already been accepted or settled. Name any supported reconciling item.
Approval and follow-through
Decision and exact version approved: ____________________
Blocking issues and timely payment route: ____________________
Late changes and repeat-check evidence: ____________________
Approver, release operator and timestamps: ____________________
Acceptance and settlement follow-up owner: ____________________
Complete the approval fields before release and the acceptance or settlement references when those events occur. Preserve the original decision if a later correction changes the outcome; add the linked correction record instead of rewriting history.
Reopen the checks that a late edit can affect
Suppose version 2 passed review at 10:20 and a manager supplies a missing six-hour time entry at 10:35. The preparer recalculates version 3. The 10:20 approval does not establish that version 3 was reviewed, even if the application leaves an approval badge on screen. Identify the new calculation and determine what the change can affect.
For version 3, show the approver what changed in the worker's result, the approved run totals and the payment instructions. Establish any overtime, withholding, deduction, net-pay or funding effects before naming the replacement totals. Identify which generated files or accounting outputs must be rebuilt and compare the actual replacement batch with the newly approved record.
State what the renewed approval covers. A supported change report may justify checking the affected results; uncertain or wider recalculation requires broader review. Retain the difference report and repeat-check evidence so a focused review cannot be mistaken for approval of an unchanged run.
If the original instructions were transmitted already, stop and establish their actual status before submitting another batch. A second upload can create a second payment where someone expected a replacement. Use the service's supported cancellation, correction or additional-payment procedure and confirm its outcome. Review records should identify both the original instruction and the action taken against it.
The approver should receive the changed result, the repeated-check evidence and the revised release instruction. An expired acceptance window may require a different payment route, not just a new signature. Notify the people who will fund and release the run of the version they should now use, and withdraw obsolete instructions from their active queue.
Keep approval separate from release and settlement
Approval records the decision about a particular payroll. Release is the authorized action that sends or commits payment instructions through the actual service. Settlement is a later money event. Retain evidence for each stage that occurs; one screenshot cannot prove all three.
The release operator should match the approval reference to the run or batch on screen, including its entity, date, population and amount. Reviewers need a way to see meaningful changes made after approval. Where permissions allow the same person to alter sensitive data and release payment, implement an appropriate second-person control rather than relying on a broadly worded policy alone.
After submission, inspect the service's acceptance result and any payment-level rejects. Retain confirmation identifiers and distinguish pending, accepted, rejected and cancelled instructions according to the provider's documented meanings. "Processed" can describe different stages in different services; confirm what it establishes before telling an employee that money arrived.
Assign follow-up for returned payments, missing deposits, rejected tax instructions and deduction remittances. These do not disappear because the pre-release review was completed correctly. Finance should receive the approved version and the later payment evidence needed to reconcile it, with open items and their owners visible.
Preserve supporting records under the requirements that apply to them. DOL rules generally require payroll records to be kept for at least three years. Underlying wage-computation records have a separate two-year federal requirement. Employment-tax records have their own IRS requirements, and certain tax-credit records require longer retention. Apply the appropriate schedule and any legal hold; the date a review checklist was completed is not a universal destruction date.
Make the next review easier to perform
Introduce the checklist by walking through an actual recent run with its preparer, reviewer, approver and release operator. Identify which report proves each answer and who can obtain it. If a required report cannot be produced, decide on a supported alternative or a documented control gap before the next deadline.
Reserve time for calculation, review, correction, renewed approval and release as separate activities. Confirm who covers an absent reviewer and how the substitute obtains the restricted evidence. A backup who has authority but no usable access can leave the team unable to complete the control when it matters.
Use the first completed records to identify recurring friction: unexplained earning changes, duplicate manual payments, unsupported bank updates, stale funding notices or edits after approval. Improve the report, ownership or system step that causes the repeated work. Measure unresolved results and late changes rather than rewarding the number of boxes ticked.
If software limitations keep preventing review of a fixed version, employee-level changes or release permissions, take those specific cases into a supported demonstration with the current provider or a prospective service. Ask what is included in the actual package and which work remains with your team. Do not infer that a generic approval feature locks calculations, verifies bank changes or guarantees payment delivery.
The next run should leave a usable trail from the expected population to the calculated result, the approved version and the payment instructions that actually moved. Start with the control that currently breaks that trail. Retain the evidence needed to challenge it, give unresolved obligations an owner and make the release decision about the version the operator will use.
Browse the Decision Guides library.
Continue with Payroll Operations & Controls.
Use the Payroll Operations Resource Library for full guides with embedded tools.

About the author
Ben Scott writes and maintains payroll decision guides for founders and operators. His work focuses on execution realities and how decisions hold up under growth, complexity, and controls and documentation pressure. He works hands-on in HR and leave-management roles that intersect with payroll-adjacent workflows such as benefits coordination, cutovers, and compliance-driven process controls.


