
Payroll Software for Accountants: Decide Which Clients Your Firm Can Support

Updated: 2 days ago

Twenty clients on one payroll platform can still mean twenty different services. One owner supplies approved hours and releases payroll. Another expects the accounting firm to chase timesheets, approve adjustments and answer every employee question. A third needs the firm only at month-end. Choosing a common login does not make those commitments the same.
For an accounting practice, the useful purchase decision is whether a named payroll setup supports the work the firm has agreed to perform for a particular client. Establish that service boundary, prove the important workflows and decide which exceptions the practice can sustain. A preferred provider can simplify training without becoming the right answer for every employer.
This guide covers U.S. accounting and bookkeeping practices recommending, preparing or reviewing client payroll. Use the Client Payroll Acceptance File to document intake, requirements and the recommendation. Its fields and examples are an original operating framework, not a vendor certification or a report of hands-on product testing. Separate tax, legal and professional advice may be needed for a client's particular arrangement, including S-corporation owner pay and benefits.
Table of contents
Agree on the service before selecting the platform
Describe the recurring service in verbs that both the firm and client understand. Who collects approved time, prepares the run, reviews changes, authorizes release, handles notices and reconciles the result? “Payroll support included” leaves all of those jobs open to interpretation. A written scope should also address the work the firm will refer elsewhere.
A client-operated service can mean the owner prepares and releases payroll while the practice reviews the accounting records at close. A firm-prepared service can mean staff prepare payroll from approved inputs while an authorized client reviewer approves release. A firm-operated service can include preparation and release within an agreed authorization. These are proposed operating models, not legal categories or statements that any vendor can enforce them.
For each job, identify the performer, the approving person where needed, the deadline and a backup. A vendor's default role called “accountant” does not answer whether the user can edit wages, submit a payment or change a bank account. The scope must agree with the actual permissions and the client's authorization.
Keep the software arrangement distinct from employment tax liability. In the ordinary payroll service provider or Form 8655 reporting-agent arrangements, the employer remains responsible for its federal employment tax obligations. The IRS explanation of these arrangements expressly states that neither arrangement relieves the employer of that responsibility. Other third-party arrangements have different rules and require separate assessment.
Software access, a signed engagement and an agency authorization also do different things. Record which authorization supports filing or payment activity and which agreement defines the firm's service. Do not assume a dashboard invitation appoints a reporting agent or authorizes the firm to make every payroll decision.
Set the practical boundary around late changes. If approved hours arrive after the agreed preparation window, who decides the available payroll route and tells the client about the consequence? The provider's processing deadline remains relevant even if the client missed the firm's earlier deadline. Staff need a defined escalation rather than an informal promise to make every late payroll work.
The boundary should remain visible after onboarding. Attach the current service record to the client's working file, include it in staff handovers and revise it when the client changes its expectation. A new payroll administrator or a new location can change the work substantially without changing the number of employees.
Collect the facts that would change your recommendation
Start intake with the most recent completed payroll and the next known change. A headcount estimate helps with subscription budgeting, but it cannot reveal whether the client supplies clean inputs, operates in unfamiliar jurisdictions or expects detailed job reporting. Ask for evidence of the workflow the firm will inherit.
Pay and timing. Record pay frequencies, ordinary pay types, variable payments and who approves time. Note where hours are stored and whether corrections arrive after approval. Ask about the last off-cycle run and what caused it. The requirement may be an earlier client cutoff or a controlled correction route rather than a more expensive subscription.
Jurisdictions and responsibilities. Record the employer entities, current work locations and planned changes. Identify who verifies registrations, tax settings, unemployment accounts and any local requirements. This intake locates questions for a qualified reviewer; it does not decide the correct tax treatment from a state count.
Deductions and external handoffs. Identify benefits, retirement contributions, garnishments and other deductions that require someone outside payroll to supply or confirm an instruction. Record both the input owner and the person who verifies the destination. A provider processing a deduction does not establish that the underlying instruction was approved or that the related payment reached its destination.
Accounting requirements. Ask for the chart of accounts, the payroll liability review, relevant departments or jobs and the intended close date. Distinguish a client satisfied with a monthly summarized journal entry from one requiring department detail on each run. Save an example of the actual report the accountant must deliver.
Existing problems and history. List unresolved notices, missing returns, prior-period corrections and records that are unavailable. Establish who owns the remediation and whether onboarding depends on it. A platform change can create another set of records while leaving the original problem unanswered.
People and access. Identify the client decision-maker, the firm preparer, the reviewer and their backups. Record whether the employer needs independent access to records. Ask what happens when a client leaves the practice or a staff member leaves the firm.
Keep a client's sensitive records in the practice's approved system. The acceptance file can refer to the evidence location without copying Social Security numbers, employee bank details or raw payroll files into every selection document. For tax professionals, the IRS guidance on written information security plans explains that safeguarding client information requires a plan appropriate to the practice. Vendor security features are one input to that plan.
Complete intake with unresolved questions, an assigned reviewer and a due date. “Unknown” is useful information when it prevents a premature recommendation. An unanswered requirement should stay visible until the firm can determine whether it changes the service scope, the proposed platform or the acceptance decision.
Establish a practice default with two exception routes
A default platform is useful when it supports a defined group of clients with similar service needs. It gives the practice a repeatable training path, permissions design, report package and support procedure. Define the group by the workflows the practice can perform reliably, and record the conditions under which a client leaves that group.
Use three service lanes: standard, documented exception and specialist referral. They are choices for the practice's operating policy, not labels supplied by the payroll vendor.
Standard service uses the practice's normal preparation and review process. The client meets the intake requirements, the proposed package has demonstrated the necessary functions, and the firm can provide backup coverage. A standard client may still have occasional corrections; the point is that the practice has a supported way to handle them.
Documented exception means the client needs a different package, platform or manual step that the practice has deliberately accepted. Name the additional work, its owner, the evidence retained and the price or scope consequence. An exception without a backup is a personal arrangement with one employee rather than an established firm service.
Specialist referral is appropriate when the practice cannot support the required work with its expertise, staffing or provider arrangement. The client may need a specialized payroll service, legal review or a different service engagement. Referral is an acceptance decision, not a declaration that the client's chosen software is defective.

Choose the service lane from the firm's demonstrated support for the client's requirements. A preferred platform does not erase an unsupported exception.
Review exceptions together across the client portfolio. A separate manual step taking ten minutes may be reasonable for one client and significant when repeated across thirty clients on the same deadline. The same portfolio review can reveal when an exception has become common enough to justify a different standard process.
Avoid mandating a migration merely to increase the number of clients on a partner program. First identify the problem the move would solve and the evidence needed for acceptance. A functioning client setup may remain a reasonable exception when its outputs, access and support fit the agreed service.
Complete the Client Payroll Acceptance File
Create one file for one client and one proposed payroll package. Copy the following labels into the practice's approved working system and fill them from intake and demonstrations. Keep it narrow enough to read on a phone. Use evidence references rather than embedding employee records.
The file combines a client intake checklist with a requirements rubric. A requirement is blocking when the practice cannot accept the proposed service without it. It is conditional when a defined workaround is acceptable. It is a preference when it improves convenience but does not determine acceptance. Decide the category before hearing how attractive a demonstration looks.
Client intake record
Service promise: Record whether the client, firm or provider prepares, reviews and releases payroll. Name the client approver, firm owner and backups. Include the agreed input deadline and escalation route.
Payroll shape: Record pay frequencies, pay types, time source, usual correction patterns and the next known change. Identify which facts came from completed records and which remain estimates.
Location review: Record entities and work locations, the qualified tax reviewer and outstanding registration or treatment questions. Add the evidence reference and decision date.
Other instructions: Record who approves benefits, retirement and garnishment instructions, who enters them and who verifies the related output. Name any service explicitly excluded.
Accounting deliverable: Record the company file, account and dimension requirements, reports needed, close deadline and reviewer. Identify one ordinary output and one correction output to demonstrate.
Open history: Record unresolved notices, prior balances, missing records and the person responsible. State whether each item must be resolved before moving or can be handled under a separate documented plan.
Repeat this requirements record for each deciding requirement
Required result: Write a concrete outcome, such as “a preparer assigned to Client A cannot enter Client B's payroll.” Avoid broad entries such as “good controls.”
Importance: Choose blocking, conditional or preference. Explain the effect on this client's service if the requirement fails.
Demonstration: State the exact task, account role and payroll type to be shown. Include the relevant change or failure path where appropriate.
Evidence and result: Record the dated report, screenshot, export or documented answer and whether the result was demonstrated, partly demonstrated or unverified. A marketing promise belongs in the unverified category until the relevant evidence is obtained.
Remaining work: Describe any workaround, its performer, reviewer, backup and expected frequency. Record whether its effort was measured in a trial or merely estimated.
Acceptance decision
Service lane: Choose standard, documented exception or specialist referral. List unresolved blocking requirements and accepted conditions separately.
Commercial and exit terms: Record the named package, bill payer, ordinary recurring cost, additional fees, the firm's service fee and the route for exporting records or transferring account access.
Decision and review point: Record the firm decision-maker, the client agreement, accepted conditions and the next review event. A new jurisdiction, lost backup or changed integration can be a review event even when no scheduled renewal is near.
Do not average away a blocking failure with several successful preferences. A supplier with a polished dashboard and attractive partner terms can still fail a client's required approval route. Keep that result visible and ask whether a different configuration, package or provider can resolve it.
For conditional requirements, define acceptance precisely. “Staff will handle this” is incomplete. “The assigned bookkeeper downloads the register after each run; the backup can access the same report; the reviewer checks it against the journal entry by the close deadline” is a workable condition to evaluate.
Demonstrate access and approval using the proposed roles
Ask to see the proposed setup as the actual preparer and reviewer. An administrator performing every demonstration can make unavailable permissions look available. The firm's account-level access and the staff member's rights within a particular client need separate inspection.
Use two fictional client accounts where a vendor demonstration or authorized trial permits it. Assign a preparer to the first account, confirm the intended visibility of the second, then reassign coverage to a backup. Check who can grant access and how access is removed. Use invented payroll data, not an existing employee's records.
OnPay's partner dashboard permissions distinguish members who access their assigned accounts from administrators who can view all accounts and manage user access. That supports a specific question for an OnPay evaluation: does the proposed firm role and client-level role give each staff member the intended scope?
Intuit's current custom-role documentation distinguishes client roles from firm roles and includes payroll among permission areas. Confirm the actual permissions in the offered Intuit account and subscription rather than assuming the role name alone provides separation.
Then demonstrate preparation and release as different tasks where the engagement requires that separation. Change one fictional pay item, request review, show what the reviewer sees and determine what happens if the run is edited afterward. Save the record that connects the reviewed version with the submitted result.
Gusto's payroll approval documentation states that approval coverage varies by payroll type; contractor payroll and certain other off-cycle types are excluded. It also documents differences in permission setup. A successful regular-payroll demonstration therefore cannot establish that every correction or contractor payment follows the same approval route.
Ask who retains an ability to bypass the desired workflow. Broad administrator access may be necessary for account maintenance, but it should have an identified owner and review procedure. A feature called approval does not itself establish that no authorized administrator can submit directly.
Record the result for this client's required payroll types. These examples use public vendor documentation reviewed on October 13, 2026. They identify questions to demonstrate, not comparative scores, an exhaustive feature list or a claim that the practice has tested those systems.
Require an accounting result and a notice route
The firm needs to see what happens after payroll is submitted. Have the candidate produce the output required by the client's accounting deliverable: register, journal or export, liability detail and the records needed to identify a correction. Check the destination company, accounting period and department or job detail that matters to the engagement.
Trace one ordinary payroll into the intended accounting record. Then demonstrate a correction affecting an earlier run. Identify whether the correction produces a separate entry, updates an existing posting or leaves manual work. Record who prevents duplicate expenses when bank activity and payroll journals both reach the books.
A balanced journal does not establish that the right client's wages reached the right accounts. Compare the source register and the required expense, liability and dimension detail. If the practice accepts a summarized output, record that choice and what information remains available for later questions.
Keep accounting evidence distinct from filing and deposit evidence. Under ordinary payroll service provider and reporting-agent arrangements, the employer's continuing responsibility makes the tax monitoring route part of client acceptance. Agree who will review deposit and filing records and who will investigate a missing record or notice.
For Form 8655 reporting-agent arrangements, the IRS describes a required quarterly written statement advising the client of its continuing responsibility and recommending EFTPS enrollment to monitor its account. Record the applicable arrangement and its monitoring method; do not invent an agency role from a provider's marketing description.
An accountant should also determine how the retained payroll records support the employer's obligations. The Department of Labor's recordkeeping guidance describes records of hours worked and wages earned for covered nonexempt workers. Ask how the selected time and payroll systems preserve the required information and how it can be retrieved after a switch.
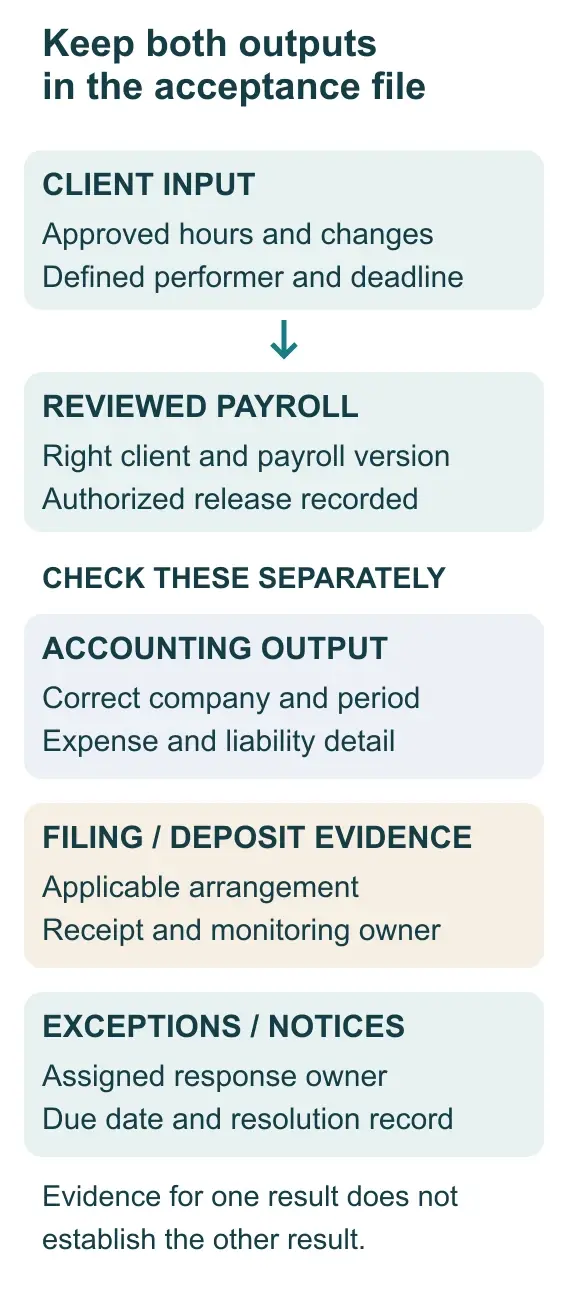
Retain evidence for each required result. Accounting reconciliation and tax monitoring have different outputs and owners.
Test the notice workflow before an actual urgent notice arrives. Ask where the client sends it, who obtains provider assistance, what authorization the provider requires and how the firm records response dates. Determine whether prior-provider periods are covered. “Support will help” is insufficient when the notice concerns a filing outside the new provider's engagement.
Price the client service and the portfolio burden
Build the commercial comparison around the named package and the proposed service. Record the subscription, employee or contractor charges, additional payroll or filing fees where applicable, implementation costs and other required subscriptions. Verify the quote directly; public prices and partner terms can change.
Show the bill payer and the practice's service fee separately. A client billed by the provider and a client billed through the firm may have different commercial arrangements without different payroll requirements. Gusto's accountant partner information describes a centralized client-management offering, but a partner dashboard does not settle the firm's fee, authorization or service commitment.
Include work that survives the purchase. Estimate staff preparation, review, exception handling, monthly close and notice support using the actual client mix. Mark estimates clearly and replace them with observed effort during an authorized trial when feasible. Do not present a vendor's time-saving claim as a measured result for your practice.
Consider a fictional practice with twenty similar clients. Candidate A costs $10 less per client each month but requires an extra manual export taking twelve minutes per client. If that step occurs twice monthly, the extra work is 480 minutes, or eight hours. At an assumed internal cost of $60 per hour, the modeled labor is $480 against $200 of subscription savings.
The example does not establish either candidate's real cost or prove that manual exports are unacceptable. It shows why the practice should identify the repeated step and price its consequence. The decision may differ if the export takes two minutes, occurs monthly or already belongs to a profitable service package.
Review the busiest shared deadline as well as the monthly average. Twenty clients needing the same reviewer on Friday morning create a coverage question that an annual cost model can hide. Establish how the proposed workflow distributes preparation, approval and backup work across that window.
Make onboarding and departure part of acceptance
Before moving an accepted client, document the first payroll date, the last run in the old setup and which party handles each filing period. Resolve year-to-date balances, tax setup and open issues with the responsible reviewers. A completed import is not evidence that the resulting records reconcile.
Choose a first live review appropriate to the client. Confirm approved input, actual permissions, pay results, accounting output and available filing or payment evidence. Keep open conditions visible until their required evidence arrives; an unavailable future filing receipt is different from a failed receipt for a completed period.
Build absence coverage from the demonstrated roles. A backup should be able to reach the assigned client, find the service record and perform the necessary work without a shared password or undocumented permission change. Decide who supplies approval if the usual client reviewer is unavailable.
Specify the departure route before it becomes urgent. Confirm who controls subscription billing, who can grant or transfer account access, what exports are available and whether records remain accessible after cancellation. Verify the terms for the named service. Do not promise permanent access merely because records are available today.
The employer may leave the practice while keeping the provider, change providers while retaining the firm or close its business. Those paths require different access and record handovers. Identify the person who removes firm access after the necessary handover, preserves the agreed working records and confirms that future payroll responsibilities have been reassigned.
Apply the recommendation to the client you actually have
A stable eight-employee client supplies approved hours, releases payroll itself and wants a summarized monthly accounting packet. The practice can choose its standard service if access, reports and tax-monitoring responsibilities are demonstrated. Firm-wide administrative access or elaborate custom reporting may add little to that particular engagement.
A growing hourly client expects the firm to prepare weekly payroll and maintain job reporting. Its deciding requirements include approved time, workable review, corrections and the required accounting detail. If a different package produces those results with a defined extra close step and backup, a documented exception can be sensible. Price the step and record the acceptance condition.
A client with unresolved tax registrations, missing prior-period records and payroll requirements outside the team's competence should not be admitted to routine service because the platform can create an account. Assign the unresolved work to appropriate specialists and reconsider acceptance when the evidence supports it. Changing software alone does not create the missing expertise or history.
These fictional cases illustrate a recommendation based on service fit. Select a practice default for a supported client group, approve specific exceptions that have owners and coverage, and refer work the firm cannot sustain. Keep the completed acceptance file with the client engagement so the next staff member can see what was agreed and what still requires attention.
Explore the Decision Guides library.
See the Payroll Operations & Controls hub.

About the author
Ben Scott writes and maintains payroll decision guides for founders and operators. His work focuses on execution realities and how decisions hold up under growth, complexity, and controls and documentation pressure. He works hands-on in HR and leave-management roles that intersect with payroll-adjacent workflows such as benefits coordination, cutovers, and compliance-driven process controls.


