
Payroll Override Controls: Authorize the Change, Prove the Result

Updated: 2 days ago

Imagine a manager authorizing a $600 manual payment. Payroll issues the check, finance sees the bank entry, and everyone considers the problem resolved. The next regular run then pays the same earning again. Each person completed an assigned task, but nobody proved how the manual payment changed the employee's remaining payroll instruction.
Control a payroll override by defining the exact departure you are permitting, approving its calculation and checking what actually happened afterward. The authorization needs an employee or defined population, a pay component, a processing version, a payment deadline and an end point. A general instruction to fix payroll leaves too much for the operator to decide alone.
After choosing an exception route, U.S. payroll, HR and finance teams can use the Override Case Sheet to control manual checks, forced values and temporary bypasses. Work through the pay example, deduction-pause scenario and replacement-payment decisions to see what each transaction needs. These controls are practical operating recommendations; applicable wage-payment rules, tax instructions, benefit terms and other obligations still govern the result.
Contents
Define what the override will change
Use the word override for a deliberate departure from the normal calculation, setup or processing route. Then name the departure precisely. Correcting an approved pay rate in the source record, typing a replacement net amount and issuing a check outside the usual payment file create different work. A single exception can involve more than one of them.
Start by asking whether the correct result can still be produced through the supported ordinary process. If an approved time correction can be entered and recalculated safely, forcing an earnings total may leave an unnecessary second source of truth. Correct the underlying instruction where practical, retain the change evidence and review the resulting calculation.
Sometimes the ordinary route cannot deliver the required payment in time. A service outage, an unavailable authorized reviewer or a payment already released can require another route. Establish which part of the process is failing and which actions remain possible. An internal cutoff does not by itself determine whether earned wages may be delayed.
Decide separately whether money is owed, which processing action is permitted and who may release the payment. The person confirming hours may have no authority to change a withholding instruction. A person approving a manual payment may still need finance to authorize its bank release.
For federal overtime, the general payment rule ties compensation to the regular payday for the period in which the workweek ends. The limited allowance for amounts that cannot yet be determined requires payment as soon as practicable, with an outside limit described in 29 CFR 778.106. It is not a routine extension for an employer's approval queue; assess applicable state and other payment requirements as well.
Preserve a result you can compare
Before editing, save the employee calculation or affected batch as it actually stands. Identify the run, version, extraction time and source instructions. A screenshot can show a particular screen, but a useful evidence set also explains which employees and components it covers and how the reviewer can inspect the relevant detail.
Record the current value, the expected value and the reason for the difference. Keep gross earnings, taxable wages, deductions, employee taxes, employer costs and net pay separate where the change affects them. “Increase payment by $600” is incomplete when nobody has established whether $600 describes gross earnings, take-home pay or a reimbursement under a particular treatment.
Define the expected result independently of the value about to be typed. Use approved hours and rates, a documented pay instruction, a benefit administrator's valid direction or another appropriate source. Copying the processor's proposed number into a second approval field does not provide an independent calculation.
Include the scope that should remain unchanged. A correction for one employee should not silently alter another employee, a recurring rate or a later pay period. If the system recalculates more broadly, identify what additional output will need review. Preserve enough detail to detect an unintended effect beyond the requested line.
The recordkeeping rules for covered employees include hours, relevant earnings, additions and deductions, wages paid, and the payment date and period. Those requirements in 29 CFR 516.2 help explain why a payment amount alone is insufficient evidence. Your case record should point to the underlying payroll records; keep personal detail in those controlled records instead of copying it into the case.
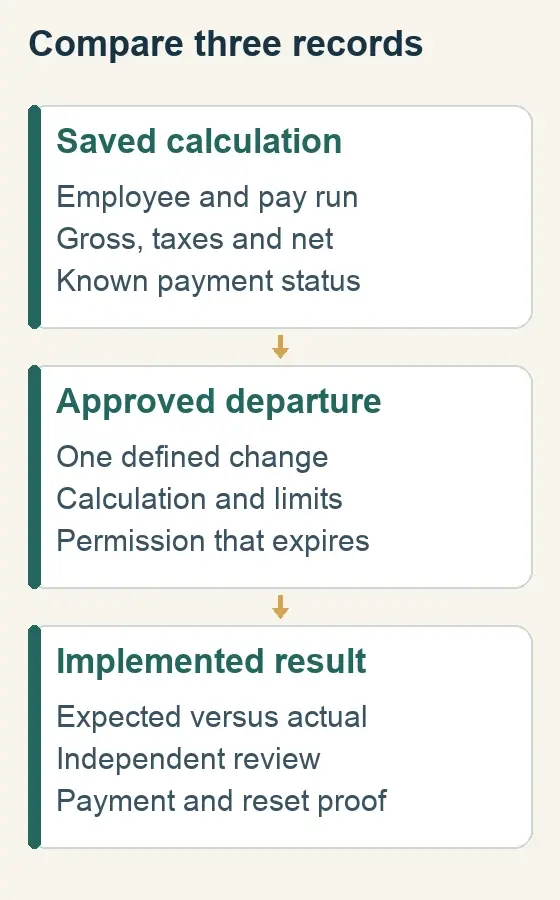
Keep the original result, permission to change it and evidence of the implemented result connected by one case reference. The approval cannot substitute for either calculation.
Authorize a bounded departure
Write an instruction that another competent processor could execute without guessing. Name the employee reference or controlled employee list, the pay component, the affected work period and the allowed action. Where amounts are still provisional, specify the calculation basis and the point at which the final amount must return for review.
Make the approval expire. An authorization may apply to one run, one payment or a defined date range. A temporary suppression should identify the instruction it replaces and the condition for restoring normal processing. Avoid an open-ended permission to adjust values whenever the same warning appears.
Assign an approver with authority over the underlying decision and an independent reviewer of the implemented result. They may be the same suitable person when the work and access permit it. Independence means the reviewer can challenge the change and inspect the evidence; a second account operated by the processor does not create a second judgment.
For a small team, name an owner, finance lead or qualified outside reviewer who can provide a meaningful check. Give that person the calculation and access needed to review it. If a genuine emergency prevents a normal review sequence, follow a preapproved emergency route with explicit limits and a prompt independent follow-up. Do not describe a review performed after payment as though it occurred before release.
Reject instructions that cannot be tied to valid authority, a supportable calculation and a permissible payment route. Escalate the missing decision to the responsible owner while continuing to address any wage-payment obligation. An approval gap requires action; it must not disappear into a log entry saying pending.
Treat forced tax and deduction values differently
A manager's desired net payment is not a tax instruction. When federal income tax withholding looks unusual, inspect the employee's effective withholding certificate, taxable wages, pay-period treatment and calculation method. The IRS publishes current federal income tax withholding methods; use the method applicable to the payment rather than forcing a familiar-looking result.
Distinguish a verified correction to an input from an unsupported override to an output. If the employee has submitted a valid change, establish when it becomes effective and preserve the instruction. If the payroll setup is wrong, correct and test the setup through the appropriate route. If treatment remains uncertain, obtain the necessary tax or provider support before asserting that a hand-entered amount is correct.
A deduction pause needs its own basis. An insurance premium, retirement contribution, recovery of an overpayment and a court-directed deduction should not share one generic bypass permission. Identify the arrangement involved, what change is permitted, who can authorize it and whether a balance or later collection instruction must change.
For example, assume a benefits administrator confirms that an employee's premium was already collected in an earlier special run. A one-run deduction pause might prevent duplicate collection, but it also needs a comparison with the earlier posted amount, the current deduction and the next scheduled collection. Preserve the continuing benefit instruction unless an authorized change to that instruction is actually intended.
Do not recover an employer loss by casually forcing a payroll deduction. Federal minimum-wage and overtime protections can be affected by employer-benefiting deductions, as illustrated in 29 CFR 531.35. State rules can impose additional restrictions.
California's Labor Commissioner, for example, describes specific limits on deductions from wages. That is a California example, not a nationwide authorization standard. An employee's agreement or a manager's signature should never be treated as proof that every proposed deduction is lawful.
Work a missing hour through gross and net
Consider a fictional employee paid solely at $28 per hour for one established workweek. Assume the employee is covered by the federal overtime rule, worked 45 hours and has no other compensation or applicable additional premiums in this example. The imported time contains only 44 hours.
Under the single-hourly-rate calculation described in 29 CFR 778.110, the intended gross is 40 hours at $28 plus five overtime hours at $42. That produces $1,330. The 44-hour preview produces $1,288, so the omitted hour changes gross by $42.
The $42 difference does not establish the amount of a manual check. Payroll still needs the correct tax and deduction treatment, what has already been paid and the supported correction procedure. Promising $42 of extra take-home pay would introduce another decision that the missing-hour evidence does not authorize.
Suppose the original preview has not been released. The cleaner instruction may be to correct time to 45 hours, regenerate the employee calculation and review the $1,330 gross alongside the resulting deductions and net. The authorization identifies that corrected input and the new preview version. A gross-only comparison would leave the payment calculation unreviewed.
If the original payment has already been released, first establish its actual status and the appropriate additional-payment route. The correction should account for the wages and withholding already recorded. Do not overwrite the historical check as if it had never existed simply to make a current screen match $1,330.
Finally, inspect the next regular instruction. The corrected hour must remain in the work record, while the payroll process must recognize any amount already paid through the correction. Removing the hour to avoid duplicate pay would trade a payment problem for an inaccurate time record. The provider's supported adjustment and recording process must reconcile both.
Make a manual payment visible in payroll
A manual check has at least three connected views: money issued or settled, payroll wages and deductions recorded, and amounts carried into tax and accounting work. Giving finance a check number addresses only part of that chain. Decide how each view will be updated before asking someone to issue the payment.
Establish whether the action will generate new money, record money already issued or do both. Payroll systems use different names and procedures for manual checks, adjustments and off-cycle runs. Confirm the actual behavior in your provider's supported process; a screen labelled manual does not establish that another payment will be suppressed.
Attach the payment reference to the payroll calculation and the case reference to the finance record. Record the payment date, affected earning period and relevant status. Have a named person verify that the payroll register contains the intended wages, taxes, deductions and net amount without recreating the same cash instruction.
Then reconcile the next affected regular run. Check whether the earning remains payable, whether the manual amount has been recognized and whether any temporary deduction or payment suppression is still active. A case is not ready to close merely because the employee has received money.
A replacement check needs particular care. Confirm what happened to the original payment with the bank and provider before issuing a replacement. An unresolved payment may still settle; the replacement could therefore create a duplicate. The available stop, void, cancellation or reissue procedure depends on the actual route and status.
Replacing cash already represented by correct payroll earnings is different from correcting an incorrect wage calculation. Record which problem the replacement solves so that payroll does not create wages or reverse tax history unnecessarily. If an overpayment has already occurred, assess the separate recovery and correction requirements rather than treating the employee's next wages as a convenient clearing account.
Changing a current preview also differs from correcting a return already filed. The IRS explains how employment tax returns are corrected, including the use of the applicable adjusted return. Assign any required reporting correction explicitly; editing a payroll display does not establish that a filed return has changed.
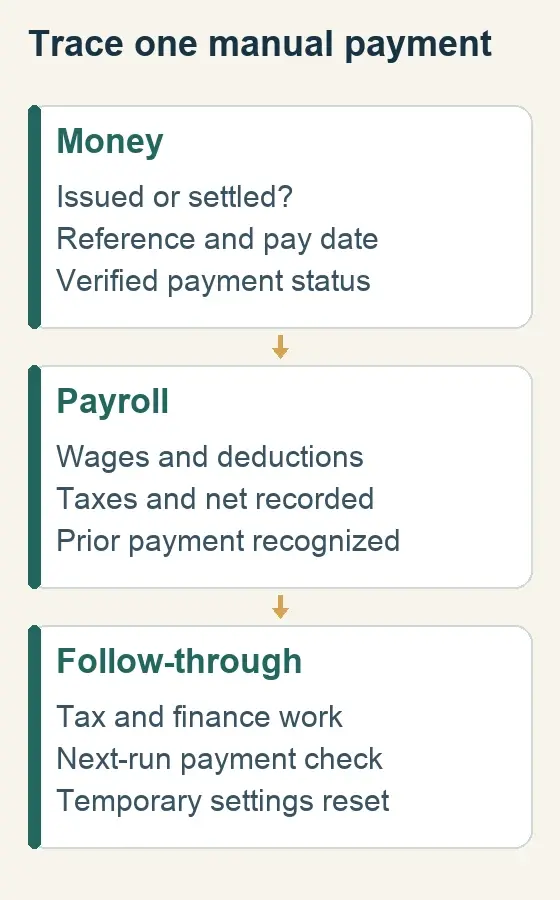
Prove each view separately. A bank reference shows a payment event; the payroll record and reporting work need their own evidence.
Review the implemented result before release
Give the reviewer the approved instruction, the saved before-state and the actual updated preview. The comparison should show what changed, what should have changed and what remained outside the authorization. Record the version reviewed so a later adjustment cannot silently inherit the earlier approval.
Check the affected employee in detail, then inspect the relevant company or batch totals. Equal batch totals can conceal two opposite employee errors. If one employee's earning rises by $100 while another falls by $100, an unchanged gross total cannot establish that either change was authorized.
Follow the consequences of the specific override. A rate correction may affect overtime or another calculated component. A deduction pause may leave a balance to collect later. A manual payment can change the remaining funding need. Select checks from those consequences, rather than asking reviewers to sign a long list of unrelated boxes.
If a second change occurs after review, identify which earlier evidence is no longer valid. Regenerate the affected calculation and return it for the appropriate review. Do not retain an approval attached to an old screenshot while allowing the live value to move.
Give release authority the reviewed result and any remaining conditions. An employee-specific override does not automatically approve the whole company payroll. Likewise, a company-level release approval should not be used to conceal a missing decision about a sensitive individual change.
After release, verify the payment's supported status and reconcile the register and finance evidence. Record a failed or uncertain outcome honestly, with the next action and owner. A provider acceptance message can be valuable evidence, but it should not be relabelled bank settlement unless that is what it actually confirms.
Use the Override Case Sheet
Copy the fields below into a controlled case record. Use references to restricted employee, tax and payment evidence; do not paste bank credentials or complete personal records into a widely shared worksheet. Each numbered field is a separate entry, with the explanatory notes kept outside the entry.
Before changing anything
1. Case and scope: Case ID; employee reference or controlled list; legal employer; work period; affected run.
2. Saved before-state: Calculation version and time; current values; evidence location; payment status already established.
3. Reason for departure: What ordinary process cannot achieve; why a source correction or supported recalculation is insufficient.
Keep the original evidence available even after the system shows the corrected value. The case should explain the choice without requiring the next reviewer to reconstruct an earlier screen.
Permission to act
4. Allowed change: Component; exact action; authorized amount or calculation basis; items that must remain unchanged.
5. Supporting basis: Approved pay, time, deduction or tax instruction; expected-result calculation; specialist determination where needed.
6. Deadline and expiry: Required payment point and its basis; latest usable processing opportunity; end of this permission.
7. People and authority: Decision approver; processor; independent result reviewer; payment-release owner; any conflict or emergency condition.
An incomplete calculation basis or unresolved legal treatment is an open decision. Identify who will resolve it before presenting the case as executable.
Execution and proof
8. Implemented version: Operator and time; changed input or field; new calculation version; supported procedure used.
9. Independent result check: Expected versus actual employee values; affected totals; unchanged-scope checks; reviewer and time.
10. Payment evidence: Release authorization; actual payment reference, date and status; outstanding delivery or settlement check.
11. Payroll and reporting record: Posted payroll reference; tax and accounting follow-through; duplicate-payment check for the next affected run.
Keep the check results alongside the evidence references. A blank field is not a pass, and an unresolved payment status needs a follow-up rather than a guessed completion date.
End the exception
12. Reset confirmation: Temporary setting restored or valid continuing instruction confirmed; verifier; effective run.
13. Closure decision: Remaining work and owner, or completed checks and closure authorization; employee communication reference where needed.
14. Cause and repair: Source defect; permanent fix owner; agreed review date; related earlier cases.
Use a separate repair task when the payment can be fully reconciled before the system defect is fixed. Keep that task linked and open; do not make the payroll case appear unresolved in every respect, or falsely describe the underlying defect as repaired.
Keep the exception log useful and restricted
Use the log as an index to cases, rather than as a second payroll database. A useful row identifies the case, period, type of departure, status, responsible person, deadline and evidence location. Include enough categorization to distinguish a forced amount from a manual payment or temporary setup bypass.
Keep authorization, processing, payment and repair status distinguishable. A case can be approved but unprocessed, paid but unreconciled, or financially closed with a repair task still open. A single complete flag hides the action somebody still needs to perform.
Limit access according to the information and decisions each role needs. A manager may need to confirm work performed without seeing another employee's deductions. A finance reviewer may need payment and accounting evidence without broad access to withholding certificates. Put sensitive supporting records behind the appropriate access controls.
Set retention by the records involved and applicable obligations. Under the FLSA rules, covered payroll records generally have a three-year minimum from the last entry under 29 CFR 516.5. Specified supporting time, earnings and deduction records have a two-year minimum under 29 CFR 516.6.
Federal employment-tax records have separate requirements; the IRS's 2026 employer tax guide states a minimum of four years. Do not turn those different minimums into an automatic deletion date for the whole case. Apply any longer applicable rule, preservation hold or contractual requirement through the organization's retention process.
Preserve the sequence of decisions when a case changes. Add the amended instruction, new evidence and reason the earlier authorization ceased to apply. Editing the original log description until it looks as though the final result was always intended destroys the history the review needs.
Close the override and repair its cause
Close the payment case after the authorized result, payment evidence, payroll recording and relevant follow-through have been checked. Confirm that temporary changes have expired or been restored. Name any continuing work separately, with an owner and a date for checking it.
Look for recurrence by cause and affected process, not just by the label manual check. Six cases arising from the same deduction setup may deserve one repair. Six legitimate final payments arising from separate events may indicate a functioning exceptional route. The count alone does not establish which conclusion is right.
A useful review asks what would make the next comparable case unnecessary or easier to control. The answer might be correcting an interface mapping, restoring a missing approval field, arranging backup authority or obtaining a supported provider procedure. Assign that specific action and verify it on a later relevant transaction.
Keep amount and consequence together when deciding escalation. A small unauthorized tax override or recurring deduction error can matter beyond its dollar value. Use the employer's materiality and correction policy to make that assessment, while preserving obligations that cannot be waived through an internal tolerance.
Avoid making fewer logged cases the team's sole success measure. That can discourage recording exactly the work the organization needs to understand. Review late payments, unsupported changes, duplicate payments, unexpired bypasses and repeated source failures alongside the volume of legitimate exceptions.
Test the controls your system actually supports
Before relying on an override policy, rehearse a representative case in a safe test environment or through a provider-supported demonstration. Ask the operator to preserve the before-state, enter only the authorized change and give the reviewer the actual resulting evidence. Do not experiment with a live employee payment merely to discover what a button does.
Try a changed amount after approval, a temporary deduction suppression and a manual payment recorded after cash has already been issued. Establish which action creates money, which action changes payroll records and which action invalidates earlier approval. Include the next run when testing whether temporary settings and duplicate-payment controls work.
Ask to see who can change the approval, backdate an entry, restore an old value or grant themselves a stronger role. A written separation of duties cannot be assumed to exist in the system. Where the platform cannot enforce a needed restriction, decide whether an independent compensating check is reliable enough for the actual payroll workload.
Record limits in the operating procedure and service agreement where relevant. Define who performs a tax correction, who can retrieve historical change evidence and who handles an unavailable processor. A demonstration can establish what was shown under its stated conditions; it cannot promise that every future exception will be resolved correctly.
Keep the procedure usable during an ordinary absence. A backup should be able to find the approved case, understand the permitted change and identify the next unfinished action. That is the practical test of the record: another person can complete the work without inventing authority or guessing what has already been paid.
Browse the Decision Guides library.
Continue with Payroll Operations & Controls.
Find practical tools in the Payroll Operations Resource Library.

About the author
Ben Scott writes and maintains payroll decision guides for founders and operators. His work focuses on execution realities and how decisions hold up under growth, complexity, and controls and documentation pressure. He works hands-on in HR and leave-management roles that intersect with payroll-adjacent workflows such as benefits coordination, cutovers, and compliance-driven process controls.


