
Multi-State Payroll Setup: Approve the Location Before the Pay Run

Updated: 4 days ago
Before activating payroll for an employee in another state, establish where that person will work and who has reviewed the resulting tax and account decisions. A home address, an assigned office and the place where services are performed can be different. Payroll needs a supported relationship between those facts, the employer's registrations, employee certificates and the first affected payment.
Use the Work Location Release Test in this guide for an out-of-state hire, a move, a recurring hybrid arrangement or a previously unreported location. It helps a payroll reviewer decide whether a particular setup is ready to use. It does not determine an employee's tax residence or supply a fifty-state tax calculation. U.S. agency sources were checked October 14, 2026; the worked situations are fictional.
Start the review while the proposed arrangement can still be clarified. If work has already occurred, record the actual facts and escalate the affected payroll periods. A company approval date cannot substitute for the date services began, and a missing setup approval is not permission to delay wages.

If residence, worksite and registration records do not agree, SelectSoftware Reviews offers a no-cost advisor conversation about payroll services. Ask each provider which location decisions and account tasks remain with your team.
Table of contents
Establish the location facts before choosing a tax code
Ask for the employee's residence, the physical places where work will occur, the expected pattern and the first day of that arrangement. Identify the employing legal entity as well. A location already registered for one subsidiary does not establish that a different employer has the account it needs.
Keep mailing details separate from the work record. An employee may change a mailing address without changing where services are performed. A person may also work temporarily from a different state while keeping the same home. Give a temporary work request its own dates and expected return, rather than silently replacing the permanent location field.
For recurring work in several places, describe the pattern in terms that can later be checked: scheduled office days, customer visits, home-work days and exceptions. Distinguish the plan from the actual service record. A three-day office schedule tells the reviewer what to investigate; it does not prove that every week followed that schedule.
Use an employee confirmation and the manager's operational knowledge to resolve inconsistent inputs. If a manager says the employee remains assigned to headquarters while the employee reports a permanent move, retain both statements and ask the responsible reviewer what each fact means. Do not edit away the disagreement so a payroll import will accept the record.
Choose an authoritative employee record and name who may change each field. Residence, worksite, assigned office and tax configuration need not share the same source. The release record should identify those sources and their versions so a later integration does not overwrite the reviewed setup with an older address.
Give each obligation its own answer
Income-tax withholding, unemployment coverage and local obligations can use different rules. Have the reviewer record the authority and conclusion for each relevant layer. A single dropdown labelled work state is an inadequate explanation when the actual treatment spans several agencies.
Federal income-tax withholding. The IRS describes Form W-4 as the employee's certificate for federal withholding. Obtain and handle it under the federal instructions. It does not, by itself, document a state reciprocity claim, local tax jurisdiction or unemployment determination. Keep the applicable state certificates with the separate decisions they support.
State income-tax withholding. Check the employer rules for the work and residence jurisdictions, including sourcing, reciprocity, required certificates and any applicable exception. The answer may involve withholding in more than one state or a supported exemption from one state's withholding. An employee's expectation of a credit on an individual return does not replace the employer's withholding instructions.
Unemployment insurance. The U.S. Department of Labor's localization guidance describes a sequence: localization of services first, then qualifying base-of-operations, direction-and-control and residence tests when the earlier tests do not decide coverage. The relevant tests include whether services are performed in the state being considered. Residence is not automatically the first answer. Confirm the applicable state agency's treatment of the employee's actual arrangement.
Local and other state obligations. Check local wage taxes, disability or paid-leave programs, workers' compensation and applicable wage rules with their responsible agencies or advisers. These are separate review questions, not a claim that every program applies to every employee. Pennsylvania's local-tax resources, for example, distinguish residence and work-location information and provide an official address search for political subdivision codes and rates.
Record a supported not-applicable conclusion where appropriate. Otherwise, a blank local-tax field can mean either no obligation or no review. Those are different outcomes. A conclusion should name the jurisdiction, the issue considered, the source used and the person responsible for the decision.
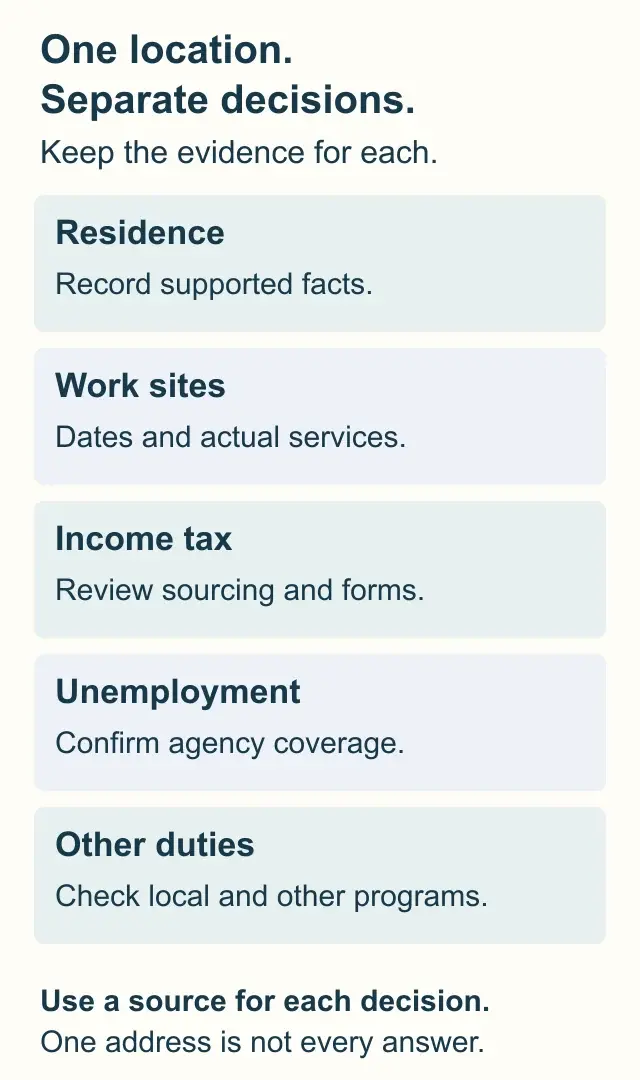
A residence record and a service record supply facts. Each obligation still needs its own reviewed treatment.
Confirm accounts and authority to file
After determining the employer's obligations, verify which accounts, registrations and service authorizations are needed. A state tax code appearing in software is a configuration option. It is not evidence that an agency accepted the employer's registration or that a provider is authorized to file for that entity.
California illustrates why this work needs a dated owner. EDD's general business registration guidance identifies paying more than $100 in wages in a calendar quarter as a registration trigger and requires registration within fifteen days. Employer categories have different rules, including household employment. Check the agency guidance rather than applying that example to every employer or every state.
For each required account, retain the legal name, employer identifier, agency account number, effective information and registration status. Keep sensitive identifiers in the approved restricted record; a general project tracker can point to that record. Assign an owner to an outstanding agency request and record the actual deadline separately from an internal target date.
Confirm the service boundary with the payroll provider. Who obtains the account? Who receives notices? Who enters the rate or account number? Who submits the return and supplies filing evidence? An onboarding specialist's completed task can coexist with an unresolved employer registration. The first payroll reviewer needs to know which result was actually achieved.
Also check filing and payment readiness. A correct employee tax calculation will not prove that a debit authorization, agency filing credential or employer account mapping is usable. Obtain appropriate confirmation before relying on the service, without exposing access credentials in the release packet.
Check for an existing account before requesting another registration. The prior payroll provider may have used an account that belongs to the employer, even when the current administrator cannot yet access it. Establish the legal entity and agency record, then decide whether access recovery, a service authorization or a new registration is actually needed. Creating another software account is a different action from obtaining another agency identifier.
Plan account closure separately when someone stops working in a state. Ask the account owner to review other employees, remaining reporting periods, balances and the agency's closure instructions. Moving the last employee visible in one payroll group does not prove that the employer has no other covered activity. Preserve the old account and filing evidence while that review occurs, and record who will confirm the closure outcome. A location change should not silently turn off a shared filing obligation needed by another employee or entity record.
Preserve three dates and the affected payroll periods
Keep the date work began in the location, the date payroll learned of it and the payment dates affected. Record any different date on which a specific approved tax or account treatment takes effect. Those dates may coincide, but making them identical for convenience hides a late report or an unresolved retrospective issue.
Identify the service periods and payments that the reviewer must examine. The treatment of a particular earning can depend on its facts and applicable rules; a current location value alone cannot explain a bonus for earlier services or a payment issued after a move. Give unusual compensation to the reviewer with its earning period and payment history.
Use effective-dated entries where the system supports them, and preserve the earlier approved version. Ask what an import actually changes: future defaults, an employee's current profile, historical earnings allocations or all of these. A bulk upload that appears to fix one employee can change other records if it uses a shared worksite code.
Compare the scheduled payroll cutoff with the remaining work. An internal cutoff does not extend an agency deadline or authorize late wages. If a required decision is unresolved, escalate the specific issue and arrange a lawful, approved payment approach. Continue independent preparation, such as collecting the service record, while the responsible specialist resolves the treatment.

These dates answer different questions. Keep the original work event visible even when payroll receives the report later.
Apply the Work Location Release Test
Copy the six tests below into the employee's restricted change file. For each test, record Pass or Unresolved, the evidence location, reviewer and date. Add the employee reference, employing entity, proposed arrangement, first service date and first affected payday at the top. The test controls release of a particular configuration; it is not a tax-residency questionnaire or a legal safe harbor.
Test 1: Can the work be located?
Identify residence, actual work sites, assigned office and the expected ongoing pattern. Preserve the employee confirmation, manager input and any relevant service dates. If the sources disagree, name the unanswered question and its owner. A usable result explains what happened or is expected to happen, not merely which address field was populated.
Test 2: Is the treatment supported for every layer?
Record the state withholding conclusion, applicable certificates, unemployment coverage decision and local or other program review. Link each conclusion to its current official source or written professional determination. Identify any remaining exception question. A residence certificate supporting one tax must not be used as evidence that every other layer is exempt.
Test 3: Can this employer file and pay?
List required account and authorization statuses for the employing entity. Identify the filer, payment responsibility and evidence that the configuration uses the correct account. An application receipt can be useful evidence of an application; label it accurately if the account or authorization remains pending. Give any deadline conflict a named escalation.
Test 4: Do dates survive the transfer?
Compare the approved service dates and treatment dates with the actual payroll input. Identify earlier affected periods, the scheduled cutoff and any correction task. Check approved location entries in timekeeping when they supply payroll allocation data. Preserve both the prior configuration and the version proposed for release so the reviewer can explain the change.
Test 5: Does the preview produce the approved result?
Inspect an appropriate payroll preview or supported test output for the actual scenario. Compare entity, locations, applicable tax lines, employer charges and reporting destinations with the reviewed instructions. Explain unexpected differences. Record the preview identifier and reviewer; a green system validation badge does not establish that the tax decision itself was correct.
Test 6: Is someone accountable after payday?
Name the person who will compare the actual payment and reporting output with the approved setup. Set the next review event and identify any remaining historical correction. Record the employee communication and where supporting evidence is retained. A future check without an owner or a retrievable output leaves the setup unverified in practice.
Release decision: Record the six outcomes, the exact configuration version approved for use, the approving person and the first covered payroll. Any Unresolved result needs a stated decision before that configuration is released. Escalate payment timing separately; this test does not authorize withholding earned wages while administrative work remains open.
Use a provider demonstration to examine a mid-period move and the earlier settings it preserves. A free SelectSoftware Reviews consultation can help identify options for that review. Confirm state and local coverage, registration ownership and ongoing support directly with each finalist.
A reciprocal border still requires a complete setup
Fictional example: Cedar Instruments hires a Pennsylvania resident who will work at its New Jersey site. The employee tells payroll that the two states have reciprocity and asks it to turn off every New Jersey deduction. Payroll retrieves the employer instructions before changing the configuration.
New Jersey's employer guide permits the Pennsylvania-resident withholding exemption when the employee files Form NJ-165 and requires the employer to retain it. It says New Jersey withholding is required if the employee does not complete the certificate. The reciprocal income-tax agreement covers employee compensation, rather than all possible income or every employer obligation.
Cedar obtains the required certificate, has its reviewer establish the applicable resident-state withholding and records the reviewed effective treatment. The unemployment and other program decisions remain separate. The team also checks whether any local-tax obligation applies to its actual facts; a state reciprocity conclusion is not a universal local-tax exemption.
The release evidence includes the certificate, employer-account confirmation and the approved payroll preview. If a prior check already withheld New Jersey income tax, payroll does not casually refund or reclassify it merely because the employee now supplies a form. It identifies that payment for review under the correction instructions and gives the employee a factual explanation of the next step.
A hybrid schedule is evidence, not an automatic allocation
Fictional example: Northline Design employs a New Jersey resident assigned to its New York office. The planned week includes two days at that office and three at the employee's New Jersey home. Someone proposes entering forty percent as the New York withholding allocation because two of five days are physically there.
The reviewer preserves the schedule but does not approve that percentage on arithmetic alone. New York's current nonresident FAQ says telecommuting days of a nonresident with a New York primary office are treated as New York workdays unless the employer has established a bona fide employer office at the telecommuting location. The underlying facts and applicable rules need review before payroll treats home days as outside-state days.
New York also provides Form IT-2104.1 for nonresidence and allocation of withholding. The form instructs employees to report its specified residence or substantial service-percentage changes within ten days and instructs employers to retain the certificate. The team uses the withholding instructions and the reviewed facts, rather than treating a general residency answer as a complete payroll calculation.
Northline records who reviewed the assigned office, the home-work arrangement and the required certificate. It retains the approved sourcing and withholding treatment and an explanation of any difference from the physical schedule. It makes no promise about the employee's individual return or credits. A later change in the arrangement reopens the location review, even if the mailing address stays the same.
Handle a late report without erasing earlier work
Fictional example: Harbor Analytics learns on October 12 that an employee began working from a different state on October 5. An October 9 payroll already included services from October 5 through October 9. The next payday is October 16. Changing a future default may be necessary, but it will not explain the already issued payment.
Harbor preserves the original October 9 register, location inputs and reporting output. It obtains the actual service record and asks the responsible reviewer to identify affected taxes, accounts and periods. The October 16 setup and the October 9 correction review receive linked tasks with distinct outcomes. The team does not replace October 5 with October 12 merely to avoid a retrospective question.
The reviewer checks what has already been deposited, filed or furnished before deciding the correction path. Some issues require a payroll adjustment, others an employer-return or employee wage-statement correction, and others a supported no-change conclusion. The location report alone does not authorize a specific amended form or a recovery from the employee.
Put the unresolved historical item in the late-change queue with its amount or affected population, missing decision and next action. Tell the employee what the team has confirmed, what information is still needed and when it will respond. Avoid promising a particular refund, tax credit or net payment before the review establishes it.
Inspect the first payment and its reporting trail
Use the release test's approved preview as a comparison point after processing. Inspect the actual employee record, payroll register and relevant tax or reporting output. Confirm that the intended effective-dated setup survived imports and that the payment used the correct employer and account mappings.
A location-only configuration change with no authorized earnings change should not quietly alter the agreed earnings inputs. Treat an unexplained gross-pay difference as a review flag. Conversely, matching gross and net totals will not prove correct state reporting: two different tax allocations can produce similar totals. Compare the underlying jurisdiction lines and their approved basis.
Choose cases that can reveal the likely failure. For a mid-period move, inspect the boundary between the old and new arrangement. For recurring work in two places, inspect how the service record reaches payroll. For a certificate-based treatment, check the employee's actual certificate and the resulting tax lines. Keep those comparison outputs with the approved setup, and use an authorized preview rather than creating a second live payment as a test.
Check the provider's evidence at the service boundary too. If it handles account registration or filing, obtain the confirmation it agreed to supply. An internal reviewer should be able to connect that confirmation to this employer and this period. A general message saying multistate is enabled leaves the essential account and reporting questions unanswered.
At the relevant filing review, reconcile the reported quarter with the approved employee and jurisdiction records. Investigate unexpected wage allocations, missing accounts or unexplained balances before treating a submission receipt as the end of the work. Give an employee wage-statement correction its own evidence when one is required; it does not substitute for an employer account correction.
Keep location decisions current as arrangements change
Set a practical trigger for a new review: a residence or worksite change, a different recurring schedule, a new employing entity, an assignment extension, a changed certificate or new agency instructions relevant to the arrangement. Ask managers and employees to report changes through the same defined channel. Do not rely entirely on an annual address confirmation to discover work performed elsewhere.
Retain the approved facts, the source used for each decision, the employee's certificates, account evidence, configuration history and first-payment review in a restricted evidence archive. Follow the retention and legal-hold requirements. Keep full personal identifiers out of a general operational log when a secure reference will let the authorized reviewer retrieve the evidence.
Use recurring exceptions to improve the intake. Repeated late work-location reports may call for clearer manager instructions; repeated account delays may require an earlier registration handoff. A recurring disagreement between timekeeping and HR may require an explicit source rule and a check on the integration, rather than another manual correction each payday.
When evaluating a replacement provider, take one resolved location change and one genuinely difficult unresolved scenario into the provider's multi-state demonstration. Ask it to show effective dates, certificate handling, multiple jurisdictions, account ownership and retrievable reporting evidence. Compare what the proposed service actually covers with the work your team will retain. Keep a named internal owner for the final treatment and the payroll result.
For a provider shortlist, tell a SelectSoftware Reviews advisor how many employing entities, states and recurring work patterns the proposed service must support. The consultation is free; compare the final package's registration and filing responsibilities before signing.
Explore the Decision Guides library.
See the Payroll Operations & Controls hub.

About the author
Ben Scott writes and maintains payroll decision guides for founders and operators. His work focuses on execution realities and how decisions hold up under growth, complexity, and controls and documentation pressure. He works hands-on in HR and leave-management roles that intersect with payroll-adjacent workflows such as benefits coordination, cutovers, and compliance-driven process controls.


