Payroll Accruals: Estimate the Unpaid Period and Reconcile the Reversal

Updated: 2 days ago

The last paycheck of the month does not necessarily pay for the last work of the month. Start a payroll accrual by identifying the service period still missing from the ledger, then follow that same period into the payroll that eventually records it. Comparing the estimate with the next run's entire total will usually answer the wrong question.
A payroll accrual SOP should produce an approved estimate, a posting instruction, a defined reversal or settlement method, and a comparison with the actual cost for the same employees and earned dates. The useful output is a supported period-end balance and an explanation of what changed afterward.
This guide is for payroll and finance teams preparing an accrual-basis close. Your controller or accounting adviser must approve the reporting framework, recognition policy, account treatment and any correction to a closed period. An accounting estimate does not determine an employee's wages, change a payday or establish when employment taxes must be deposited.
Contents
Mark the unpaid slice of the work calendar
Write down three different dates: the last earned date already represented in posted payroll, the accounting cutoff, and the expected payment date. The unpaid slice is the earned time through the accounting cutoff that the ledger has not already captured. A future payment date helps locate the eventual settlement, but it does not define the slice.
For example, suppose a payroll covers ten scheduled workdays, four before month-end and six afterward. A four-day estimate may be appropriate for an unchanged salary population under the company's approved allocation policy. It is not automatically four-tenths of every item on the register. Overtime, hires, terminations and a commission can follow different evidence.
Identify work already recorded through another entry. An off-cycle run, an earlier manual accrual or a cost imported from a time system can cover part of the same period. Subtract overlap only after identifying its journal and scope. Otherwise a correct-looking new estimate can duplicate a liability that was already recorded.
Define the boundary for each employing entity and relevant currency. Keep the original amount and the approved translation basis when a foreign-currency balance is involved. An employee's transfer between entities or cost centers during the slice needs an effective-date allocation, not a last-day organizational snapshot applied to every earlier day.
Use an explicit status for incomplete evidence. “Estimated hours pending manager confirmation” is useful when accompanied by the population, assumption, owner and follow-up date. “Payroll pending” does not tell finance whether an obligation was estimated, omitted, duplicated or simply awaiting payment.
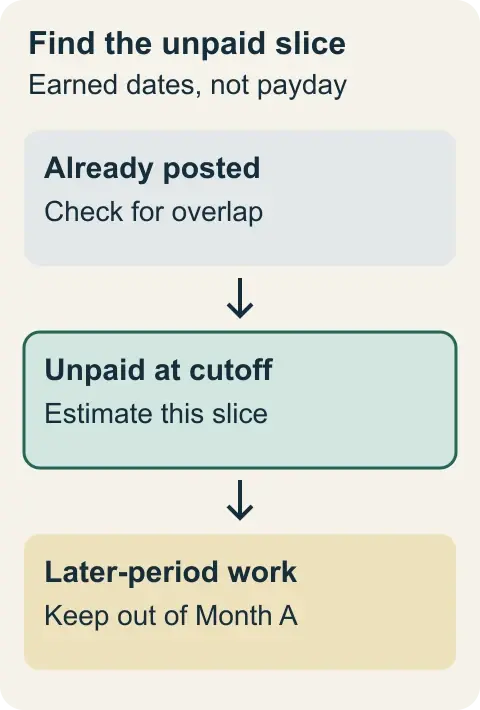
The estimate covers the unpaid earned slice after checking work already posted. Later-period work belongs outside Month A's estimate.
Establish the population before choosing a formula
Begin with the people and earning arrangements that can create unpaid cost. Reconcile the employee list to approved starts, departures, leave and pay changes effective during the slice. Compare expected groups with the source report's filters. A report limited to active employees today can omit someone who earned wages before leaving yesterday.
Save the time report's extraction date, version, earned-date range and approval status. Distinguish approved hours from submitted hours and a modeled amount from either. The Department of Labor's recordkeeping guidance requires accurate hours-worked and wages-earned information for covered nonexempt workers. A close estimate should preserve the distinction between known payroll facts and an assumption about missing facts.
Ask payroll to explain unusual pay calendars, unpaid leave and rate changes before applying a standard daily amount. If the source contains ten employees but only nine rate records, resolve the missing person rather than letting a lookup return zero. Test for duplicate employee-period rows as well as missing rows.
Keep sensitive employee detail in controlled support. The close schedule can show a restricted reference, group total and reviewer without circulating bank information or a complete personnel file. The reviewer still needs authorized access to enough detail to reproduce the calculation.
A reliable prior estimate can be a reasonableness comparison. It is a weak substitute for identifying this month's actual population. A stable headline headcount can hide departures, different pay rates or a shift from ordinary hours to premium work.
Match the method to the kind of cost
Salaries with a defined allocation basis
For stable salary groups, use the compensation and allocation convention approved for financial reporting. Document the denominator and which days are included. Scheduled workdays, calendar days and an annualized daily amount are different conventions; switching between them silently creates a variance before anyone has worked differently.
The allocation used to estimate accounting cost is not a legal salary-deduction rule or permission to change contractual pay. Validate partial periods, unpaid leave and effective-dated increases with payroll. Keep the salary amount and the period it represents together so a reviewer can see why the numerator and denominator belong to the same calculation.
Use a separate line when a rate changes inside the slice. That is easier to inspect than an unexplained blended rate. If a simplified method remains appropriate, record its scope and why it reasonably represents the affected employees.
Hourly wages and premium earnings
Use earned-date time records and approved rates where available. Separate ordinary hours, overtime and other premium components rather than multiplying all hours by a single regular rate. When approvals arrive after close, retain the provisional basis and compare it with the approved time later.
Do not restart a workweek at month-end to make the accounting split easier. Federal overtime rules generally treat each workweek separately rather than averaging hours across weeks. Have payroll determine the wage result under the applicable rules, then allocate the resulting cost to the reporting periods using the approved accounting method.
If the full workweek is incomplete, document how the premium estimate was developed and who will resolve it when the week closes. “No overtime approved yet” does not establish that no overtime cost exists. Equally, a budgeted premium should not be presented as approved employee earnings.
Employer costs associated with the wages
Calculate employer taxes and other employer costs on their appropriate bases. A flat burden percentage can be an approved estimation shortcut for a suitable population, but it is not a universal tax rate. Wage-base limits, exemptions, different jurisdictions and benefit arrangements can make a prior average misleading.
Separate employer cost from amounts withheld from employees. Employee deductions are part of the eventual distribution of gross wages, not an extra employer wage expense to add on top of gross pay. Benefits already accrued through accounts payable or another schedule also need an overlap check.
Publication 15 distinguishes federal employment-tax deposit timing from accounting accruals: its deposit rules follow when wages are paid, rather than when a liability is accrued for accounting. Maintain the tax calendar independently. Booking an employer-tax estimate is neither evidence of a deposit nor an instruction to change a tax return.
Give other obligations their own accounting decision
The ordinary unpaid-wage estimate should not become a container for every payroll-related uncertainty. Route a bonus, commission, paid-absence balance, severance or deferred arrangement to the person responsible for its accounting policy. Identify the applicable plan terms, service period, conditions, existing balance and required support.
KPMG's employee-benefits handbook describes Topic 710 as addressing particular compensation arrangements, with other matters governed elsewhere or through applicable accounting principles. Its discussion of compensated absences illustrates why plan terms and recognition conditions matter. Do not assume an unused leave balance or a proposed award follows the same rule as four days of ordinary salary.
Separate treatment does not mean ignoring a possible obligation. Record the question, the amount or exposure information available, the policy owner and the deadline for a conclusion. Finance must determine whether to recognize, estimate, disclose or otherwise address it under the applicable framework. Missing payroll processing is not itself an accounting conclusion.
Commission support should identify the underlying plan and earned-period evidence. A sales forecast and an approved commission calculation are different inputs. If recognition depends on a technical assessment, retain that assessment with the accounting schedule rather than burying the uncertainty in the base-pay percentage.
Likewise, an unresolved employee underpayment belongs in the wage-correction process as well as any necessary accounting review. An accrual can represent an obligation in the books; it does not make the employee whole. Federal overtime payment rules have their own timing requirements, and applicable state rules also need review.
Calculate one estimate that another person can reproduce
The following case is fictional and uses Month A and Month B rather than a particular calendar. Assume the controller has approved a workday allocation for the salary group, the hourly evidence is complete for the estimate, and all costs are expensed. There are no opening overlaps, currency differences or separately accrued benefits.
The unpaid slice contains four of a salary group's ten equal scheduled workdays. Its complete ten-day salary is $5,000. Estimated salary cost is $5,000 ÷ 10 × 4 = $2,000. Separately, 180 hourly hours at $30 produce $5,400. The wage estimate is therefore $7,400.
For illustration only, assume an approved composite employer-cost estimate of 8% applies to this entire fictional wage base. That produces $592, making the total accrual $7,992. The 8% is invented for the example, not a statutory rate or a recommended allowance for real employer taxes.
Keep the component calculation visible:
Salary: $2,000, supported by the salary roster and four-day allocation.
Hourly wages: $5,400, supported by 180 hours and the $30 rate.
Employer cost: $592, supported by the fictional 8% assumption.
Total accrual: $7,992, with each component assigned to the correct entity and accounts.
The proposed Month A entry debits wage expense $7,400 and employer-cost expense $592. It credits accrued wages $7,400 and accrued employer cost $592. Debits and credits both total $7,992. Use your approved chart of accounts; an asset-cost allocation, separate departments or different liability accounts can require different lines.
Have a reviewer reproduce at least the slice, population and component totals from the retained reports. A balanced journal proves only that the debit and credit totals agree. It does not prove the employees, period or cost classification are correct.
Choose one way to unwind the estimate
A reversing accrual and a liability-settlement approach can both appear in accounting processes. They need different posting instructions. Select the approved method before booking, then ensure the actual payroll journal follows that method. Mixing parts of both can remove the same liability twice or leave wages in expense twice.
With the reversing method in this example, the Month B entry debits accrued wages $7,400 and accrued employer cost $592, and credits their expense accounts for the same amounts. The actual payroll then posts through the normal approved accounts. Keep the original accrual ID, reversal ID and actual run reference connected.
An automatic first-day reversal can be appropriate under the company's close design, but its existence is not proof the underlying work has been paid or recorded. If the actual run is delayed past the next reporting cutoff, finance must assess the still-unsettled obligation and the closing estimate. Do not leave the balance absent merely because a reversal posted.
Under a settlement method, actual payroll uses the accrued liability for the previously accrued portion and records any difference and new-period expense through the approved accounts. Do not add a full automatic expense reversal to that design. Finance should document how the interface splits the actual entry and prevents duplicate clearance.
Keep long-lived or separately measured liabilities outside a routine automatic-reversal batch unless their approved treatment calls for it. A paid-absence obligation may remain outstanding after the first payroll of the new month. The next convenient run is not evidence that every liability on the schedule settled.
Test both system status and posting date. A reversal created in a queue may not yet be in the ledger; a reversal posted to the wrong entity may leave the consolidated total looking reasonable while both entity balances are wrong.
Compare actual cost for the same earned dates
Assume the next fictional payroll's total gross wages are $18,000 and its employer cost is $1,440. Its earned-date detail identifies $7,500 of wages and $600 of employer cost for Month A. The remaining Month B cost is $10,500 of wages plus $840 of employer cost, or $11,340.
For clarity, the example's employer costs also happen to equal 8% of wages. These are illustrative supplied amounts, not a model of actual tax calculation. Compare real employer costs using the applicable payroll results and your approved allocation basis.
The like-for-like comparison is Month A actual $8,100 against Month A estimated $7,992. The $108 increase consists of $100 in wages and $8 in employer cost. Comparing the full $19,440 payroll cost against $7,992 would mix six days of new-period work into the variance.
With the unadjusted $7,992 reversal, Month B's net expense from these entries is $19,440 minus $7,992 = $11,448. That contains $11,340 for Month B and the $108 difference relating to Month A. Across both months, $7,992 plus $11,448 equals the actual $19,440.
This bridge explains the arithmetic; it does not decide which reporting period may retain the difference. If Month A remains open and finance determines an adjustment is appropriate, increasing its accrual by $108 and reversing the revised $8,100 leaves $11,340 in Month B. The reversal must follow the approved revised amount rather than the superseded estimate.
If Month A is closed, send the facts to the controller for the appropriate estimate-change or error assessment and correction decision. Do not automatically backdate the payroll, alter a filed wage record or book everything to current expense because the difference seems small. Preserve the original and revised evidence.
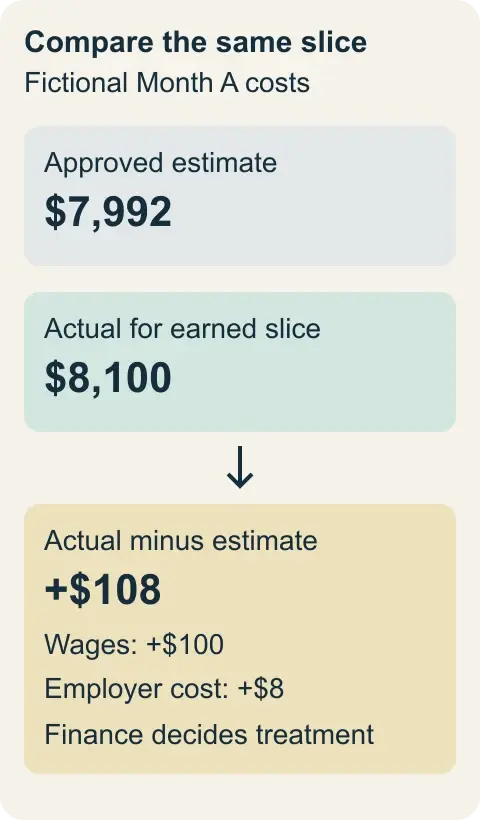
The $108 difference relates to the same Month A scope. It combines $100 of wages and $8 of employer cost, with accounting treatment approved separately.
Resolve the cause before clearing the line
Assign each difference to something that can be checked: hours, rate, population, earning code, employer-cost basis, period allocation, account mapping or posting timing. Use employee-level support where needed while keeping the shared close explanation appropriately restricted.
A $100 increase might arise from a premium omitted from the estimate. It might instead come from one employee counted twice in actual detail. Those situations require different corrections. A description such as “timing” is incomplete until it identifies the missing or delayed event and the date expected to clear it.
Review offsetting differences separately. An overestimate of $500 in one department and an underestimate of $500 in another net to zero, but the cost allocation is still wrong. Compare meaningful components and entities before accepting the total. Also investigate a reversal that agrees in amount but posts to the wrong expense account.
Use the organization's approved review and materiality policy to decide escalation and correction. For SEC registrants, Staff Accounting Bulletin No. 99 cautions against deciding materiality solely from a numerical threshold. Do not turn a convenient percentage into permission to leave employee pay, tax obligations or known accounting errors unresolved.
A line closes when its recognition and posting have been reconciled, any required correction is approved and recorded, and the remaining balance is explained. If it remains open, give it a named owner, aging date and next action. Carry that evidence forward without silently refreshing the line's age each month.
Set the timetable around available evidence
Schedule the initial extract, payroll confirmation, finance review, journal posting, reversal confirmation and actual comparison as separate events. Put them on the close calendar with responsible people. The actual-comparison date should follow the relevant finalized run, not an arbitrary date when the reviewer knows the evidence will be unavailable.
Define what changes between the initial estimate and posting require another review. A replacement time extract, a new salary file or an entity correction can invalidate an earlier approval. Preserve the superseded version and explain the delta; do not overwrite the workbook while leaving the original approval attached.
If a source will arrive late, give finance a specific decision package: affected group, last reliable evidence, proposed assumption, sensitivity, expected actual date and person responsible. Finance can then decide whether an estimate is supportable and what follow-up is required. A missed internal cutoff does not remove an obligation from consideration.
Keep the approver of the accounting judgment distinct from the preparer where the team can do so. In a small team, an external accountant or designated owner can provide the agreed review. Document the review actually performed rather than adding an unused second signature box.
Retain the schedule alongside its source versions, posting evidence and resolution. IRS employment-tax recordkeeping guidance requires tax records for at least four years after filing the fourth quarter for the year and identifies payment, deposit and return evidence. Apply the retention rules relevant to each record and any longer legal, audit or company requirement; a routine close-folder cleanup should not destroy the support.
Use the Accrual Line and Settlement Schedule
Create a record for each component, entity and earned-period slice that needs distinct support or clearance. Reuse the record until the line is resolved. The fields below can be copied into a controlled document or spreadsheet; they do not require employee bank or identity details.
Define the line
1. Line identity: Record the close month, entity, currency, component and responsible preparer. Use one ID that remains with the estimate, reversal and actual comparison.
2. Earned dates and population: Record the start and end of the slice, included employees or restricted roster reference, and the last earned date already posted.
3. Overlap check: Identify earlier accruals, payroll journals or other schedules covering the same work. Record the amount already recognized and how duplication was prevented.
4. Recognition decision: Identify the approved accounting policy, reviewer and conclusion. For an unresolved component, identify the separate accounting review rather than substituting zero without explanation.
5. Source version: List the report or controlled file, extraction time, filters, approval status and secure location. Mark actual, approved or estimated inputs clearly.
An unresolved recognition question remains visible even if the ordinary wage line can be prepared. Record its owner and decision date separately.
Calculate and post
6. Quantity and rate: Enter hours, days or other units, rates, effective dates and the complete denominator. Keep the calculation reproducible.
7. Employer-cost basis: Record each relevant base, rate or approved estimation assumption, including wage-base limits, exclusions and overlap with other schedules.
8. Proposed amount: Record the wage or component amount, associated employer cost and total, with the entity, account and cost-center allocation.
9. Review result: Record the reviewer, date, reproduced checks, exceptions and approved version. Identify any change requiring renewed approval.
10. Posting proof: Record the journal ID, accounting date, posted amount and evidence that the ledger accepted it. Distinguish an upload file from an actual posting.
11. Unwind instruction: Choose the approved reversal or settlement method. Record the expected date, accounts, related run and confirmation owner.
Before releasing the journal, confirm that its amount and version match the review. A later correction must update the unwind instruction as well as the estimate.
Reconcile and finish
12. Actual-period extraction: Identify the finalized payroll version, earned dates, population and allocation used to isolate actual cost for this line.
13. Difference bridge: Record actual cost minus estimate, separated into wages or component cost and employer cost. Explain changes in hours, rates, population or method.
14. Accounting action: Record whether the estimate remains appropriate, a correction is required or further assessment is pending. Include the controller's decision, resulting journal IDs and any affected reporting periods.
15. Closing balance and next action: Record the supported remaining liability, unresolved items, owner and due date. Close the line only when its posting and resolution are evidenced.
For the fictional case, field 8 is $7,992 and field 12 is $8,100 for the same Month A scope. Field 13 explains $100 of wage difference and $8 of employer cost. Field 14 records the accounting decision about that $108; the worksheet does not make that decision automatically.
Automate the repeated calculation after proving the route
Automation helps when the population, earned-date logic, accounts and unwind method are already defined. Ask a payroll or accounting system to reproduce the accepted schedule for a period with a rate change, a departure, late time and an off-cycle adjustment. Verify the output rather than accepting a demonstration of a flat salary month.
Inspect whether the system's “accrual” report estimates earnings, accrues unused leave or creates a journal. Those are different functions. Confirm the module and export actually included in the proposed service, the fields available for earned-date comparison and the responsibility for an interface correction.
A system change can also leave both the old spreadsheet reversal and the new automated journal active. Inventory scheduled entries, disable the superseded instruction through the approved change process, and retain evidence of the transition. Do not delete historical entries or records simply to make the new schedule look clean.
Start with a parallel comparison of calculations, not duplicate live postings. Record which method is authoritative for each close and who approves retirement of the old calculation. If the new method cannot isolate the actual earned slice, automation has not yet removed the reconciliation work.
Questions that arise at the first close
Is accrued payroll the same as the next payroll amount?
No. The estimate covers the unpaid cost assigned to the closing period under the approved policy. The next payroll can also contain later-period work, unrelated awards and corrections. Use earned-date detail to compare the corresponding part.
Must the estimate reverse on the first day of the next month?
That depends on the accounting process your controller approves. A first-day automatic reversal needs follow-up to the actual posting and a review of any obligation still outstanding at the next cutoff. A settlement method requires its own account logic instead. Do not combine the two unintentionally.
Can a small difference just stay in next month's expense?
The arithmetic may place it there after a reversal, but that does not settle the accounting decision. Apply the approved estimate-change, error and materiality assessment. Employee payment and tax duties remain separate from that financial-reporting judgment.
What if the actual payroll is not available before close?
Identify the missing evidence, develop a supported estimate where appropriate, obtain the required review and assign the actual comparison. Escalate a component that cannot be supported. Neither an unsupported plug nor an undocumented omission is a substitute for the accounting decision.
Put the next unresolved line through the complete schedule
Choose one unpaid wage slice from the coming close. Agree its dates and population with payroll, reproduce the estimate with finance, confirm how it will unwind, and name the person who will isolate the actual earned cost. Keep the record open through that comparison.
The method is ready for routine use when another authorized reviewer can follow the same work from source evidence to the remaining liability and explain any difference without reconstructing the month from memory.
Browse the Decision Guides library.
Continue with Payroll Operations & Controls.
Explore the Payroll Operations Resource Library for full guides with practical tools.

About the author
Ben Scott writes and maintains payroll decision guides for founders and operators. His work focuses on execution realities and how decisions hold up under growth, complexity, and controls and documentation pressure. He works hands-on in HR and leave-management roles that intersect with payroll-adjacent workflows such as benefits coordination, cutovers, and compliance-driven process controls.