
Employee Reimbursements: Payroll, AP and Claim Settlement

Updated: 2 days ago

An approved expense is not necessarily an unpaid expense. Before sending an employee another dollar, match the claim to any advance, company-card charge or earlier reimbursement and identify the remaining balance.
Employee reimbursements can move through payroll or accounts payable. A settled claim needs a supported expense amount, the applicable tax treatment and evidence that earlier funding plus any new payment or return clears its balance.
This workflow covers U.S. employee business expenses, from evidence through payment and any excess return. Use the Employee Reimbursement Settlement Record below to document each claim. The examples are fictional operating situations, not tax determinations for a particular employer or results from testing a payroll product.
Contents
Answer three questions before paying a claim
Start with three questions. What accepted expense must the employer repay? What treatment applies to the payment? What amount remains to be settled? A manager's approval can support the first answer without completing the other two.
Expense obligation: identify the employer, employee, business purpose, applicable policy and legal requirements. Determine the accepted amount and when it must be paid. A payroll cutoff is an operating constraint to resolve, rather than an automatic reason to postpone an obligation.
Tax treatment: have the responsible reviewer establish the basis for excluding an expense repayment from wages or including an amount in payroll reporting. An expense label, employee vendor profile or manager signature does not supply that basis.
Payment balance: determine what has already reached the employee or supplier. An approved claim for $470 may require a $470 payment, no additional payment or a return of excess, depending on earlier funding.

Keep these decisions connected to the same claim. A completed approval is evidence of an accepted decision, not proof of a bank payment.
Payroll is a practical route when its reimbursement code produces the intended nonwage payment and the timing works. AP may be a practical route when expense review and payment already occur there. In either case, assign one cash-release owner and identify any record the other system still needs.
Use a consistent claim identifier across the expense report, payment instruction, advance record and payroll adjustment. Where a system cannot carry it, retain a controlled cross-reference. Matching only employee names and equal dollar amounts becomes unreliable when the same person has several similar claims.
Assemble evidence that explains the expense
An expense record should let a reviewer understand what was bought, when, for whose business and why the employee paid. The evidence needs to support the particular expense and its applicable rules. A credit-card statement may show a charge without explaining the business purpose or the items purchased.
Capture the expense date, supplier, amount, currency, business purpose and supporting document reference. Distinguish the employee's out-of-pocket portion from employer-paid amounts and personal items. For a trip, identify its business dates and purpose; for a purchase serving multiple activities, explain the allocation rather than approving the whole receipt automatically.
Check for company-card payment before reimbursing a receipt. The same hotel invoice can appear in a travel report and an employee claim even when the employer already paid it. A report can document the expense without authorizing another cash payment.
Look for an earlier claim or advance using more than the total. Compare supplier, date, employee, business event and payment references. Ask about an apparent duplicate before deleting it: one entry could be a corrected report replacing a rejected claim. Preserve the relationship between versions so the replacement does not remain payable alongside the original.
For travel and car expenses, IRS recordkeeping guidance addresses the elements to substantiate and when documentary evidence is required. Some receipt exceptions exist, including certain expenses below $75, but lodging has different requirements. An exception from producing a receipt does not eliminate the need to establish the expense and business purpose.
A missing document needs a specific next action. Request the itemized bill, purpose explanation or allocation that is absent. Identify who can obtain it and the date the issue must be resolved. If the document cannot be obtained, send the available evidence and applicable alternative-documentation rules to the authorized reviewer.
Do not promise that a signed missing-receipt statement satisfies every tax rule. It may document a policy review while leaving a separate federal substantiation question. Record the decision and its basis rather than treating the form's existence as a universal approval.
Keep bank information and sensitive receipts in the approved restricted location. The settlement record can point to that evidence without reproducing account numbers, medical details or personal purchases in a broadly shared tracker.
Apply the reimbursement arrangement that actually exists
Under an accountable plan, the arrangement must have a business connection, require adequate accounting within a reasonable period and require return of excess within a reasonable period. Qualifying payments are excluded from wages for the federal employment-tax purposes described by the IRS.
A policy's title is insufficient if its operating terms do not meet those conditions. Nor can an employer turn wages otherwise payable into an expense repayment by changing a pay-code label. Review what the employee is entitled to receive and what the arrangement requires in practice.
Separate a supported reimbursement from an unrestricted allowance. A regular amount paid regardless of expenses needs its own tax analysis. Do not assume it is excluded from wages because it appears in the reimbursement column.
Per diem and mileage arrangements need more care than the rule “flat amount means taxable.” Qualifying methods can substantiate the amount using prescribed rules while still requiring the employee to establish relevant travel or mileage facts. Verify the applicable method, current rate, dates and limits before configuring it; this guide supplies no standing mileage or per diem rate.
Document mixed treatment by component. An expense report can contain an accepted business item, a personal item and an unresolved item. Record the dollars and decision for each, so a single “approved” status cannot authorize the personal amount or conceal the unresolved balance.
The federal overtime regular-rate question is also separate from payroll tax treatment. The regulation addresses actual or reasonably approximate employer-business expense reimbursements and disproportionately large amounts. Have the appropriate reviewer determine the applicable wage-and-hour treatment instead of assuming that a payroll tax setting settles it.
For recurring remote-work, vehicle, phone or other allowances, establish the arrangement before automating the payment. Define the covered expense, evidence, allocation, excess handling and review owner. Reconsider the arrangement when the employee's circumstances or payment terms change.
Put payment deadlines and substantiation dates on separate calendars
The accountable-plan timing rules do not create a general employer reimbursement payday. Applicable employment law, policy and the facts of the obligation need their own review. A longer federal substantiation period is not permission to ignore an earlier payment obligation.
The IRS describes reasonable-period approaches, including an advance within 30 days of when the expense is paid or incurred, substantiation within 60 days and return of excess within 120 days. It also describes a periodic-statement alternative, at least quarterly, with action within 120 days of the statement. These are reasonable-period rules with conditions, not a universal “pay every expense in 30 days” instruction.
Use actual dates in the claim record: expense incurred, advance paid, evidence due, excess return due and payment due. Record which timing method applies. An internal earlier submission deadline can help operations, but it should not be confused with the federal rule or treated as resolving every late claim.
State law may create additional requirements. Illinois' 2026 labor poster, for example, identifies necessary employee expenses as an employer reimbursement obligation and states a 30-calendar-day employee submission rule unless employer policy allows longer. That submission period is distinct from the federal accountable-plan rules. Check the law applicable to the employee rather than borrowing one state's rules for the whole workforce.
Federal wage protections matter too. Employer-benefit costs cannot be shifted to an employee in a way that unlawfully reduces required minimum wages or overtime; an employer cannot avoid the rule simply by asking for a cash repayment. Review the actual workweek and applicable law when expenses or proposed recovery affect pay.
When evidence is incomplete near a payment deadline, give the reviewer both questions: what obligation must be met now, and what tax or documentation work remains? Arrange an approved timely response, which may require a separate payment route or advice on the disputed portion. Do not leave a lawful obligation suspended indefinitely in an expense queue.
Communicate the next step to the employee without giving a misleading status. “Accepted for $470, payment scheduled for Friday” describes something different from “paid.” If an item remains disputed, identify the specific issue and the person handling it rather than sending a generic request to resubmit the whole report.
Use an advance to fund an expense, then clear its balance
An accountable arrangement can provide an advance for reasonably anticipated business expenses. Paying before receipts is therefore not inherently a failed control. The important work is to connect the advance to the expected expense, obtain the required substantiation and handle any excess under the arrangement.
Record an advance when it is released, with its amount, purpose, employee and due dates. Do not leave it only in an email approval or assume it will be discovered when a later expense report arrives. Tell the employee how to submit evidence and return unused money.
Consider a fictional $500 travel advance. The employee later substantiates $470 of accepted business expenses and returns $30 on time under an otherwise qualifying accountable arrangement. No further reimbursement is due for those expenses. The advance can close when the reviewer has the expense evidence and confirmation of the $30 return.
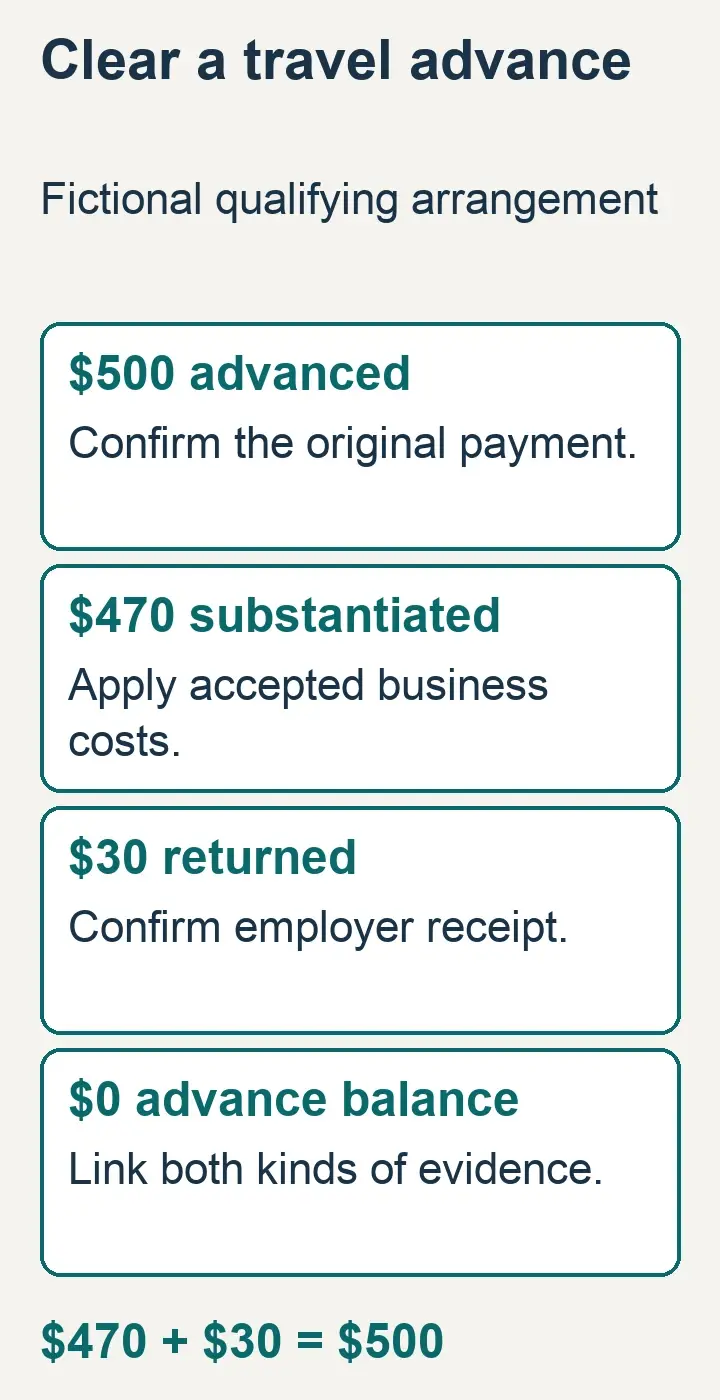
The $470 expense and $30 return clear different parts of the $500 advance. Expense approval alone leaves $30 unresolved.
If accepted expenses were $560 instead, the same $500 advance would leave $60 payable to the employee, assuming no other payments or offsets. The expense report should authorize the additional $60, not send the full $560 through a second payment run.
If only $450 were supported and no excess had been returned, $50 would remain unresolved against the advance. Preserve that balance and its due date. Do not describe it as recovered merely because finance requested a return.
For amounts advanced under an otherwise accountable plan, unsupported or unreturned excess is treated as nonaccountable wages for the first payroll period after the reasonable period ends. Send payroll the reviewed amount, basis and deadline before that period is processed. Special rules can affect allowance arrangements; have the reviewer establish the actual rule and date rather than applying one generic aging trigger to everything.
A later receipt or return should trigger a review of the affected records, not an automatic reversal of previously reported wages. Identify what was reported, why and for which period before deciding whether a payroll or information-return correction is appropriate.
Calculate the cash still due before selecting the run
For an ordinary claim with no advance, begin with accepted employee-funded expenses. Subtract verified earlier reimbursements of those same expenses. Keep employer-paid charges outside the amount payable to the employee. State any currency conversion method and supporting rate record when currencies differ.
Do not subtract an advance twice. Either apply its available balance to the accepted expenses and calculate the remaining reimbursement, or show the full advance reconciliation separately with a clear cross-reference. A payment instruction should contain one unambiguous amount.
A fictional employee submits $320 of accepted out-of-pocket expenses. AP already paid $200 against that claim. Payroll receives a request containing the full approved $320 report. The remaining cash obligation is $120, assuming the earlier $200 settled successfully and no other adjustments apply.
Before releasing the $120, confirm that the AP payment has not been rejected or voided. If its status is uncertain, investigate it. Paying the apparent remainder without resolving the first payment can either leave the employee short or create a duplicate when a replacement is later issued.
Document corrections to an accepted amount as a new version. Show the old amount, changed item, reason, approval and resulting balance. A reviewer should be able to reproduce the new instruction without guessing whether the earlier approved total remains valid.
For tax reporting, identify whether an instruction represents cash still payable or an amount already paid. If AP paid an amount that the reviewer determines is taxable wages, payroll needs an approved way to record and handle it without paying that amount a second time. Any withholding shortfall, recovery or additional employer-funded amount requires a separate authorized decision.
Do not mark an AP-paid amount “noncash” solely to suppress a duplicate payment without understanding the payroll configuration. Ask the provider or system owner to demonstrate the supported method, its wage bases, withholding, net cash and reporting output. Use the actual preview before release.
Choose payroll or AP for the work each can complete
Use payroll when the approved code and output handle the treatment correctly, the payment date meets the obligation and the claim evidence remains traceable. Review how the reimbursement appears on the employee's statement and whether it affects wages, deductions or employer taxes as intended.
Use AP when expense review, funding and settlement are managed there and the employee can be paid on time. Define who sends any required payroll information and who confirms it was accepted. An AP payment reference does not demonstrate that a payroll reporting instruction was processed.
Use a coordinated exception when the normal route cannot meet the obligation or handle the required treatment. Name the decision maker, payment owner and reporting owner, with dates for each action. Avoid a vague handoff that leaves both teams expecting the other to pay.
When wages and reimbursement share one payment, identify the expense amount separately in the records and employee-facing explanation as required. A combined bank deposit should not prevent finance from tracing the reimbursement component or the employee from understanding it.
Confirm the accounting treatment in the organization's books. Clearing an advance, recognizing an accepted expense and issuing an additional employee payment are different events. Have the accounting owner determine the entries and reconcile the affected expense, advance and cash records; this guide does not prescribe a universal journal.
A small team can use a short claim register and restricted evidence folder. The reviewer needs source evidence and the actual release output, especially when one person prepares both AP and payroll instructions. Assign a compensating owner review where practical instead of relying on two signatures supplied by the same person.
Follow rejected payments, returns and deductions to their actual result
A released payment can still fail. Keep the claim open when an AP or payroll payment is rejected, returned or awaiting confirmation. Identify the amount still owed and the action needed, while preserving the failed payment's reference.
A reissue should link to the original instruction and the confirmed failure or cancellation. Check that a pending payment cannot settle alongside its replacement. Do not treat a payroll void as evidence that money has returned from the employee's bank.
Verify employee bank changes through the approved independent process before a replacement is released. A request to redirect reimbursement money can carry the same fraud risk as a request to redirect ordinary pay.
For excess advances, identify a permitted repayment method and retain confirmation that the return reached the employer. Do not automatically deduct the amount from wages or final pay. Recovery rights, consent requirements and wage restrictions require review for the applicable circumstances and jurisdiction.
Distinguish a disputed expense from a confirmed overpayment. The company may owe reimbursement while still needing tax evidence, or it may need to recover money already advanced. Calling both situations “employee owes documentation” can hide which party owes cash.
When the employee leaves, hand open claims and advances to named owners with their original dates. Review payment obligations and any proposed recovery under the applicable rules. Ending employment does not itself show that an advance has been cleared or authorize a deduction.
Copy an Employee Reimbursement Settlement Record
Use one record per claim or related advance. Enter dates, dollars and secure evidence references; split components where treatment differs. Copy each field as its own row, then attach the decisions and actual payment results. The record supports review but does not establish a legal entitlement or tax exclusion by itself.
Claim and supporting evidence
Claim identity: Employee / employer / claim ID / expense period / relevant work location: ______
Expense support: Expense dates / supplier / business purpose / amount and currency / secure document references: ______
Amount split: Business expenses in claim / employer-paid charges / personal or disputed items: ______
Earlier funding: Advance and prior reimbursement IDs / amounts / verified status / available balance: ______
Evidence follow-up: Missing fact or document / responsible person / action date / accepted alternative and reviewer: ______
Record what is missing precisely. Keep sensitive receipts and bank details in the restricted evidence location.
Entitlement, treatment and release
Amount owed and timing: Accepted expense amount / policy and applicable-law review / payment due date / approver: ______
Treatment decision: Accountable-plan or wage basis by component / regular-rate review if relevant / authorized reviewer: ______
Substantiation dates: Applicable timing method / expense date / advance date / evidence due / excess return due: ______
Settlement calculation: Accepted claim expenses less applied advance and confirmed earlier reimbursement / additional cash due or excess still to clear: ______
Release instruction: AP or payroll / cash owner / amount and currency / release date / instruction version / payroll reporting owner if needed: ______
An already-paid amount requiring payroll reporting is not another cash instruction. Confirm the intended output.
Actual settlement and reporting
Payment evidence: Release reference / bank or provider result / rejected, pending or settled / verified date: ______
Replacement control: Original payment reference / confirmed failure or cancellation / replacement reference and result, if any: ______
Excess return: Amount required / due date / permitted return method / received reference / remaining advance balance: ______
Payroll completion: Reporting instruction and period / accepted payroll result / wage, withholding and cash checks / remaining correction: ______
Leave this section open until the affected payment and reporting records support the recorded result.
Closure and retention
Unresolved work: Exact amount or question / owner / next action and due date / employee communication: ______
Evidence retention: Restricted record location / retention rule by record type / access owner: ______
Closure decision: Amount still payable / advance still open / reporting still open / reviewer and date / condition for reopening: ______
Close only when the accepted obligation and applicable reporting are resolved and the remaining advance balance is explained.
Worked record: a cleared travel advance
Identity and scope: Fictional claim TR-18; one employee and employer; business travel; $500 advance.
Expense decision: $470 accepted and substantiated business expense; no company-card amount or earlier reimbursement.
Treatment and timing: Reviewer accepts the accountable-plan treatment; evidence and excess return meet the selected reasonable-period method.
Cash instruction: $470 expense less $500 already advanced; no additional employee payment; $30 excess return required.
Settlement evidence: Original $500 payment confirmed; $30 employer receipt confirmed and linked to the claim.
Remaining balances: $0 additional reimbursement due; $0 advance left after applying $470 expense and $30 return.
Closure: Reviewer links expense and return evidence, records the decision and retains the claim in the restricted folder.
Check the setup with an ordinary claim and an exception
Before adopting a new workflow, trace one supported expense with no advance and one advance or AP-paid taxable exception through the actual systems. Use fictional or appropriately protected data and an approved test environment. This is a recommended implementation check, not a claim that a particular product has been tested.
For the ordinary claim, compare the accepted expense, cash instruction, employee statement, payment result and accounting record. The same claim amount should remain traceable even when payroll and expense systems use different identifiers. Investigate an unexpected tax or deduction effect before relying on the configuration.
For the advance case, demonstrate both outcomes: accepted expenses exceed the advance, and the advance exceeds accepted expenses. Confirm that the system pays only the additional amount or records the excess return, without creating a second full reimbursement.
For an AP-paid amount requiring wage treatment, inspect how the approved reporting instruction affects wage bases, withholding and additional cash. Establish how the employer will handle any shortfall before a real employee is affected. Record unresolved configuration questions and the person authorized to answer them.
Set a regular review of open advances, payment failures and uncompleted payroll instructions. Prioritize them by the actual obligation, reasonable-period deadline and employee impact, not just the largest amount. A small unresolved advance can still need timely tax handling.
Preserve the released claim version and subsequent corrections. Give retained records a rule based on what they are and the applicable requirements; expense support, employment-tax records and bank evidence need not share a single destruction date. Restrict access without making the approved evidence impossible for the responsible reviewer to retrieve.
Explore related payroll resources:

About the author
Ben Scott writes and maintains payroll decision guides for founders and operators. His work focuses on execution realities and how decisions hold up under growth, complexity, and controls and documentation pressure. He works hands-on in HR and leave-management roles that intersect with payroll-adjacent workflows such as benefits coordination, cutovers, and compliance-driven process controls.


