
Final Pay Controls: Meet the Wage Deadline at Separation

Updated: 1 day ago
A termination meeting is scheduled for 10 a.m., but payroll's next standard payment date is Friday. Before the meeting, someone needs to establish when this employee's wages are due and how the employee will receive them. Entering an end date in the HR system does not answer either question.
Final pay controls connect the actual separation event to the amounts owed, their payment deadlines and a workable delivery route. An unresolved commission, disputed equipment charge or missing manager signature needs its own response. It should not disappear inside one status that leaves every wage component waiting.
Use this guide for U.S. employee separations, including planned discharges and unexpected resignations. The Final Pay Dispatch Record below helps HR, payroll and payment teams organize the work. State examples illustrate different questions; they are not a fifty-state deadline table. Have the responsible wage-law reviewer identify the rules, coverage and any special industry or agreement provisions for the actual employee.
Contents
The event that starts the wage deadline
Capture what happened before choosing a payroll date. Identify the legal employer, the employee's relevant work locations, who initiated the separation, the notice received, the effective end of employment and the final work actually performed. Keep the notice and the employer's response. A resignation date entered weeks earlier may no longer describe the event that occurred.
The Department of Labor's final-paycheck guidance says federal law does not generally require an immediate final paycheck and points to potentially earlier state requirements. That is a starting distinction, not authorization to wait for the company's usual run. Record the applicable state instruction and the facts that make it apply.
Pay particular attention when the employer changes a proposed resignation date. California's payday FAQ describes an employee who gives notice but is then discharged earlier: earned wages become due immediately at discharge. Do not preserve a voluntary-separation payment date simply because that was the first code HR selected. Obtain a fresh timing decision when the underlying event changes.
For remote or traveling employees, list the work-location history and any other facts the reviewer needs rather than choosing the headquarters state by default. A mailing address and a payroll tax setup are useful evidence, but neither is a complete legal analysis. Record the reviewer's conclusion and source, including any unresolved jurisdiction question and the action being taken to meet the obligation.
A planned employer-initiated exit gives the team time to assemble pay before the meeting. An unexpected departure requires immediate intake and escalation. The distinction changes preparation time, not the employer's ability to invent a later due date. Keep an after-hours contact and an authorized backup for cases that arrive when the normal approver is unavailable.
Four state examples, four different checks
These examples describe ordinary employee situations under the cited sources. Confirm coverage, exceptions and current requirements before using them. Translate the applicable rule into an actual date and, where relevant, a time and time zone. Do not copy a generic state abbreviation into a deadline field and call the review complete.
California: The Labor Commissioner's Final Pay explanation describes wages due immediately on discharge. For a quitting employee without a written agreement for a definite employment period, at least 72 hours' notice generally means payment at quitting; otherwise payment is due within 72 hours. The notice and the actual separation event therefore matter to the clock.
Texas: The Workforce Commission's final-pay explanation distinguishes involuntary separation, with payment within six calendar days, from voluntary separation, with payment on the next regularly scheduled payday. Its separate final-pay and severance guidance addresses the next regular workday when the sixth day falls on a day the employer is normally closed. Apply the actual rule rather than silently converting calendar days into business days.
Massachusetts: General Laws chapter 149, section 148 provides for payment on the discharge day, while a departing employee is generally paid on the following regular payday, or the following Saturday if there is none. The statute also contains specific coverage and payment provisions. Have the reviewer resolve those rather than treating a summary as complete for every employer.
Washington: L&I's Getting Paid guidance says a quitting or fired employee's final paycheck is due on or before the next regularly scheduled payday. It also says an employer cannot withhold that paycheck because keys, uniforms, tools or equipment have not been returned. An equipment task and a wage-payment obligation can remain open at the same time.
The operational result is a reviewed deadline for this separation, not a company-wide rule that final pay always means same-day or always means next payday. Check how weekends, holidays, employee requests and permitted delivery methods affect the particular obligation. Do not move a deadline because a payroll service's standard processing window is inconvenient.
Keep the rule record compact: source URL, date checked, triggering facts, required payment result, due timestamp and reviewer. Where the source describes an exception, record why it applies. A link to a long handbook without the relevant provision leaves the payment team guessing about which instruction it is supposed to execute.
Build the amount from earned components
Start with the compensation that remains unpaid through the relevant earning cutoff. Reconcile the last completed payroll with the time and earning records after it. A separation mid-period can create a short final interval; a payment already scheduled for release can also overlap that interval. Identify what has actually been paid, what is still in flight and what remains due.
For hourly work, confirm the final time record, rates and applicable premiums. Include work performed outside the manager's planned schedule when the reviewed wage instruction requires payment. Do not erase a shift because the employee's HR status changed before the time system received the hours. Assign a factual reconstruction promptly when a record is missing, with the employee's report and available operational evidence.
Salary treatment also needs an actual instruction. The federal salary-basis rule at section 541.602(b)(6) permits proportionate salary for time actually worked in an exempt employee's terminal employment week. That does not establish state entitlements, contract promises or a universal divisor. Record the employee's classification, covered dates and approved method before reducing a salary.
Review vacation and other leave balances as separate components. California's vacation FAQ explains that earned vacation vests and, subject to the stated collective-bargaining qualification, earned unused vacation is paid at the final rate when employment ends. Confirm the balance through the separation date, including earned amounts not yet posted and leave already taken. A balance from the last monthly report may omit both.
Do not treat every leave label as vacation. Identify the actual plan, applicable state rule and any contractual obligation. California's Final Pay explanation distinguishes accrued sick leave from earned vacation. Another employer's policy or a software category called PTO does not settle this employee's payout. Keep the decision and calculation together so a reviewer can explain why a particular balance was or was not included.
For commissions and bonuses, establish the earning conditions and whether they have actually been satisfied. The California payday FAQ distinguishes earned commissions due at separation from amounts awaiting a lawful condition precedent; the latter become payable when the condition is completed. A customary commission-processing date cannot by itself justify delaying commissions already earned and due.
A useful component record contains the earning period or event, calculation basis, gross amount, amount previously paid, amount still due, applicable due date and evidence reference. Mark an unascertained amount explicitly and assign the calculation or rule question. Do not use “pending” to mean both not yet earned and earned but not calculated.
Keep required withholding, benefit deductions and support-order instructions in the payroll calculation, with the proper reviewer for any unusual final or lump-sum treatment. A gross wage comparison is not an authorization for the net amount. Confirm the actual wage statement and payment result after the normal lawful payroll treatment has been applied.
Keep deductions and severance on their own instructions
A manager's recovery request is not a payroll deduction authorization. Separate the claimed debt, supporting evidence, applicable legal limits and any required employee authorization from the wages calculation. This lets the team decide whether recovery is permitted without turning the wage deadline into leverage for returning a laptop or signing an exit document.
California's deductions guidance describes restrictions on offsets and specifically notes an unlawful final-pay loan balloon deduction even when authorized in writing. Do not assume a signature makes every deduction lawful. Obtain a reviewed instruction for advances, prior overpayments, equipment or other proposed offsets before including them.
An unsupported recovery should be removed from the proposed wage calculation while its own review continues. That is different from deciding the employer has no claim at all. Preserve the claim reference and owner in the appropriate process. Do not invent a negative earning or reduce recorded hours merely to make the desired net payment appear in the payroll system.
A dispute about one amount also needs a precise boundary. California's Final Pay explanation says wages that are due and undisputed must be paid without a release even when another amount is disputed. Record the undisputed payment and the separate contested issue. A reviewer should be able to identify what was paid on time and what factual or legal question remains.
Handle severance under its actual agreement, policy and legal review. Texas's final-pay and severance guidance, for example, distinguishes promised severance obligations and other post-termination payments. A separate severance timetable does not establish when earned wages are due. Conversely, labeling a payment severance does not resolve its tax or unemployment treatment. Give those questions to the responsible specialists.
Keep the employee explanation equally clear. State which wage components the payment covers, what deduction instructions were applied and which separately identified item remains under review. Do not ask the employee to sign a broad acknowledgment that every possible amount has been settled merely to collect wages already due. Use the reviewed documents and preserve any actual delivery or receipt evidence.
Schedule the employee's payment, then work backward
Once the wage-law reviewer establishes the required payment result, ask the payment team to identify a route that can actually achieve it. Separate the legal deadline from the provider's submission cutoff, approval cutoff, funding requirement, processing date and employee-access date. A batch accepted before midnight is not necessarily a payment available that day.
For a planned separation, work backward from the due event. Confirm who can calculate the amount, who can approve it, who can fund or sign the payment and who will deliver it. Assign a backup at every deadline-sensitive step. If same-day local payment is required, the team needs a reviewed way to produce and tender that payment, not just a service ticket requesting faster processing.
Check the lawful method and place of payment as well as the amount. California's payday FAQ describes final-payment location rules and a limited mailing option for a qualifying quit without 72 hours' notice at the employee's request. It also addresses final direct-deposit authorization. Do not assume an existing bank instruction or a generic mailing request satisfies every separation scenario.
Ask the provider or bank for its actual capability and cutoff for the proposed route. Record whether an expedited option is available for this account, what must be submitted and when funds can be available. These are verification questions, not claims that any particular product supports immediate final pay. An option shown in a sales presentation may require approval or setup the employer has not completed.
Keep calculation approval and payment execution connected. The approver needs the exact employee result and version, the due date, the planned route and any remaining issue. A generic approval to “run termination payroll” can conceal a changed vacation amount or a payment scheduled too late. If a fact changes after approval, identify the affected instruction and obtain the necessary review without losing the wage deadline.
An internal exception approval cannot waive a statutory deadline. When the planned route cannot meet it, escalate immediately to people authorized to resolve the calculation, funding or lawful delivery problem. State the amount and deadline at risk. Do not turn an internal red status into permission to wait while every participant assumes another team is handling the payment.

Plan from the required payment result. Confirm each earlier step's owner and cutoff against that result, including the lawful delivery instruction.
A planned discharge with two unresolved exit tasks
Consider a fictional California employee whose discharge is planned for 10 a.m. Tuesday. The responsible reviewer confirms ordinary immediate-payment treatment, earned vacation payout at the final rate and a lawful local payment method. Assume all listed hours are straight time, the stated vacation balance is valid, and no other earnings or premiums are owed. The example is a gross calculation, not a complete withholding result.
Payroll verifies 24 unpaid hours before the final shift and four hours on that shift, all at $24 per hour. The leave record shows 16 earned unused vacation hours, plus 2.5 additional earned hours through separation, with no further usage. No part of these amounts has been paid or included in another payment.
Unpaid work: (24 + 4) × $24 = $672.
Earned unused vacation: (16 + 2.5) × $24 = $444.
Illustrated gross wages due: $672 + $444 = $1,116.
The manager also requests a $500 equipment deduction and asks payroll to wait until the employee signs a proposed severance agreement. Neither request is an approved instruction in this example. The reviewer directs the team to pay the $1,116 gross wage obligation through the normal lawful withholding process and keep the equipment and severance questions separate.
The dispatch record therefore needs more than “approved.” It records the 10 a.m. wage deadline, reviewed calculation, authorized payment method and person responsible for the actual tender. Equipment recovery remains assigned to its own reviewer. Severance remains assigned to its agreement owner. The existence of those two open tasks does not turn the wage payment into an incomplete draft.
Suppose an earlier payroll export contains only 24 hours and 16 vacation hours. It would show $576 + $384, or $960 gross, leaving $156 missing: $96 for the final shift and $60 of vacation. This is why the reviewer checks the earning cutoff and current balance instead of approving a familiar report total. Compare the exact candidate before payment, then verify the actual result.
If the final shift changes, recalculate before relying on the $1,116 figure. If a later fact reveals additional wages, create a linked adjustment record with its own applicable deadline. Keep the first payment in the comparison so a correction pays the remaining amount rather than repeating the entire wage obligation. The illustration does not authorize delaying a known amount while waiting for a perfect final file.
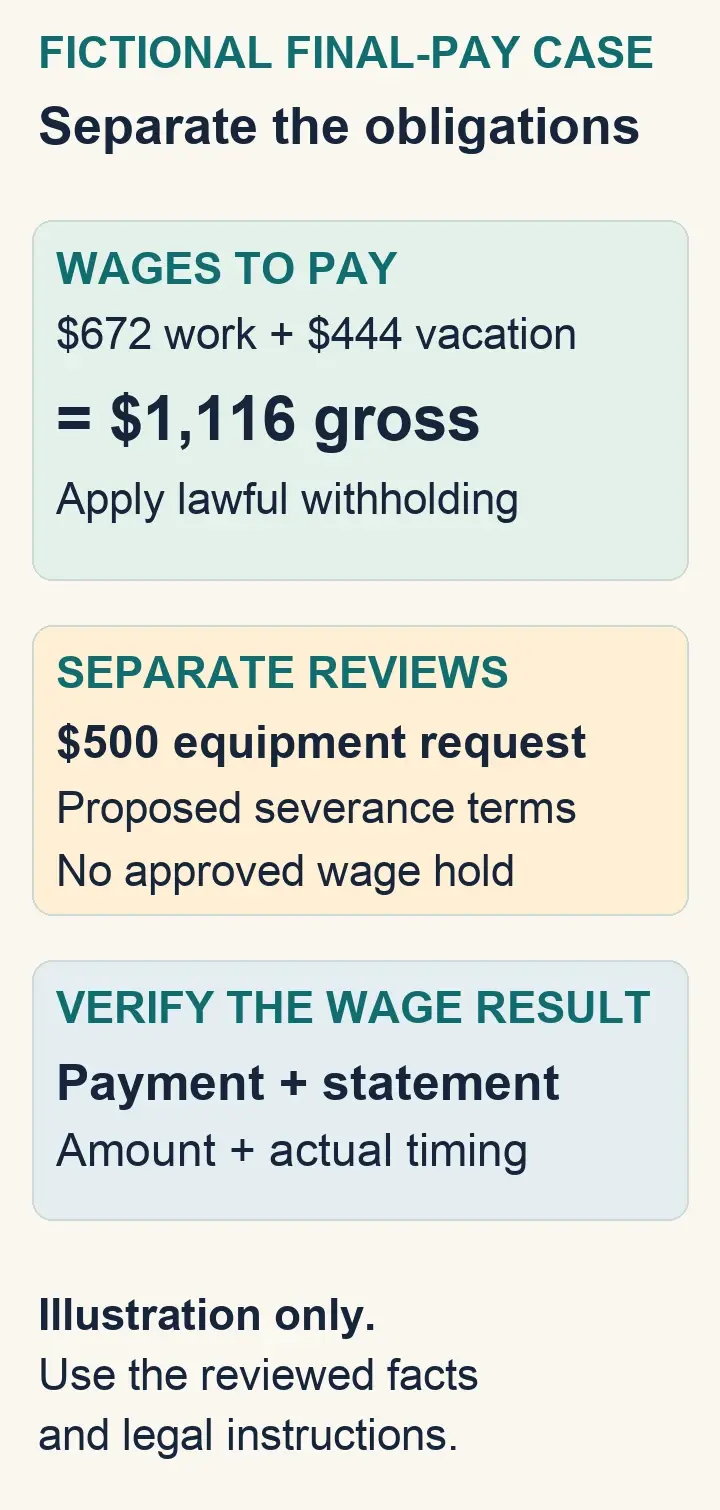
The wage calculation and its delivery stay visible even when other separation tasks remain open. The illustrated amounts do not determine withholding or authorize a deduction.
Final Pay Dispatch Record
Copy this record for one employee separation. Repeat the component entry for each distinct amount and deadline, and repeat the payment entry if more than one payment is needed. Store sensitive employee, account and legal records in the employer's controlled systems; use references here. A missing answer triggers an assigned action, not an automatic extension of the payment deadline.
Separation and rule decision
1. Employee and legal employer: Record the internal identifiers and the employing entity.
2. Actual separation event: Record who initiated it, the notice received, effective date and time, final work and any later change.
3. Relevant locations and coverage: Identify work locations and the reviewer-confirmed jurisdiction, coverage or special provision.
4. Required payment result: Record the source, provision, due date/time/time zone and lawful method or place requirements.
5. Rule owner and urgent contact: Name the reviewer, backup and route for an immediate timing or classification question.
Check the facts against the rule before scheduling payment. If either changes, reopen the affected instruction promptly.
Amounts and exclusions
6. Component entry: Identify the earning event or period, calculation basis and gross amount; repeat as needed.
7. Prior and in-flight payments: Record amounts already paid or already submitted, their status and which obligation they cover.
8. Remaining amount and deadline: Identify the amount still due for each component and its reviewed payment deadline.
9. Leave payout instruction: Reference the plan, applicable rule, balance through separation, rate and calculation.
10. Deduction and order review: Reference lawful withholding, benefit or support-order instructions, and identify proposed recoveries awaiting authorization.
11. Separately unresolved item: State the earning condition, disputed fact or calculation question, responsible owner and next review event.
An unresolved component needs a reason and an owner. It does not change the deadline for a different amount already due.
Payment preparation and dispatch
12. Exact payroll candidate: Reference the employee result, wage statement and version approved for payment.
13. Amount authorization: Record the reviewer, approval time and the components included or expressly excluded.
14. Executable route: Identify the verified payment method, required authorization, place or address and employee-access expectation.
15. Preparation and funding cutoffs: Record the calculation, approval, funding and dispatch times needed to meet the wage deadline.
16. Dispatch owner and backup: Name who will execute or tender payment and who acts if that person or route is unavailable.
17. Failure response: Identify the escalation contact, alternative lawful route and the evidence needed before replacing an uncertain payment.
Approval authorizes the specified action. It does not prove delivery, and an internal exception cannot waive the applicable wage deadline.
Observed result and remaining work
18. Actual payment evidence: Record payment identifier, amount, issue or tender evidence, access or settlement information and relevant timestamps.
19. Employee explanation and statement: Record how the wage breakdown and required statement were provided and where pay questions go.
20. Difference or failed payment: Identify a missing amount, rejection, noncollection or uncertain status and the assigned response.
21. Later-component follow-through: Record the trigger being watched, next check, calculation owner and applicable payment instruction.
22. Closure and retention reference: State which payment obligation is verified complete, which tasks remain open and where the supporting records are retained.
Close against the observed result for the specified obligation. Keep the equipment, severance or later-earning work open under its own owner where necessary.
When the planned payment route fails
First determine what actually happened. A rejected funding request, a bank file accepted for processing, a check printed but not tendered and a payment received by the employee are different states. Obtain the relevant provider or bank evidence and establish which amount remains unpaid or uncertain. Do not treat a successful payroll calculation as proof that money arrived.
If a bank submission might already have succeeded, identify its status before issuing a replacement. Coordinate cancellation, stop-payment or reissue instructions with the responsible payment team and applicable rules. A blind second payment can create a recovery problem while the first one still moves through the system. The alternative route needs both a timely-payment plan and a clear treatment of the original instruction.
Do not use an unreachable employee as a reason to mark the matter paid and archive it. Preserve contact attempts and the reviewed tender, mailing or unclaimed-wage instruction that applies. The California payday FAQ, for example, describes a route for non-negotiated final checks after reasonable efforts to locate the employee. That is a specific process to review, not a national rule that mailing always completes payment.
If the deadline has passed, escalate the actual facts promptly. Record the amount, when it was due, the attempted route, the current status and the proposed corrective action. Have the responsible reviewer address any additional obligation or employee communication. Backdating an approval or a pay date cannot change when the payment actually occurred.
Use the incident to change the failed operational step. A local signer unavailable at discharge needs a reliable backup; a missing final time record needs an earlier intake; an account without an expedited option needs a verified alternative. Keep the remedy specific to the failure rather than adding another generic approval that consumes the time needed to pay.
After separation, watch for another amount becoming due
The employee's inactive status should not hide compensation that becomes payable later. Keep a monitored list of commissions, bonuses, corrections or other components with a named owner and a defined event to check. Record the applicable earning and payment instruction rather than scheduling every outstanding item for an arbitrary monthly cleanup.
A later amount can have more than one consequence. The federal bonus-allocation rule addresses additional overtime for a bonus allocated to earlier workweeks. The federal deferred-commission rule addresses allocation and additional overtime when commissions are ascertained later. Use the appropriate method for the actual compensation; a current payment date does not make every earning belong to the current workweek.
Match each new payment with earlier paid amounts. If the original vacation payout used 18.5 hours and a reviewed correction establishes 19 hours at the same $24 rate, the illustrated additional gross vacation amount is 0.5 × $24, or $12. This narrow example assumes the only change is the balance. It is not a materiality threshold or permission to ignore a small amount.
Retain enough evidence to reconstruct the separation, rule decision, calculation, authorization and actual payment. Link later corrections to the original dispatch record without overwriting it. Apply the employer's reviewed retention schedule and any legal hold; do not invent one universal destruction date for all final-pay records.
Close the wage obligation once its actual required result is verified, while leaving genuinely separate work with its own owner and due date. A returned laptop does not prove a wage payment, and a completed wage payment does not settle every possible later earning. That distinction lets the team follow the remaining work without keeping the entire separation permanently labeled pending.
Questions about final-pay execution
Can we wait for the manager to approve the timecard?
Escalate the missing factual review and determine what must be paid by the applicable deadline. Texas's final-pay guidance expressly says the paycheck cannot be held past the deadline because a timesheet was not signed. Preserve the known work record and the action taken to resolve missing information rather than treating approval software as the wage rule.
Does an off-cycle run automatically solve an immediate deadline?
No. It identifies a processing route, not necessarily timely employee access or lawful tender. Confirm the account's cutoff, funding, payment method and actual result required by the applicable rule. If that route cannot deliver, use the reviewed escalation and alternative payment instructions.
Can we combine wages and severance into one payment?
The responsible reviewers must establish what is due, when it is due and the correct treatment of each component. Combining items for convenience cannot supply those decisions. Where the instructions permit one payment, preserve the separate components and statement detail; where they require different dates or conditions, keep the routes distinct.
What should a payroll provider demonstrate?
Use a realistic separation with a short deadline, a last-shift change, leave payout and one proposed recovery. Ask the provider to show supported calculation, approval, funding, delivery and correction steps, including the employer's remaining responsibilities. This is a proposed acceptance exercise, not a claim that any product has passed it.
Explore more payroll guidance:

About the author
Ben Scott writes and maintains payroll decision guides for founders and operators. His work focuses on execution realities and how decisions hold up under growth, complexity, and controls and documentation pressure. He works hands-on in HR and leave-management roles that intersect with payroll-adjacent workflows such as benefits coordination, cutovers, and compliance-driven process controls.


