Bonus Payroll Controls: Approve the Award, Verify the Payment

Updated: 2 days ago
Finance has approved the bonus pool, but payroll still has unanswered questions. One manager has changed a recipient, another has promised take-home pay, and part of the award relates to earlier overtime weeks. A budget approval cannot supply the missing payment instructions.
Control a bonus batch by connecting the approved award to named recipients, reviewed payroll treatment, an exact calculated run and the eventual payment results. Establish the gross or net promise, earning period, withholding method, overtime work, deductions and payment deadline before release. Preserve the evidence when any of those decisions changes.
This guide is for U.S. employers processing cash bonuses for employees. It provides an original Bonus Batch Release Record and fictional checks for recipient amounts and withholding. The operating controls are recommendations to adapt to the employer's responsibilities, staffing and actual payroll service. Employee entitlement, state requirements and unusual compensation arrangements need their own supported review.
Contents
Turn the award into a complete payroll instruction
Start with the decision that created the award. Obtain the applicable plan, award letter or authorized instruction, its version, the population it covers and the period for which the bonus is earned. Keep any employee communication that explains conditions or a promised amount. A manager's later spreadsheet should be traceable to that source.
An instruction should establish the legal employer, recipient identifier, approved bonus amount, payment basis, earning dates and intended pay date. Explain exclusions, prorations and changes in eligibility. A company-wide total can help finance control the budget, but payroll needs the underlying recipient decisions to know how that total becomes individual wages.
Separate approval of the award from approval to release a particular payroll. The compensation approver establishes the payment's authorized purpose, recipients and amount. Payroll translates that instruction into calculations and records. The release reviewer checks that the resulting run reflects the authorized instruction and is ready for the selected payment route. Finance confirms the funding arrangements and accounting treatment assigned to it.
These responsibilities can sit with a small number of people. Make the handoffs explicit even when one person performs several tasks. A second reviewer can inspect the approved list, changes and preview without rebuilding the entire batch. Where independent review is limited, use a documented compensating review by someone with appropriate authority and access; do not label a self-check independent.
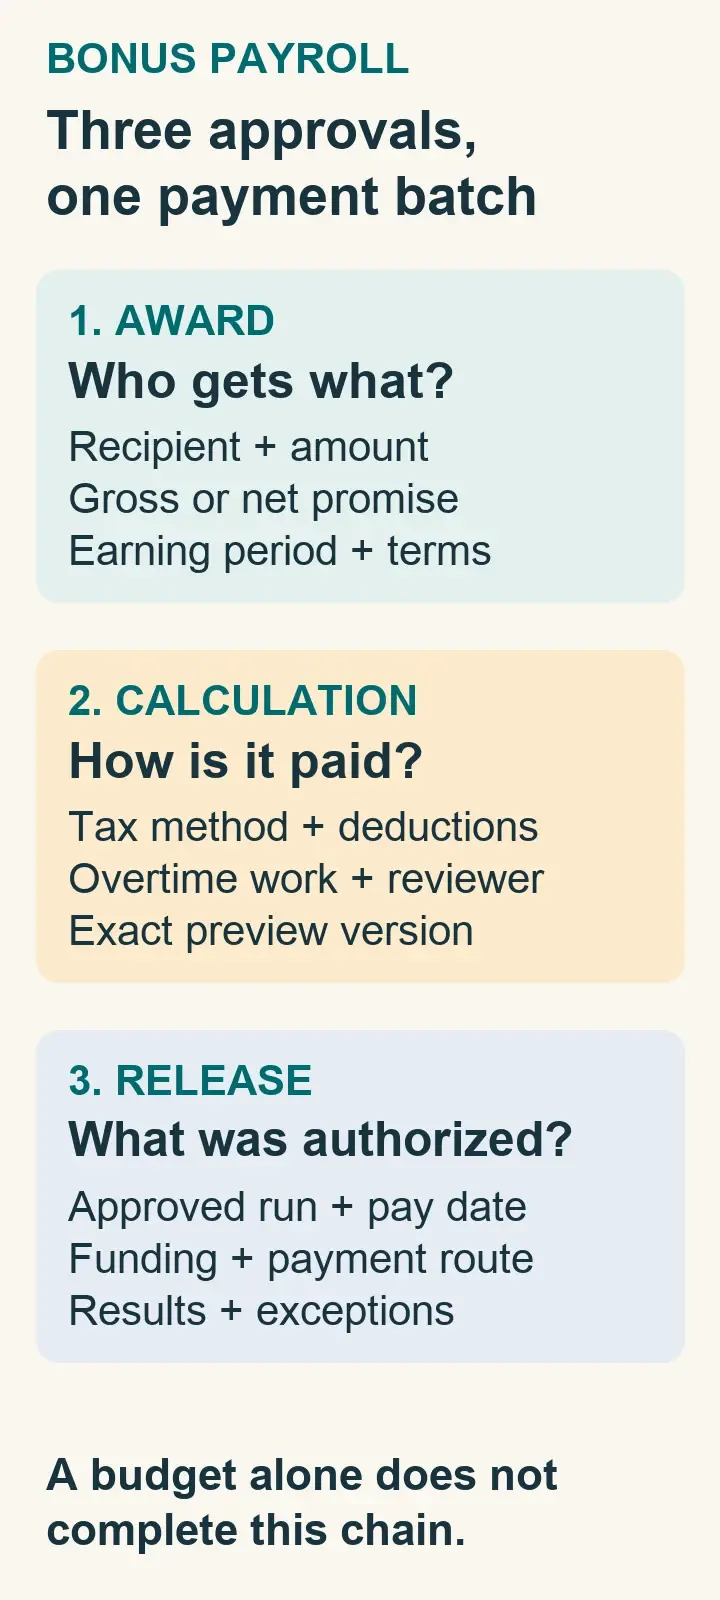
Connect the award, calculation and payment decisions. A budget approval does not complete the whole bonus release.
Resolve whether the promise is gross pay or a specified net payment before the employee announcement. A gross award leaves applicable withholding and deductions to reduce the amount delivered. A net promise can require additional gross wages and employer cost. It needs an approved scope for the taxes or deductions the employer intends to absorb, followed by a supported calculation.
Keep the instruction separate from a proposed repayment or clawback. If repayment conditions exist, retain them and route their application through the appropriate legal, tax and payroll review. Do not quietly offset an unrelated wage payment because a manager wants the bonus budget restored.
Finally, identify the applicable payment deadline and who confirmed it. Internal approval and cutoff dates should be arranged around that obligation. An unresolved internal signature is an escalation problem when wages are due; it does not establish a new employee payment date.
Give the bonus two separate classifications
The payment's federal overtime treatment and its federal income tax withholding treatment answer different questions. A description such as discretionary, spot or year-end is insufficient to complete either review. Record the facts and the reason for each treatment, then configure the earnings code accordingly.
For the federal discretionary-bonus exclusion from the regular rate, section 778.211 requires the employer to retain sole discretion over both whether to pay and the amount until at or near the end of the relevant period, without a prior contract, agreement or promise causing an expectation of regular payment. A bonus announced in advance under a formula does not become discretionary because a manager signs the final list.
The Department of Labor's bonus guidance explains that nondiscretionary bonuses enter the regular rate unless another statutory exclusion applies. For an employee subject to overtime, record the approved classification and any exclusion relied upon. Keep the plan facts available to payroll instead of sending a bare instruction to use an exclusion code.
For example, an announced attendance award earned under stated conditions calls for a different analysis from an unannounced recognition payment whose fact and amount remained undecided until the end of the period. The examples identify facts to review, not automatic classifications for every attendance or recognition program.
Build the classification review into plan setup, then check whether this payment follows that approved version. Changed criteria, new promises or a different earning period may require a new review. Reusing last year's pay code is useful only when the underlying facts still support it.
Maintain the separate supplemental-wage withholding decision even when the payment qualifies for an overtime exclusion. An overtime exclusion does not establish an income tax exemption. Likewise, selecting a supplemental withholding method does not perform the employee's overtime calculation. Employees' exemption status and unusual plans should be reviewed on their actual facts rather than inferred from salary or job title.
Finish the overtime work attached to the award
For an included bonus, identify the workweeks to which it relates, the employee's hours and overtime, and any adjustment already paid. The earning period can precede the payment date. The Department of Labor's Field Operations Handbook describes allocating a later-determined bonus back to its earning weeks and calculating the additional premium for overtime weeks.
Give this work an owner before choosing the release date. Payroll needs historical time records, the bonus formula or allocation basis and the earlier calculation. A quarterly bonus file with names and amounts alone leaves an important dependency unresolved. An absence of historical hours in the current system does not establish that no overtime was worked.
Consider a simplified fictional case: a later $100 bonus belongs to one 50-hour workweek with ten statutory overtime hours. Assume an ordinary hourly arrangement, correctly paid straight-time wages and original overtime premium, with no other relevant compensation or special rules. The bonus adds $2 to the hourly regular rate, so the additional premium is $2 × 0.5 × 10, or $10. The later gross amount is $110 if neither the bonus nor that adjustment has been paid.
Use this calculation only for its stated assumptions. Multiple weeks, multiple pay rates, an alternative allocation or a bonus calculated as a percentage of earnings needs the appropriate detailed method. Confirm whether the payroll service performs the necessary historical calculation and what the employer must supply.
The federal time-of-payment rule requires overtime to be paid on the regular payday, with a limited rule when its correct amount cannot yet be determined. It does not authorize an indefinite wait for administrative convenience. Record when the amount became ascertainable, the calculation deadline and the responsible reviewer's payment instruction.
If some recipients need extra work, identify their cases individually. Establish whether supported payments can proceed while an urgent, lawful route resolves the remaining cases. Preserve each employee's amount due and deadline. A batch status called Hold is an internal control label, not permission to postpone wages.
Record the withholding method and the gross-to-net result
IRS Publication 15 treats bonuses as supplemental wages. For 2026, the optional flat federal income tax withholding rate is 22%; the mandatory rate on supplemental wages above the $1 million annual threshold is 37%. Check the applicable rules for the payment rather than assuming every bonus uses the optional rate.
Under the supplemental-wage regulation, optional flat withholding requires the payment to be separate from regular wages or separately stated, and federal income tax must have been withheld from the employee's regular wages during the current or preceding calendar year. The mandatory high-amount rule is a separate consideration.
For the portion outside the mandatory high-amount rule, use the aggregate procedure if optional flat withholding is unavailable. Where it is available, the employer can still use the permitted aggregate approach. If regular and supplemental wages are combined without specifying each amount, Publication 15 describes withholding as a single payment for the regular payroll period. A separate bank deposit by itself does not document the tax calculation.
Have the payroll tax owner record the method, eligibility facts, relevant payroll period and calculation evidence. For an aggregate calculation, identify the regular wages and previous withholding used in the calculation and account for other supplemental payments in that period as required. Review the actual preview; an earnings label or processing shortcut is not evidence that the correct method ran.
A withholding check with a deliberately limited result
Assume a separately identified $1,000 gross bonus qualifies for optional 22% federal income tax withholding and is below the mandatory threshold. Federal income tax withholding is $220, leaving $780 before other applicable taxes and deductions. That $780 is not a promised net deposit.
Social Security and Medicare taxes, including Additional Medicare Tax withholding where applicable, and state or local withholding can also affect the result. Confirm each employee's actual setup and year-to-date position. Communicate the withholding method without predicting a refund or the employee's final annual income tax liability.
For larger awards, review cumulative supplemental wages for the calendar year, not merely this batch. The rules contain aggregation provisions for employers under common control and certain agent payments. A provider conversion or a second payroll account should not silently reset the relevant history. Escalate threshold crossings and unusual payer arrangements to the tax owner.
If a manager promised a net amount, return to the approved gross-up scope before finalizing. Determine the actual gross wages, employee deductions and employer charges under that scope. A change in the calculation can change the required funding and the approval amount; obtain review of the resulting payment rather than editing withholding to manufacture the desired deposit.
Review plan deductions and income-withholding orders
A bonus run deserves a payment-specific deduction review. Determine which instructions apply to the bonus, which balances or limits matter and which changes have been authorized. A regular-payroll default can be inappropriate for a special run, while a blanket instruction to suppress deductions can omit something that must continue.
For retirement contributions, use the plan's definition of compensation and applicable elections. The IRS's 401(k) Fix-it Guide explains that compensation definitions can differ for deferrals, allocations and testing, and that the plan document must be followed. Obtain the administrator's supported instruction for the bonus rather than assuming all plans include or exclude it.
Review child-support orders and other applicable withholding instructions through their established process. Bonus-specific reporting may affect the schedule. Washington, for example, requires reporting of payments over $500 for employees with a current Washington income-withholding order that includes past-due support. Its published instructions also address the response and withholding process. That is a Washington example, not a national threshold.
For the actual employee, record the governing order, jurisdiction, reporting or withholding instruction and responsible owner. Keep sensitive order details in the controlled records that require them. The release record can reference that evidence without circulating it with the general compensation approval list.
Software options still require an authorized decision. OnPay's bonus instructions, for example, show a setting to hold employee deductions for a special run. The existence of that option does not establish whether the employer may suppress a particular retirement contribution or court-ordered withholding. Check the instruction and preview before using it.
Also review instructions that interact with the payment basis, such as a separate retirement election or an approved deduction correction. Record which version applies to this run. If a question changes the employee's payment, identify the amount affected, the owner and the decision deadline instead of leaving a generic note that benefits will check later.
Choose the pay date with the release and funding teams
Put the employee pay date, payroll submission deadline, funding requirement and internal review completion on the same calendar. Add the deadlines for any historical overtime work, plan instructions or required lump-sum reporting. Work backward from the date the employee must receive payment, using the actual service and banking requirements.
Use the regular run when it supports the approved timing and calculation requirements and leaves enough time to review the bonus alongside ordinary wages. An off-cycle run can help isolate a separate payment or meet a supported deadline, but it adds another release, funding and reconciliation event. Obtain the provider's actual processing conditions and charges when relevant; the label off-cycle promises neither same-day delivery nor a particular tax method.
Approve the complete cash requirement. Separate employee net payments, withheld amounts, employer taxes and contributions, and any service charges. Avoid counting withheld taxes twice when reconciling a provider funding debit, and do not mistake the employees' net deposits for the entire employer obligation.
A large bonus batch can also affect the federal tax deposit deadline. IRS Notice 931 says an accumulated employment-tax liability of $100,000 or more on a day in a deposit period triggers a next-business-day deposit requirement. Have the tax owner check the employer's combined liability and deposit responsibilities, including other payroll activity, rather than evaluating the bonus in isolation.
Confirm who submits and monitors each payment or deposit when a provider is involved. Retain the funding instruction, authorization and expected collection date. If funding is insufficient, escalate immediately to the responsible finance and payroll owners with the amount, deadline and available supported alternatives.
Manage the employee communication from the approved schedule. State the pay date, whether the payment is separate, the approved gross or net basis and where questions should go. Avoid presenting an estimated preview as a completed payment. If circumstances change, explain the confirmed next step and who is resolving the exception.
Compare each recipient before authorizing the run
Freeze the approved recipient list and identify the version imported or entered into payroll. Then compare the actual calculated run with the approved instructions by employee identifier, employer, amount, earning code and relevant period. Check additions, omissions, duplicates and changes in payment basis as well as the batch totals.
A matched total is a useful check with a limited conclusion. In this fictional example, the approved gross bonuses are $1,000 for employee A017 and $1,500 for B026. A preview showing $1,500 for A017 and $1,000 for B026 has the same two recipients and the same $2,500 total. Each employee is still $500 away from the approved amount.
The appropriate response is to correct the entered amounts against the approved list, recalculate and review the new preview. Preserve the failed comparison and its resolution. Do not alter the source approval to make it agree with the mistaken preview. If the business actually changes the awards, obtain a new authorized version and make that change visible.
Separate the bonus amount from any additional overtime adjustment or gross-up. A $2,500 approved bonus list might produce a larger gross payroll requirement for supported reasons. Explain each component and reconcile it to its own authorization or calculation. A single combined gross total can conceal both a correct adjustment and a wrong bonus.
Review the deduction and tax results for the affected populations. Useful cases include someone near a relevant year-to-date threshold, a former employee, an employee with an applicable order, a net promise and a bonus covering historical overtime. Choose cases based on the batch's actual risks; this is not a fixed sample size or permission to ignore the remaining recipient comparison.
The final release approval should name the exact preview or run version, the pay date and any remaining exceptions. If someone changes an amount, recipient, tax method or deduction after that review, return the affected result for approval. Keep the authorization attached to the run that will actually be submitted.
For a small batch, a documented recipient-by-recipient comparison can be enough. For a large batch, use a reliable comparison process with exception output and a reviewer who can explain how completeness was checked. Automation should leave evidence of what it compared and which differences were resolved.
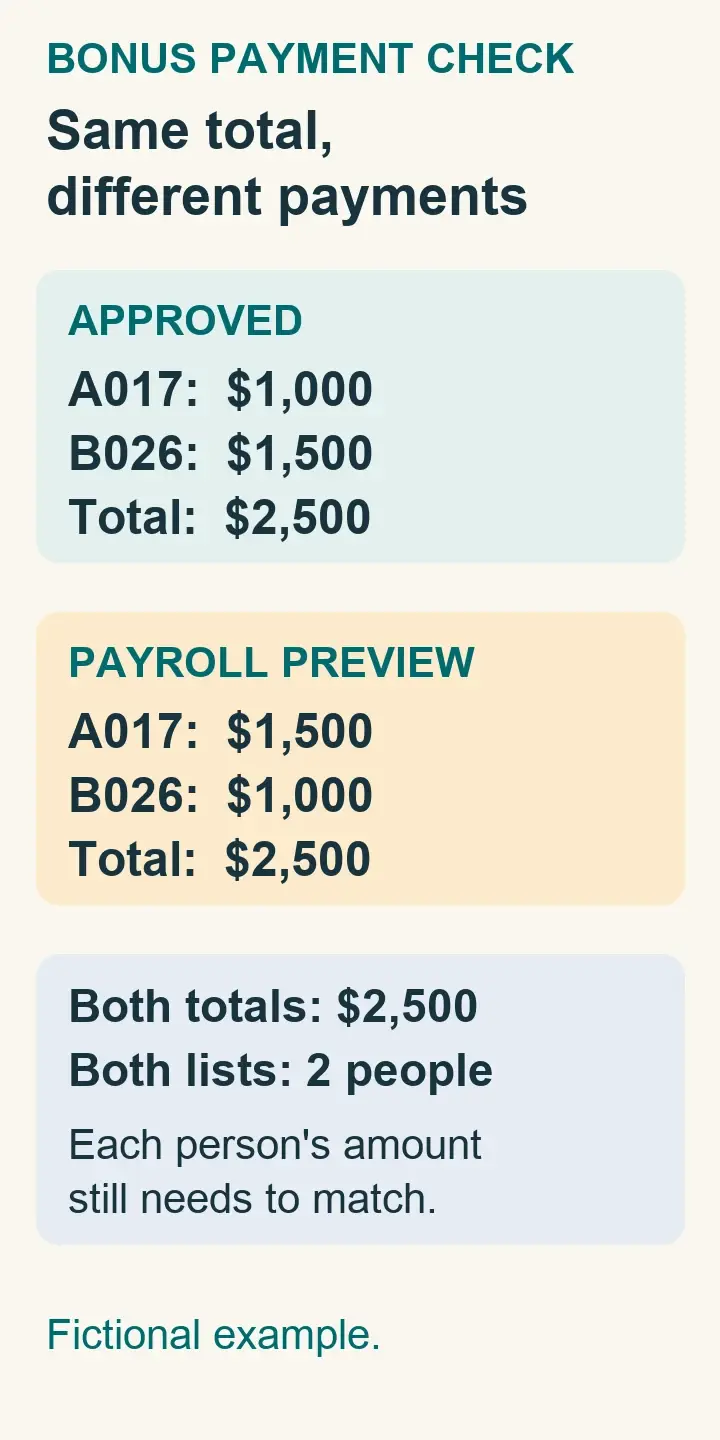
A recipient-level comparison catches the swapped amounts even when the fictional batch total and headcount agree.
Copy the Bonus Batch Release Record
Use one record for a defined bonus batch, with a controlled recipient schedule attached. Complete the fields before release and update the payment outcomes afterward. Write Not applicable with a reason where appropriate; an unanswered field is not an approval. Store personal, bank and order details in their controlled source locations, using references here.
Award instructions
1. Batch identifier and approved list version: ______.
2. Legal employer, award purpose and earning period: ______.
3. Eligibility rule and recipient schedule reference: ______.
4. Gross or net promise and employee communication: ______.
5. Award approver, authorized amounts and decision date: ______.
6. Payment obligation, due date and review reference: ______.
Resolve missing compensation decisions with the authorized owner. Record the applicable payment obligation while arranging the review; this form does not change it.
Calculation decisions
7. Overtime classification, supporting facts and reviewer: ______.
8. Affected workweeks, hours and historical records: ______.
9. Bonus allocation and additional overtime calculation: ______.
10. Federal withholding method and eligibility evidence: ______.
11. Cumulative supplemental wages and threshold review: ______.
12. State and local withholding instructions: ______.
13. Retirement, deductions and order instructions: ______.
Keep the calculations and governing instructions with their evidence references. A tax-method choice does not complete overtime or plan review.
Run comparison
14. Approved source and calculated preview versions: ______.
15. Recipient, employer and amount comparison result: ______.
16. Earnings code, earning period and payment basis check: ______.
17. Bonus, overtime and gross-up component totals: ______.
18. Tax, deduction, net payment and employer-cost review: ______.
19. Pay date, submission deadline and funding confirmation: ______.
20. Preparer, release reviewer and review evidence: ______.
Identify every unresolved difference and its owner before authorization. Re-review a changed result against the correct approved version.
Payment and follow-through
21. Final release decision, exact run version and approver: ______.
22. Actual submission confirmation and provider reference: ______.
23. Employee payment results and failed-payment cases: ______.
24. Tax deposit, plan remittance and accounting follow-through: ______.
25. Open exceptions, owners, due dates and next actions: ______.
26. Evidence location, access owner and closure review: ______.
Close the batch only when its actual outcomes and remaining cases can be explained. Carry unresolved payments into the exception process with their original references.
For the swapped-amount example, field 15 records two recipient differences despite a matching total. Field 21 remains pending until the corrected preview is reviewed; the underlying payment deadline in field 6 stays visible. After authorization, fields 22 and 23 distinguish submission from the payment results instead of treating the review signature as settlement evidence.
Control a late change without concealing the amount due
A late addition should arrive with its award authority, amount, payment basis and deadline. Identify which parts of the existing review it changes. A new recipient can create a different tax, deduction or overtime case even when the added dollars fit within the approved budget.
Preserve the previous version and prepare an explicit change record. Recalculate affected payments and obtain the necessary review of the new result. If the existing run can no longer meet the deadline safely, escalate the specific cases and evaluate a supported alternative. Do not move a due payment to the next cycle simply because that is the easiest internal route.
Treat a rejected or returned deposit as an unresolved payment. Establish what the provider and bank actually did before sending a replacement. Preserve the original instruction, failure reference and authorized replacement route so that correcting one failed payment does not create a duplicate.
An employee who has left the business can still appear in a bonus request. Have the proper owner determine eligibility and payment timing from the plan and applicable requirements, then use the supported payroll route for that employee. Changing the employee's status solely to make a system screen accept the payment can damage other records.
If money was already delivered outside the payroll system, identify that fact before processing another payment instruction. Record the wages, taxes and applicable deductions through the provider's documented process, with the appropriate review of any gross-up or correction. An accounting entry alone does not supply the employee-level payroll history.
Use a clear status for each exception: the amount or calculation still unresolved, the payment result known so far, the owner and next decision time. Avoid closing an employee case merely because the main batch was approved. Provide employees a responsible contact and a confirmed next update when an exception affects them.
Retain the decision trail through accounting close
Assemble a usable evidence pack: the governing award terms, approved recipient version, classifications, calculations, preview comparison, change approvals, final release and actual submission results. Add the records supporting payment failures, replacements and unresolved cases. Keep the connections between versions so a later reviewer can follow the amount from the award to the employee.
Reconcile the bonus components with the posted payroll and accounting outputs. Keep employee bonus expense, additional overtime, employer costs and relevant liabilities distinguishable under the employer's accounting policy. Investigate unexplained differences between the approved batch, calculated payroll, funding collections and posted result instead of using a clearing entry to hide them.
Assign follow-through for tax deposits, retirement contributions, withholding-order remittances and any provider correction. Record the due dates, completion evidence and unresolved items in the appropriate operating records. The bonus release record can point to those records; it should not become a second payroll database.
Apply the employer's retention and access rules to the actual evidence. Limit copies of sensitive recipient and order information, preserve access when a preparer leaves and retain the approved version rather than only the latest working spreadsheet. A useful archive explains which file governed the payment and which later file corrected it.
After the batch closes, review the exceptions that changed the release work: unclear net promises, missing earning dates, late eligibility changes or unsupported calculations. Change the relevant plan handoff or payroll setup and assign an owner. Measure the process using observed exceptions and results, without treating a clean signoff page as evidence that no error could have occurred.
When system limitations recur, turn the documented requirements into a practical demonstration. Ask how the proposed service records the bonus period, supports the required overtime work, applies reviewed deductions, shows changed recipients and reports failed payments. Use fictional or appropriately controlled test data and the actual proposed configuration. A demonstration request is a purchasing check, not a claim that any provider has passed it.
Bonus-payday questions
Can an employee choose the 22% withholding method?
The employer must apply an available method under the supplemental-wage rules and handle applicable withholding instructions correctly. An employee preference does not make an unavailable method permissible. Explain the method being used and direct individual annual-tax questions to the employee's tax adviser.
Does a separate bonus deposit avoid overtime review?
No. The earning arrangement and applicable regular-rate rules determine the overtime work. A separate payment route does not supply that classification or recover the historical workweeks. Give payroll the earning period and the supported calculation before authorizing the payment.
Can we approve the bonus list before every tax result is final?
Award approval and payroll release approval can happen at different stages. Keep each approval's scope clear. The release reviewer still needs a reviewed calculated result and a lawful plan for any unresolved employee cases before authorizing the actual run.
What if the approved budget does not cover a gross-up or overtime adjustment?
Escalate the difference with its calculation and payment obligation. The compensation or finance owner can review the commercial decision, while payroll and the appropriate specialist determine what must be paid and when. Preserve any new approval rather than reducing a required amount to make the total fit.
Explore related payroll resources:

About the author
Ben Scott writes and maintains payroll decision guides for founders and operators. His work focuses on execution realities and how decisions hold up under growth, complexity, and controls and documentation pressure. He works hands-on in HR and leave-management roles that intersect with payroll-adjacent workflows such as benefits coordination, cutovers, and compliance-driven process controls.