Payroll Continuity Under Sanctions and Travel Disruption

Updated: 2 days ago

Before the next payroll cutoff, identify the employees, approvals and payment routes the disruption actually touches. A canceled flight may strand the only bank approver while employees' payment routes remain available. A sanctions alert may affect one transaction while the rest of the run can proceed. Those situations need different instructions.
Payroll continuity under sanctions and travel disruption means preserving lawful pay decisions, a usable processing route and evidence of what happened to the money. Start with the affected population and the next decision deadline. Assign a reviewer to each unresolved question, and keep the unaffected work moving when the authorized team confirms it can proceed.
This guide is for payroll, finance and HR teams coordinating an interruption with their bank, provider, legal or sanctions reviewer and worker-location advisers. It provides an operating record for those decisions. A completed worksheet cannot authorize a prohibited transaction, settle a jurisdiction's wage rules or guarantee a bank's processing time.
Contents
Locate the disruption before changing the run
Create a short incident description from verified facts: the affected employer, workers, service, payment route or approver; the last successful step; and the next step that cannot yet be completed. Record when and from whom you learned each fact. A news report can prompt this check, but it does not establish that your bank account, employee or payroll instruction is affected.
Classify the immediate interruption by the work it prevents:
People or access: the person who approves, prepares or releases payroll is unavailable, or an approved system cannot be reached.
Calculation inputs: hours, location changes or other required instructions are missing or unreliable.
Payment processing: a provider or bank cannot accept or complete a particular instruction.
Sanctions review: a transaction, party, ownership relationship or jurisdiction needs a compliance determination.
Worker circumstances: travel or evacuation changes where someone is staying, whether they are working or how they can receive information and support.
A case can have more than one category. Give each category an owner rather than expecting payroll to solve them all through a payment method change. If the bank is processing normally but a worker cannot access the resulting funds, describe that access problem accurately. Do not record a failed payment without evidence of failure.
Scope the response narrowly enough to act on it. Identify whether a restriction applies to one employee instruction, one employer account, a file or the whole service. Ask the provider whether an affected item can be separated without changing the approved totals or creating a second instruction for everyone else. Retain the answer with the run record.
Use a decision clock with actual dates, times and time zones. Include the employer's review deadline, the bank or provider cutoff and the employee pay date. A 4 p.m. message is not actionable across teams unless they know which clock it uses. Work backward from the earliest decision needed to preserve an available lawful option.
Establish which wage and tax decisions need review
Payroll needs a pay instruction even when the incident starts outside payroll. Ask HR and the applicable wage-law reviewer to determine the treatment of work performed, unavailable work, leave, travel and any proposed change in pay timing. Preserve the relevant hours and manager instructions while that review occurs. Do not silently replace missing time with zero or turn an inaccessible approval into permission to postpone wages.
For work covered by the FLSA, the Department of Labor states that wages required by that law are due on the regular payday for the period covered. Coverage, exemptions and other applicable wage laws need their own review, particularly when work is performed abroad. A bank interruption should trigger an urgent payment and legal response, not an assumed extension.
Separate the immediate payroll calculation from the employer's wider choices. A decision to suspend travel, close an office or offer emergency assistance needs a named policy owner. Payroll should receive the affected dates, population, approved earning or leave treatment and reviewer. A message saying to take care of everyone leaves too much interpretation with the processor.
Maintain a separate list of tax deposits, filings, benefit remittances and other scheduled obligations. Ask each responsible owner whether the same funding or access problem affects their work. Track the applicable deadline and any relief actually verified for that obligation. Do not import an employee's personal tax extension or a general travel notice into the employer's payroll calendar.
Where an instruction remains unresolved, document what is missing, who can decide it and when that person must respond. Escalate before the processing window closes. An operational hold status records a problem; it does not itself determine whether delaying a payment is lawful. Keep the wage response active while compliance and treasury examine the available routes.
Route a sanctions alert to a documented determination
Payroll should preserve the alert and send the underlying transaction facts to the employer's sanctions reviewer. Include the parties and banks involved, the relevant country or region, amount and currency, stated reason for review and any instruction already sent. Use the controlled case system for identity documents and other sensitive support. The incident summary can point to those records without copying them into every email.
OFAC's jurisdiction reaches U.S. persons, including U.S. citizens and permanent residents wherever located, and U.S.-incorporated entities and their foreign branches. Particular programs also reach other persons and activity. Establish which rules apply to the actual employer and transaction rather than assuming that an overseas worker or foreign account removes the U.S. connection.
Distinguish a screening alert from a completed determination. OFAC's current name-match guidance calls for examining the alert's source, relevant facts and applicable restrictions or authorizations. An empty name search is insufficient by itself: sanctions can concern jurisdictions or other non-listed targets. Under OFAC's 50 Percent Rule, entities owned directly or indirectly 50 percent or more in aggregate by one or more blocked persons are considered blocked. Have the reviewer assess the ownership chain; a familiar supplier name is not a complete review of its status.
Ask the reviewer to record a usable instruction: what may proceed, what must not proceed, the parties and route covered, any conditions and the facts that would require review again. If relying on an authorization, identify its current scope and how this transaction fits it. Do not turn a colleague's statement that an exemption probably exists into a release instruction.
Blocking and rejecting have different consequences. OFAC describes blocking as freezing property and rejection as not proceeding with prohibited activity when there is no blockable interest. Have the compliance owner determine the required action, reporting and recordkeeping for the specific facts. Payroll should not relabel a bank's technical rejection as an OFAC rejection or move funds already subject to a blocking requirement.
The reviewer should also define when the determination expires or needs refreshing: a changed payee, intermediary, ownership fact, location, authorization or sanctions measure can change the answer. Retain the version of the instruction actually used. Do not treat a previous successful payroll as continuing permission for every later transaction.
Get a usable answer from the bank or payment provider
Ask a question about the exact payment attempt. Give the bank or provider its instruction or trace reference, amount, currency, intended recipient and submission time through the approved channel. Request a status explanation that distinguishes an accepted instruction, a pending review, a rejected instruction, a return and a completed payment. The provider's terminology and evidence should govern your record; do not invent a universal status code.
Find out what remains within your control. Can the instruction still be withdrawn, and what would establish that withdrawal? Is a recall merely requested? Has a return reached the funding account? What confirmation will the provider supply, who owns the next action and when should the team contact them again? Record the answer rather than the optimistic interpretation of it.
Keep three questions visible:
Is the transaction permitted? The relevant compliance and legal review addresses the facts and any required conditions.
Can this route process it? The bank or provider confirms operational availability, requirements, funding and timing.
What happened to the existing instruction? Transaction evidence establishes what is pending, stopped, returned or settled.

A positive answer in one check does not complete the other two. Preserve each answer and its owner with the proposed action.
When someone reports a sanctions concern, ask who is evaluating it and what information they need. A bank's inability or decision not to process a route does not supply your employer's full legal analysis. Conversely, a legal authorization does not promise that a particular bank will offer the service or meet your desired value date.
Escalate an approaching cutoff through the named relationship contact. Ask for the next confirmed decision time and identify the employer's deadline. Avoid opening competing instructions through several channels just to see which succeeds. Multiple support tickets can be cross-referenced to one case; multiple payment attempts need their own approval and duplicate-prevention controls.
Assess the worker's actual location and work
HR should obtain a dated account of where the worker is staying, where services were performed, the expected duration and whether the worker can safely work or communicate. A mailing-address change is not a complete work-location record. Ask only for information needed by the responsible reviewers, and use a restricted channel for identity, immigration or personal circumstances.
Send those facts to the appropriate tax, employment and immigration advisers. Payroll needs their implementation instruction, including effective dates, registrations or reporting to examine, and what to do while a determination is pending. Do not interpret approval to work remotely as approval of the payroll or immigration treatment in the destination.
U.S. income-tax withholding and social insurance are separate reviews. IRS Publication 54 describes a general U.S. withholding rule for U.S. citizens working abroad and specific circumstances affecting withholding. A canceled flight or foreign address does not establish that the worker qualifies for an exclusion or its withholding treatment.
The IRS also states that wages of U.S. citizens and residents working abroad for an American employer are generally subject to Social Security and Medicare taxes, with exceptions. Totalization agreements can affect coverage in applicable countries. Do not stop those taxes merely because income-tax withholding is being reconsidered; obtain the appropriate coverage analysis and supporting instruction.
For a stranded worker who continues the same duties from a temporary location, keep the existing payment-status inquiry distinct from the location review. For someone unable to work, HR must separately determine leave and pay treatment. Those cases can share an incident identifier while requiring different employee-level payroll instructions.
Safety coordination belongs with the employer's emergency contacts and relevant authorities. State Department crisis guidance explains its assistance for U.S. citizens and important limits, including that in-country transportation generally cannot be provided. Direct workers to current official information and their nationality's consular resources as appropriate; do not promise an evacuation, free transport or a specific return date in a payroll update.
Design an alternative that survives a second review
Consider a backup only after identifying the exact obstacle. An authorized substitute approver may solve an access problem. A different permitted processing route may address a service outage. Neither action alone resolves a sanctions restriction, incomplete wage instruction or uncertain original payment. Ask which fact the alternative actually changes.
Write the proposal before releasing it: employer, approved recipient, amount and currency, funding account, payment method, intended value date, fees, operator and approvers. Explain the status of any earlier instruction and the control that prevents paying the same obligation twice. Give the reviewer the whole proposal rather than requesting permission for an unspecified workaround.
Changing the recipient or route requires its own review. Do not obscure a sanctioned connection, remove identifying information or route money through another person to avoid a restriction. An employee's request to use a relative's account does not by itself establish a permitted or appropriate payroll destination. Have the legal, compliance and payment owners assess the actual arrangement before it is considered for use.
Urgency also creates an account-change fraud risk. The FBI advises independently verifying requests and changes in payment details, including calling a number obtained independently of a suspicious message. Use the employer's established verification channel even when the request arrives from a familiar email account. Record verification without exposing full bank details in the incident log.
Review the employer's authority to release through the alternative. The person who validates an employee request should not acquire an unrestricted bank-release role merely because the usual approver is traveling. Use an existing authorized backup where possible, retain required independent approval and put an end date on incident-specific access. Ask the security owner to restore the normal permission set after the incident.
If an alternative includes currency conversion, treasury should state the contractual pay currency, instructed amount, rate source, fees and expected amount reaching the worker. The wage reviewer should confirm any required treatment of fees or shortfalls. Do not compare a source-currency debit directly with a different-currency receipt and call the difference a payroll variance.
Emergency assistance needs a separate approved treatment. A proposed advance, expense reimbursement or support payment should identify its purpose, recipient, reporting treatment and any repayment terms that require review. Do not net it from later wages simply because finance labeled it an advance. Keep the immediate safety response connected to, but distinguishable from, ordinary payroll.
Follow the original and replacement through settlement
An employee in this fictional case is due $1,800 net. The bank is reviewing the original instruction, and treasury cannot yet confirm its cancellation, return or settlement. Sending another $1,800 creates $3,600 of instructions against one $1,800 obligation. It does not prove a $3,600 cash outflow yet, but it creates an exposure that a single paid checkbox conceals.
Keep the original reference open until its outcome is evidenced. If the authorized team approves another route, record why it is permissible and how the uncertain original is controlled. Where that control cannot be established, escalate the unresolved payment urgently rather than calling the replacement safe. The wage-law response continues while treasury and compliance determine what can be done.
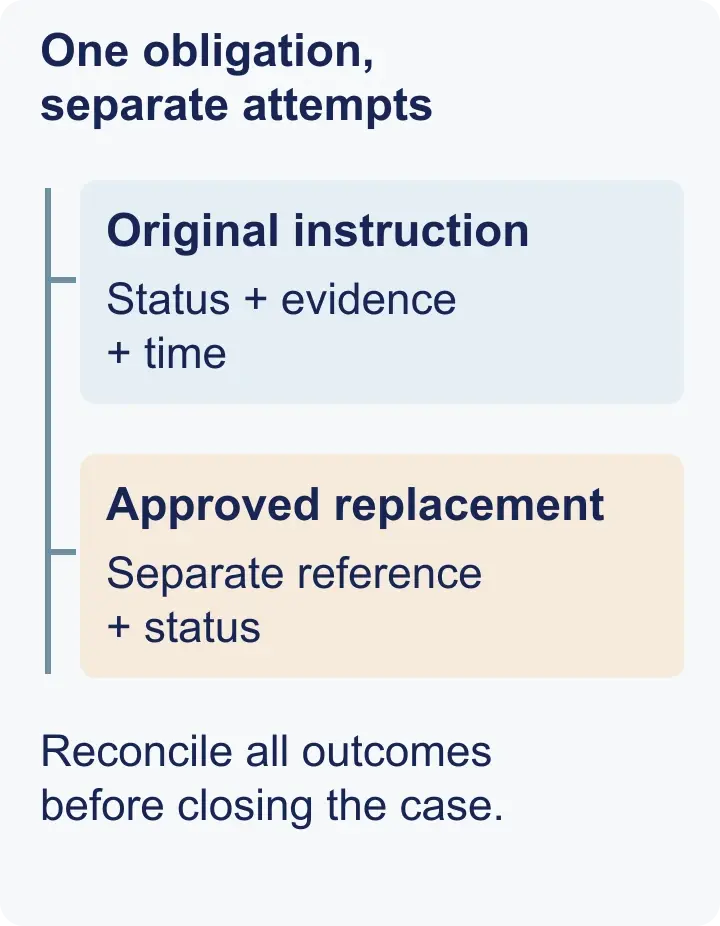
Link the attempts to one obligation. Close each attempt from evidence, then reconcile the employee's total received amount and any remaining amount due.
When a return is confirmed and the team approves reissue, link the replacement to the returned instruction. Preserve the evidence of restored funds separately from approval to release again. For a settled original, investigate a receipt or access complaint through the bank and the employee-support route rather than assuming that a new payment is the next step.
Reconcile by employee, obligation and currency. Show the original amount due, each instructed payment, its latest status, confirmed receipts or returns, and the remaining obligation under the approved treatment. A provider's paid label, a bank debit and an employee's confirmation can answer different questions. Record the evidence relied on and investigate inconsistencies before closure.
Keep accounting informed of pending funds, returned amounts, approved assistance and fees. Do not erase the original attempt when entering its replacement. Finance needs a clear explanation of why two references relate to one wage obligation, and who will clear any pending balance. If both attempts settle, escalate recovery and payroll treatment for review rather than automatically deducting the excess from the next run.
Give employees a useful update without exposing the case
An employee needs to know what is affected, what the employer is doing, what information is needed and when to expect another update. Separate a confirmed payment date from an estimated processing time. If the bank has not confirmed settlement, say that plainly. Avoid asking an employee to make repeated trips to a branch or change accounts without a reviewed reason.
Use a short message such as: Your payment is being reviewed with our payment provider. We have not yet confirmed a new receipt date. We will update you by 2 p.m. London time tomorrow, even if the review is still open. Please use our established payroll contact channel for any account-change request. Adapt the message to the facts; this is an example, not a required legal notice.
Have the compliance and HR owners approve sensitive explanations. Do not describe an employee as sanctioned merely because their name triggered a possible match, and do not promise clearance before review. Keep personal identifiers and the substance of restricted legal advice out of broad team updates. A manager may need the work instruction without needing the supporting passport or bank information.
Offer an accessible contact route and a backup when normal email or telephone service is unavailable. Record failed contact attempts and the next permitted method. If assistance is available under employer policy, explain how to request it without representing it as replacement wages or assuming eligibility. The person coordinating employee support should know who can authorize help and when to escalate an urgent need.
Payment Continuity Decision Record
Copy this record into the employer's restricted incident system. Use one record for each obligation or group of obligations that genuinely shares the same facts, authority and route. Create a separate record for any worker, bank, jurisdiction or original payment status that requires its own decision. Refer to protected evidence by case reference rather than copying full identity or account information.
What changed
1. Scope: Record the incident identifier, legal employer, affected worker or defined population, and incident owner.
2. Work and location facts: Record relevant work dates, actual locations, availability and the HR reviewer responsible for unresolved facts.
3. Decision clock: Record the pay date, required review time, provider cutoff and time zone, plus the escalation contact if a decision is late.
4. Original attempt: Record the obligation amount and currency, instruction reference, latest evidenced status, evidence time and provider contact.
Do not merge different original statuses into one population-level paid or unpaid label. An employee-level exception can remain attached to a wider incident without inheriting the wider group's release decision.
What authorizes the next step
5. Sanctions determination: Record the reviewer's instruction or reason review is not implicated, its factual scope, conditions and refresh trigger; reference the supporting analysis securely.
6. Wage and tax instruction: Record the approved pay treatment and effective dates, separate location or coverage questions, their owners and any unresolved obligation deadline.
7. Proposed action: Record the verified payee reference, route, amount, currency, intended date and the obstacle this action resolves.
8. Processing and duplicate control: Record the provider's route confirmation, treatment of the original attempt and evidence required before another release.
9. Authority: Record the preparer, independent reviewers and releaser, the scope of approval, any conditions and the end of temporary authority.
A missing required determination means the proposed action remains unresolved. Write the next reviewer and response time beside it. Continue reviewing unaffected obligations separately, and escalate any threatened wage deadline immediately.
What actually happened
10. Funding and currency: Record the funding account reference, available funding confirmation, any conversion basis, fees and approved treatment of a shortfall.
11. Execution: Record each released instruction, release time, operator, provider acknowledgment and the next expected status evidence.
12. Employee communication: Record the update sent, safe contact channel, support owner and promised time for the next update.
13. Reconciliation: Record each original and replacement outcome, confirmed receipt or return, remaining amount due and any balance that finance still needs to resolve.
14. Closure and retest: Record the closure reviewer, unresolved follow-through, restored access, evidence location, retention instruction and the change that will trigger another review.
Use the record to issue a specific decision: proceed with the identified approved action; obtain the named review before acting; or stop the identified action and follow the reviewer's instruction. Apply the decision only to the obligations named in this record; it cannot authorize a payment delay, override blocking requirements or resolve another worker's case.
Practice the unavailable-approver scenario
Schedule a rehearsal in which the authorized backup team handles a realistic interruption using fictional or appropriately masked data. Start with the regular approver unavailable and an employee payment still pending. Ask the backup to find the correct run, identify the original attempt and reach the responsible bank contact. A directory entry is useful only if the person can actually obtain the evidence needed for the decision.
Exercise the handoffs in sequence. HR supplies a dated work instruction; the compliance reviewer states the boundary of any required clearance; treasury confirms route, funding and original status; payroll identifies the calculated obligation; an authorized reviewer approves the defined release. Include one item that cannot proceed so the team demonstrates escalation rather than marking the whole exercise complete.
Check practical limits: access from the backup's location, permitted authentication, support hours, holiday cutoffs, contact verification and the ability to retrieve required records. Use approved access methods. Do not share credentials or disable authentication to make the exercise succeed. Record an access failure as work for the system owner, with an approved alternative if one exists.
If the exercise exposes a provider gap, document the exact missing service or evidence. Ask whether it can be resolved within the current arrangement before considering a change. A demonstration of global coverage does not prove payment availability for your entity, bank, currency or incident. Require a written explanation of country service responsibilities and exception support in the proposed contract.
Restore the normal process with the evidence intact
Recovery starts when the underlying interruption ends, but payroll closure requires more. Confirm the final result for every affected obligation and payment attempt, complete required compliance follow-through and identify any unresolved accounting or employee-support work. Assign that remaining work explicitly; do not let closing the incident remove it from the team's view.
Review the first ordinary run after recovery for duplicate earnings, retained temporary bank instructions, changed work locations and assistance entries. Have the responsible owners decide which temporary arrangements end and which require a new standing approval. Confirm that backup access has been removed or returned to its intended role and that the regular approver can resume securely.
Keep the incident record, dated determinations, provider messages, approval evidence and payment outcomes retrievable under the applicable retention requirements. Ask compliance, payroll and legal owners to identify the relevant periods and any hold. Do not apply one generic deletion date to sanctions, wage, tax and personnel records. Restrict access to the sensitive support even when a broader lessons record is useful to managers.
Choose a concrete improvement from the evidence: a missing backup role, an ambiguous bank status, an unowned location review or a communication deadline nobody monitored. Assign its owner and test it before relying on it. A workable continuity plan identifies the next authorized action and preserves proof of its outcome for the workers actually affected.
Browse the Decision Guides library.
Continue with Payroll Operations & Controls.
Explore the Payroll Operations Resource Library for related processes and practical tools.

About the author
Ben Scott writes and maintains payroll decision guides for founders and operators. His work focuses on execution realities and how decisions hold up under growth, complexity, and controls and documentation pressure. He works hands-on in HR and leave-management roles that intersect with payroll-adjacent workflows such as benefits coordination, cutovers, and compliance-driven process controls.