
Government Shutdown Payroll: Keep Pay and Funding Decisions Separate

Updated: 2 days ago

When a federal customer stops approving invoices, the employer still needs an answer for Friday's payroll. The missing receipt belongs in the cash forecast. A proposed change to employees' work schedules belongs with HR and the wage-law reviewer. Payroll needs an approved instruction that connects those decisions without treating one as permission for the other.
For payroll continuity during a government shutdown, first identify the employing organization and the specific interruption. Then establish the pay obligations, cash availability and processing route for each affected group. Preserve the official notice and the decisions made from it, including anything still awaiting an answer.
The method follows the employer's response across U.S. private businesses, federal contractors and grant-funded organizations, while routing federal agency questions to the agency's own rules. It is a reusable continuity method, not a report that a shutdown is currently underway or an agency payroll manual. The examples and amounts are fictional.
Contents
Start with the employer, not the source of its revenue
A person working at a federal building may be employed by an agency, a contractor or a subcontractor. Those relationships can produce different pay decisions when a funding lapse disrupts the workplace. Establish the legal employer before applying a notice to anyone's payroll record.
For a federal agency employee, obtain the agency's authorized status and payroll instructions. OPM distinguishes shutdown furloughs caused by an appropriations lapse from administrative furloughs used for other budget or work conditions. Some functions have alternative funding and may continue under normal rules, as its furlough guidance explains. A private employer should not borrow those federal employee categories to decide whether its own workers will be paid.
For a contractor, determine which contract, location, task order or work package is affected. A closed customer office may prevent site access while other work continues. A delayed invoice approval may affect receipts without changing the work authorization at all. The contracts lead should establish that distinction and identify the person authorized to interpret the customer's instruction.
For a grant-funded employer, identify the award and the actual restriction or processing delay. A grant-funded employee does not become a federal employee merely because federal money supports the position. Finance must assess which funds can support the payroll while HR establishes the employment instruction. Keep a decision about charging an award separate from a decision about wages owed to the employee.
Build a small population list rather than adding a shutdown flag to everyone. Include legal employer, affected program, work location, employee group and the payroll cycles under review. Name the business owner who confirms the group. The payroll ownership model should provide a responsible person even when the usual program contact is unavailable.
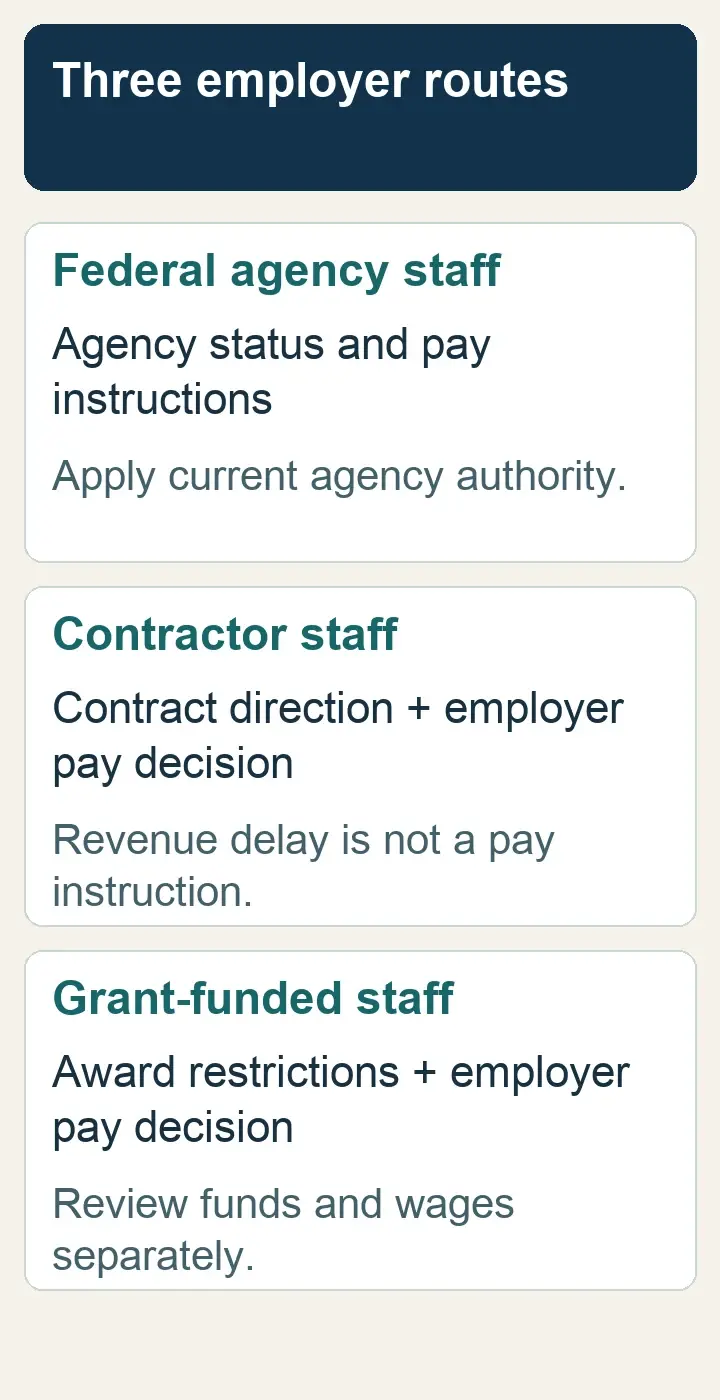
Revenue source does not identify the employer. Choose the applicable route before changing payroll.
Read the notice for an action and a boundary
Preserve the actual agency notice, contract direction, award communication or verified service alert. Record its issuer, issue time, effective time, affected work and any later amendment. Keep the original with the working interpretation so the next operator can see where the conclusion came from.
Ask what the notice changes. Does it stop performance, close a location, defer an approval, change access to a service or merely warn that a disruption is possible? Record what it does not establish as an unanswered question when necessary. A notice saying that invoices may be delayed does not tell payroll which earning code to use next week.
If the contract includes FAR 52.242-15, its Stop-Work Order clause describes a written order from the contracting officer and requires compliance with its terms. It also addresses cost minimization and later contract adjustments. Have the contracts lead evaluate the clause and the actual order; do not assume every funding lapse automatically stops every contract or guarantees reimbursement of every payroll cost.
The employment response is a separate decision. Who will work, on what assignment, from which date, and under what approved pay treatment? Who will communicate that instruction to supervisors and employees? A project manager's view about billable time is useful input, but should not become an unreviewed payroll deduction.
Attach a review time to provisional information. For example: “Site access is unavailable today; contracts will confirm permitted alternate work by 2 p.m.” That describes the current constraint and the next decision. It does not silently create an unpaid day. If the answer affects a processing cutoff, make the responsible reviewer aware of both times.
Protect the workweek when work is reduced
Before implementing reduced hours or a private employer furlough, have HR and the wage-law reviewer assess the employees, jurisdictions, agreements and proposed dates. Specify how actual work will be recorded and who can authorize contact with employees during the period. A supervisor who asks for a short email reply may change the facts payroll must consider.
For covered nonexempt workers, preserve all hours actually worked and apply the relevant minimum-wage and overtime requirements. The FLSA does not turn the employer's loss of revenue into unpaid work. DOL's furlough fact sheet summarizes the federal minimum-wage and overtime framework; state requirements and agreements may provide additional protections. Verify the applicable payday requirements before choosing when any amount will be paid.
For an employee subject to the Part 541 salary-basis requirement, 29 CFR 541.602 generally requires the full salary for a week in which any work is performed, subject to its exceptions. It distinguishes that from a complete workweek with no work and prohibits deductions caused by the employer's operating needs when the employee is ready, willing and able to work. Review the actual arrangement before treating a partial-week closure as a salary reduction.
Consider a fictional contractor that loses access to a customer site on Thursday. One salaried employee worked Monday through Wednesday. Another has been told not to work for the entire following workweek. Those facts require different review, even though both employees belong to the same project. The payroll instruction should identify the actual workweek and approved treatment, rather than applying one percentage reduction to the project roster.
Define the handling of leave separately. Ask HR whether employees may use available paid leave, how requests are approved and whether any applicable rule requires a different result. Leave balances, cash salary and the timekeeping category are related records, but are not interchangeable decisions. A leave-of-absence workflow may provide useful administration controls without deciding the legal treatment of a shutdown-related absence.
Make the revised instruction visible to the person reviewing payroll. Include effective dates, the covered employees, the time source and the approver. If the decision arrives after the normal deadline, record it in the cutoff exception log with its actual approval time. An internal cutoff is a processing constraint, not an answer to whether wages may wait.
Forecast the next debit without spending an expected receipt
Finance should translate the interruption into a dated funding position. Use the provider's actual collection request, including the amounts it will debit together and the amounts collected separately. Confirm the account, available funds, pending withdrawals, restrictions and the time at which the money must be usable.
Keep expected government receipts visible as uncertain receipts until availability is confirmed. A customer has approved an invoice, an agency has scheduled payment and money has reached the usable account are different events. None should be represented by a single “funding confirmed” checkbox.
Suppose a fictional employer must fund $92,000 on Wednesday. Finance verifies $72,500 available for that request after other known activity and restrictions. An expected $25,000 federal receipt has no confirmed arrival time. The current gap is $19,500: $92,000 minus $72,500. The forecast should show the receipt separately, with its uncertainty, rather than reporting a $5,500 surplus.
This calculation does not authorize delayed wages, partial payment or the use of restricted money. It tells management what must be resolved and by when. If authorized funding is unavailable, activate the payroll funding shortfall response with legal, finance and the provider while a usable recovery route still exists.
For grants, finance should document the basis for any temporary source of funds and any later accounting treatment. Do not assume that an advance, transfer or reclassification is permitted simply because the organization intends to repay it. The nonprofit payroll controls guide explains how funding restrictions, labor allocations and payroll records need to remain traceable.
Run the forecast beyond the immediate payday. Include the next payroll, scheduled tax and benefit collections and the point when another receipt must become available. Decide how often finance will refresh the position. A response that resolves Wednesday but ignores the next scheduled debit has only moved the decision.
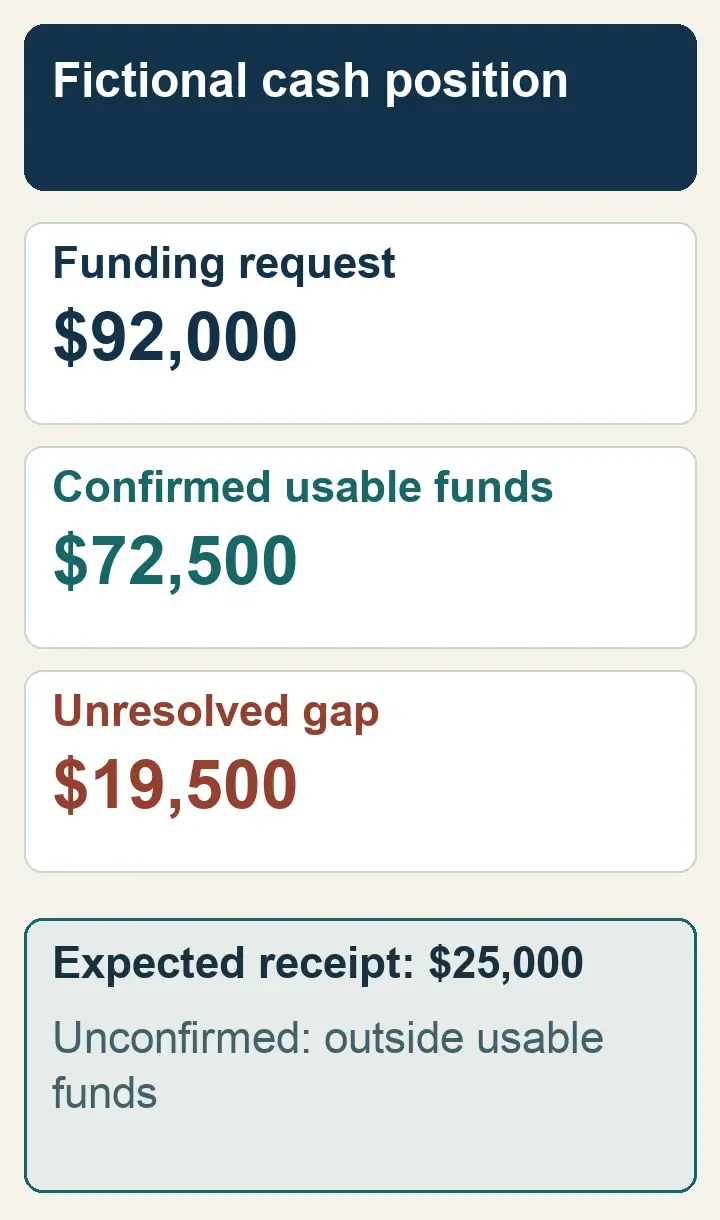
Keep the expected receipt outside usable funds until confirmed. The example is a cash comparison, not permission to defer obligations.
If the disruption exposes a longer-term service problem, keep provider evaluation separate from the active payroll response.
Keep tax dates separate from agency service availability
Do not infer a payroll tax extension from a closed office or a long telephone queue. In its October 21, 2025 lapse statement, the IRS expressly said that regular payroll tax deadlines remained in effect. That dated notice illustrates the distinction; check current official instructions and any relief that actually applies to the employer, tax and period.
The IRS employment tax due-date guidance distinguishes return filing from tax deposits. Completing one does not complete the other. Maintain the employer's actual deposit schedule and filing calendar, with evidence for the period, amount and payment instruction. A provider's debit confirmation also needs to be distinguished from confirmation of the tax payment itself.
Assign someone to check current service announcements if the team depends on a particular federal tool. Record what the service actually permits and the supported alternative, if one exists. Preserve an error message or unavailable-service notice with its time. An unsuccessful attempt helps explain the incident but should not be treated as a receipt or automatic deadline relief.
Use the federal payroll tax calendar to keep separate owners for preparing the return, authorizing a payment and verifying acceptance. Escalate any unresolved deadline to the tax adviser while there is time to assess the available method. Do not repeatedly retry a money instruction without first establishing whether the previous attempt was accepted.
Apply the same discipline to a notice already under response. A delayed agency answer does not prove that the employer's question has been resolved. The tax notice case should retain its own response date, evidence and follow-up owner while the wider continuity event remains open.
Put a replacement approver inside an authorized role
A government contact's absence and an employer approver's absence create different problems. The contracts lead handles the first through the contract's communication route. Management handles the second by assigning an authorized substitute. Payroll should not invent either person's authority because the clock is running.
Before relying on a substitute, confirm what they may approve, for which entity and for how long. Give them the supporting records and appropriate system access. Preserve separation between changing the instruction, reviewing the result and releasing money where practical. Do not solve an absent approver by sharing the person's credentials.
Reconcile the expected employee population and the actual approved inputs before review starts. A government program's internal spreadsheet may no longer be available, but the employer still needs a supported way to establish work and pay. Document the replacement source, its limitations and the reviewer who accepts it. Avoid creating a new permanent source of truth merely to finish one cycle.
The final payroll review should test the resulting pay against the approved work and employment decisions. It should also identify the payment route and any unresolved items. If a calculation or manual instruction must depart from the ordinary process, use the override controls so the permission and implemented result can be compared later.
Ask the provider a bounded operational question: “For this entity and pay date, what approval and funding must you receive, and what can you confirm after submission?” Obtain a case reference and written summary when possible. Do not treat a general statement that payroll remains operational as a promise about a particular unapproved or unfunded run.
Explain benefits and employee assistance without promising coverage
An employee's first question may concern health coverage, a missed deduction or immediate household bills. Give HR and benefits a defined route for those questions. Payroll can explain what was withheld and remitted; the benefits owner should confirm the plan's coverage, premium and arrears treatment with the appropriate administrator or carrier.
Separate federal employee guidance from private plans. The OPM's January 30, 2026 shutdown furlough guidance addresses federal benefits and deductions under its own rules. It does not establish what a private employer's insurer will do. Do not copy a federal coverage assurance into an employee message for a contractor or grant-funded organization.
For a private plan, document the effective status, any employer premium payment, the employee amount that remains due and the approved collection method. Before recovering several missed deductions from a later paycheck, review the plan, authorization and applicable wage rules. Benefits arrears need a reconciliation that distinguishes premiums owed from deductions already taken.
Keep court-ordered withholding on its own review route. An employee's hardship request is not, by itself, authority to suspend an order or change a remittance. Have the responsible reviewer verify what the order and governing rules require for the actual pay available, and retain the decision with the garnishment record.
If management offers an advance or other assistance, classify it before money moves. Establish whether it is a wage payment, an advance recoverable under an approved arrangement, a loan or a separate benefit. Obtain the appropriate tax and legal review rather than labeling every payment “shutdown relief.” Identify how the payment will appear in payroll and whether the next run must account for it to prevent duplicate wages.
Send employees a message that separates confirmed facts from unresolved timing. For example: “Your employer has approved the normal payroll instruction for this pay period. Finance is confirming the funding route. We will provide the next update by 3 p.m. today through this channel.” Use that wording only when those facts are true. If pay is at risk, communicate the actual known risk and approved response without inventing a settlement promise.
Keep sensitive individual circumstances out of the group update and the general incident log. Give employees a private contact for hardship, medical, benefit or garnishment questions. A helpful continuity message tells people where to get an answer without making their details part of the operational briefing.
Maintain a Shutdown Payroll Continuity Brief
Use one brief for one employing entity, affected population and payroll cycle. The brief is a decision aid for the coordinating team. Keep detailed employee records and bank information in the controlled supporting systems, with references here. Copy the fields into an approved document or complete them as separate rows; do not collapse the whole brief into one text block.
Identify the interruption
Record only the group covered by this brief. Split groups when the employer, applicable instruction or pay decision differs.
Employing entity and affected group: ____________________
Payroll period, pay date and workweek boundaries: ____________________
Notice issuer, reference and saved location: ____________________
Effective time, affected activity and current limits: ____________________
Coordinator, backup and next briefing time: ____________________
A warning or expected event stays identified as provisional. Record the evidence needed to replace that assumption.
Settle the work and pay instruction
HR, contracts and the wage-law reviewer contribute within their responsibilities. Payroll records the approved result rather than deciding employment status from a funding alert.
Authorized work, access and schedule decision: ____________________
Actual time source and supervisor confirmation: ____________________
Pay or leave treatment, legal review and effective dates: ____________________
Benefits, deductions or individual exceptions requiring review: ____________________
Approver, authority and outstanding decision deadline: ____________________
If an answer is missing, name the question and person responsible. “Pending” without a decision time does not tell the next shift what to do.
Establish money and processing
Finance verifies usable funds. The provider or bank confirms its own processing requirements and the status of any instruction already sent.
Required collections, amounts, accounts and cutoff times: ____________________
Confirmed usable funds, restrictions and verification time: ____________________
Unconfirmed receipts and unresolved funding gap: ____________________
Approved funding route, provider case and acceptance proof: ____________________
Tax deposits, returns and benefit remittances with separate due dates: ____________________
Required funding minus confirmed usable funds equals the unresolved gap when the result is positive. List uncertain receipts separately; do not subtract them from the gap.
Carry the decisions into recovery
The briefing remains open until the team has reconciled its temporary decisions and assigned any remaining individual cases.
Employee update, approved sender and next update time: ____________________
Temporary payroll entries and duplicate-payment checks: ____________________
Return-to-work or normal-service evidence: ____________________
Pay, tax, benefit and accounting differences still to reconcile: ____________________
Closure reviewer, retained evidence and follow-up owners: ____________________
A reopening announcement starts the recovery review. It does not prove that the payroll, funding and benefit records agree.
Use the brief at each scheduled update. Review what changed since the previous version, which decision is due next and whether any employee or deadline has moved into a different risk position. Preserve prior versions when their instructions governed a payment. Replacing yesterday's “awaiting authorization” with today's “approved” should not erase the time during which approval was absent.
For escalation, present the unresolved question with the available options and the last time a decision can still affect the outcome. The payroll exception escalation framework helps distinguish a payment deadline from a provider cutoff and from an internal approval deadline. The brief should make the decision-maker's action easier, not merely collect evidence of delay.
Provider review can resume after the immediate response is controlled. Bring the missing confirmations, access limits and service handoffs from this brief to that conversation.
Reconcile the restart one population at a time
When funding or access resumes, obtain the actual restart instruction for the affected work. Contracts confirms performance authority; HR confirms the employee schedule; finance confirms usable money; payroll confirms which processing and payment tasks remain. Those events may occur at different times.
Compare each employee's intended treatment with what was actually recorded and paid. Include work performed, leave used, any changed earning, advances or manual payments, deductions and benefit remittances. Make the comparison before loading a broad “catch-up” file. A temporary payment already delivered should not be issued again merely because the ordinary system still shows an unpaid amount.
Federal employee retroactive pay belongs in the agency's authorized process. The Government Employee Fair Treatment Act of 2019 addresses covered government employees and excepted work; it is not a promise that contractor employees will receive government-funded back pay. Agency administrators must confirm the governing authority, covered periods and current instructions before calculating or communicating a payment. Do not infer a private employer entitlement or a payment date from another agency's announcement.
For the private employer, determine the basis of each remaining amount: a correction to wages, a separately authorized payment, an assistance balance or a funding/accounting entry. Use the retro-pay decision process for wage corrections and an approved off-cycle route when the circumstances require it. A cost reimbursement from a customer is a different transaction from an employee wage correction.
Reconcile employer tax reporting and deposits for the amounts actually paid, with the tax adviser deciding any correction needed. Ask benefits to confirm premium and arrears balances. Have finance resolve temporary funding and allocation entries with the award or contract records. Close each difference in its own system while retaining a shared reference to the continuity event.
Finally, compare the brief's closure conditions with the evidence. Can another operator identify the instructions that governed the disrupted periods and the resulting payments? Are unresolved cases assigned with dates? Has management ended temporary access or approval delegations that are no longer needed? A team can return to the ordinary payroll timetable while specific recovery cases remain open, provided their ownership is explicit.
Keep the source history with the payroll evidence
Save the notices and guidance used for each decision with their publication or revision dates and the date checked. A stable web address can later contain revised material. Linking today's page is useful, but does not preserve the instruction that governed a payment weeks earlier.
Source selection matters especially for federal personnel questions. On October 23, 2026, OPM and OMB stated that specified September 2025 documents addressing reductions in force during a lapse had been rescinded in full. Use the current official guidance and agency instructions for the actual question; an archived memo or familiar title does not establish current authority. This guide does not provide a reduction-in-force procedure.
For covered employers, federal wage-record rules generally require relevant payroll records to be kept for at least three years under 29 CFR 516.5. Supplementary time, earnings and deduction support has separate requirements, including two-year periods under 29 CFR 516.6. Other laws, contracts, tax requirements and holds may require more. Apply the organization's retention schedule to the full record rather than deleting the brief as soon as the service resumes.
Keep the public notices, operational brief and restricted employee support in appropriate locations. Give the briefing team enough access to act while limiting access to personal information. Use the payroll record retention guide to assign the record owner, retrieval route and deletion controls.
The next rehearsal should test a dependency that actually failed: an unavailable program approver, a receipt without an arrival date, a missing time source or a benefit balance that could not be explained. Walk the responsible people through that dependency before the next disruption. A usable result is a named substitute, a confirmed source or an earlier funding decision, with evidence the next operator can find.
Browse the Decision Guides library.
Continue with Payroll Operations & Controls.
Find practical tools in the Payroll Operations Resource Library.

About the author
Ben Scott writes and maintains payroll decision guides for founders and operators. His work focuses on execution realities and how decisions hold up under growth, complexity, and controls and documentation pressure. He works hands-on in HR and leave-management roles that intersect with payroll-adjacent workflows such as benefits coordination, cutovers, and compliance-driven process controls.


