
Leave of Absence Payroll: Coordinate Pay, Coverage and Return

Updated: 2 days ago
Before an employee leaves work, give them a usable explanation of the next paycheck, continuing coverage and any payments they will need to make directly. Then give payroll instructions that can produce that result. An approved absence can contain paid time, unpaid time and an outside benefit payment, with different effective dates for each.
Leave-of-absence payroll controls connect those facts throughout the absence and into the first returning paycheck. Keep four records aligned: the approved leave interval, the pay instruction, the coverage decision and the employee-contribution collection method. Update the affected record when circumstances change rather than expecting one “on leave” status to control them all.
This guide is for U.S. employers coordinating HR, benefits and payroll. It includes a Leave-to-Payroll Transition Sheet and fictional examples. The workflow is an operating recommendation; the applicable law, plan terms, employment agreement and approved leave determination establish the employee's rights. Have the responsible specialists identify those requirements before configuring a live case.
Contents
Establish the leave decision payroll can act on
Ask HR or the leave administrator for the approved basis, dates and working pattern. Payroll needs to know whether the employee will stop work entirely, miss particular intervals or return on a reduced schedule. An expected end date should be identified as an estimate until the authorized return instruction arrives.
The Family and Medical Leave Act, or FMLA, provides qualifying leave protections for eligible employees of covered employers. Its protections include continued group health benefits under the same conditions as continued employment and restoration rights. FMLA leave can run alongside employer-provided paid leave. Receiving pay does not, by itself, tell payroll whether an absence is protected or how much protected leave has been used.
For each case, have the leave owner identify all applicable federal, state, local, agreement and employer-policy requirements. A disability benefit approval is a payment decision; it does not establish every job-protection entitlement. Similarly, a request outside FMLA may require another leave or accommodation review. Payroll should receive the resulting instruction, including any item still awaiting a determination, instead of making a legal decision from an earnings code.
Record the employee identifier, case reference, approved start, current expected end, actual work pattern and person authorized to change those facts. Keep the original instruction when a new version arrives. A leave extended by two weeks should create a traceable revision to the affected dates and pay treatment, with a named next review, rather than silently overwriting the earlier record.
The payroll working record generally needs operational facts, not medical narratives. FMLA medical certifications and related histories have separate confidentiality requirements. Retain the decision reference in the payroll worksheet and keep those medical records in the restricted system designated for them. Limit access to the worksheet as well: pay and benefits information remains sensitive even without a diagnosis.
Give each leave interval a pay instruction
Divide the absence at the points where treatment changes. A continuous four-week leave might contain a week of approved paid time off, two weeks without employer wages and a week of salary continuation. A reduced schedule might contain worked hours and unpaid leave on the same day. Choose intervals that explain the calculation without creating a separate record for every calendar day when nothing changes.
For each interval, specify the dates or hours, employer payment source, earning code, calculation basis and next transition. Distinguish actual work, paid leave, salary continuation and an informational entry for a benefit already paid elsewhere. A code that records a third-party payment must not accidentally issue the employee that cash a second time.
Read the employer's paid-leave policy with the applicable leave rules. Under the FMLA substitution rules, qualifying accrued paid leave can run concurrently with otherwise unpaid FMLA leave, subject to the normal policy conditions. Disability-plan and workers' compensation payments have different substitution and supplementation provisions. Identify the applicable arrangement before instructing payroll to use a leave bank or top up another payment.
Keep an exhaustion trigger for paid balances. “Use PTO first” needs an available balance, an approved rate and a defined response when the balance runs out midperiod. Calculate the paid portion and remaining interval separately. Tell benefits when the reduced earnings may no longer support ordinary collection; waiting until the first zero-pay result loses useful preparation time.
For a nonexempt hourly employee, obtain the actual worked-time record as well as leave hours. Do not treat an approved absence as proof that no work occurred. Route an unexpected work event to the leave owner and wage reviewer so both the pay and leave-use records can be corrected. Preserve the actual event rather than erasing it to fit the planned absence.
Salary treatment needs its own review. The FMLA rules allow proportionate unpaid FMLA deductions for otherwise qualifying salaried exempt employees without destroying the exemption. That special rule does not authorize hourly salary deductions for every employer-policy or state-law leave. Record the supported basis and calculation for this employee; do not turn a generic unpaid-leave code into a universal salary rule.
Count protected absence separately from paid hours
An intermittent leave record should explain how much scheduled work the employee missed for the qualifying reason. A payroll record should explain what the employer paid. Those totals often differ. The difference is expected when approved paid leave replaces some or all of the missed work.
DOL's leave-counting guidance bases a partial week's FMLA usage on the employee's actual workweek. In the ordinary case, divide the qualifying absence by the hours the employee would have worked without leave. Count only the leave actually used, subject to the applicable increment and special rules. A universal forty-hour denominator will misstate usage for an employee whose normal workweek is different.
Consider a fictional employee scheduled for forty hours, paid $24 per hour for both work and approved PTO. The employee works thirty-two hours and misses eight scheduled hours for approved intermittent FMLA leave. Four of those absence hours are covered by approved PTO; the other four are unpaid. There are no other earnings or overtime complications in this example.
Worked pay: 32 hours × $24 = $768.
Paid-leave pay: 4 hours × $24 = $96.
Total employer gross pay: $864.
Scheduled time allocation: 32 worked + 4 paid leave + 4 unpaid leave = 40 hours.
FMLA usage: 8 qualifying absence hours ÷ 40 scheduled hours = one-fifth of a workweek.
Recording only the four unpaid hours as FMLA usage would understate the absence. Recording all forty scheduled hours as worked time would misdescribe the work. The employee's deduction collection then needs to be assessed against the actual payroll result, not against the normal forty-hour gross amount.
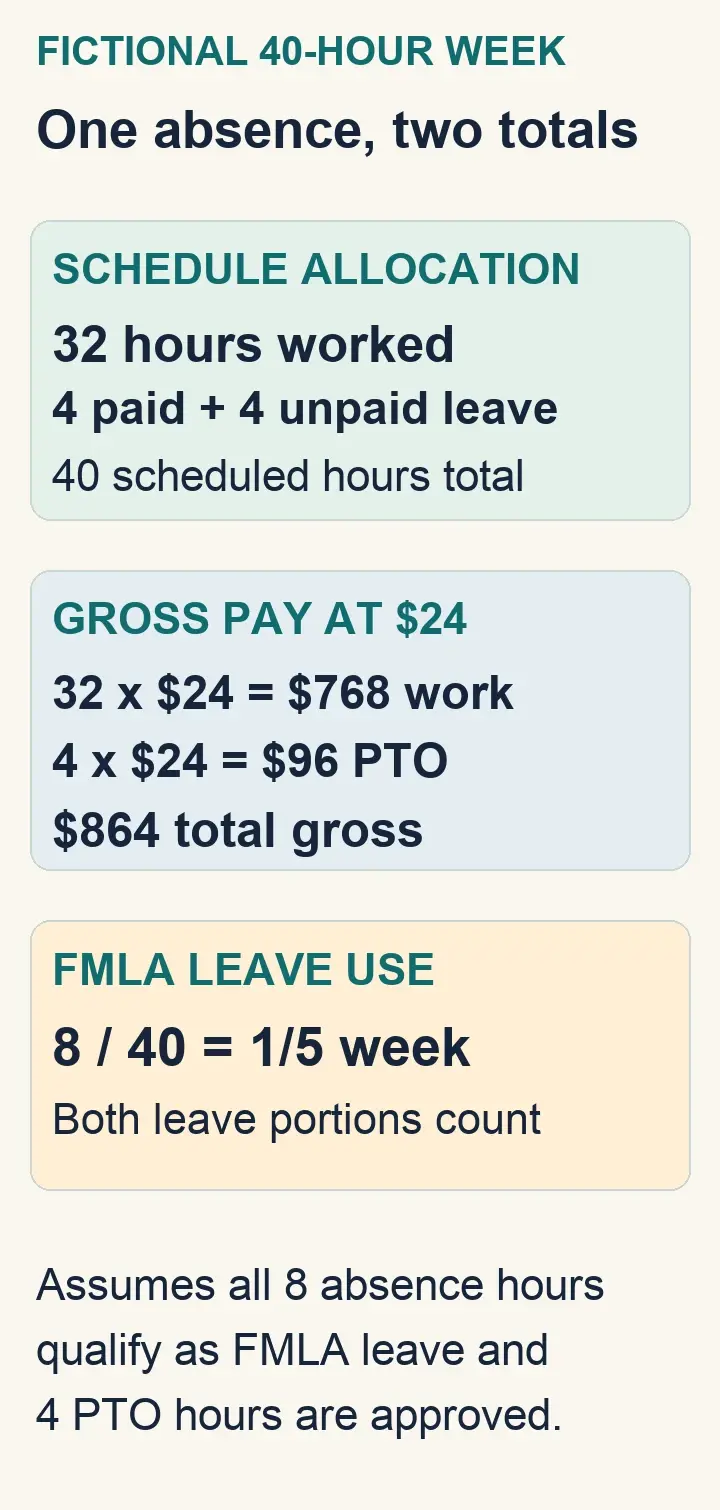
One absence produces both a pay calculation and a protected-leave calculation. The selectable calculation above states the assumptions and values.
Check holidays, fluctuating schedules and unusual shift arrangements with the leave owner instead of extending the example mechanically. DOL distinguishes holidays in full-week and partial-week FMLA absences. When a highly variable schedule prevents identifying the expected hours, the applicable averaging method also needs support. Keep the schedule evidence and approved method with the usage record.
Continue coverage through an explicit benefits decision
A zero wage payment is not a coverage termination instruction. Benefits should identify which plans continue, under what basis, for which period and at what employee contribution. Payroll then receives a collection instruction consistent with that decision. This is particularly important when an HR status field also feeds an insurer or benefits platform.
For FMLA group health coverage, the employee generally remains responsible for the normal employee share while the employer maintains coverage on the required basis. During substituted paid leave, contributions use the method normally used during paid leave. During unpaid FMLA leave, permitted payment arrangements and advance written notice become important. The payroll absence of a deduction does not show that the employee's contribution has been waived.
Ask benefits to record the plan, coverage tier, contribution amount or rate, covered period, continuation basis and communication reference. Specify which system sends any carrier transaction. An automatic inactive-employee feed should be tested against the approved coverage outcome before the leave status reaches production. Obtain the actual acceptance or coverage evidence required by that process.
Treat each benefit according to its own rules. Do not apply a medical-premium collection decision wholesale to retirement contributions, plan loans, voluntary insurance or a health flexible spending arrangement. Identify the responsible plan administrator and obtain the applicable instruction. An unreviewed payroll default can suspend an item that should continue or attempt to collect an amount that has no current basis.
If FMLA protection ends before the employee returns, ask benefits and HR for the next supported coverage and employment instructions. Other leave rights, plan terms or continuation requirements may apply. Do not let payroll infer an employment termination, a new waiting period or a coverage end merely because a counter reached its limit.
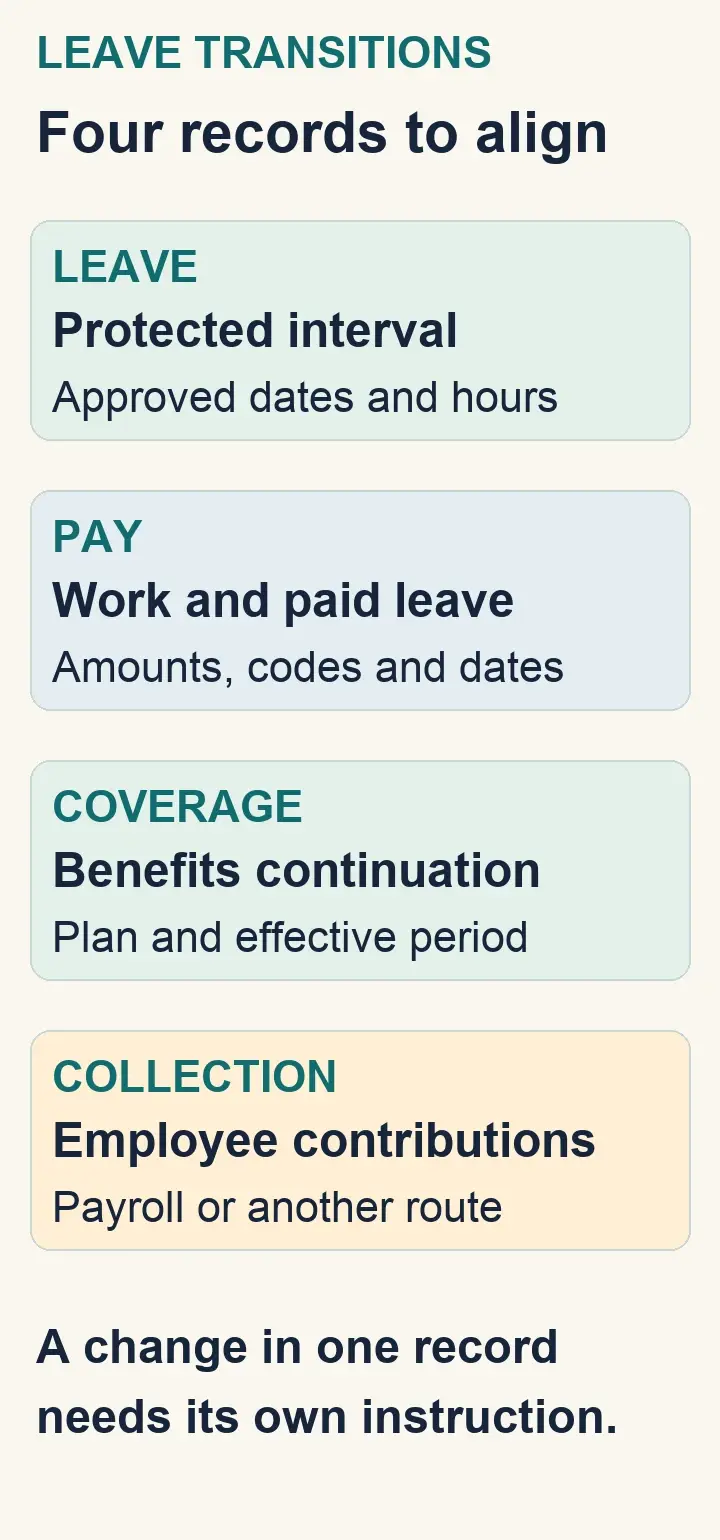
Review these four records at every change in treatment. The next sections explain how collection and return decisions connect them.
Choose a collection route before wages become insufficient
Build a separate instruction for each deduction affected by reduced or absent wages. Include the current contribution, collection route, effective pay date and treatment of any uncollected amount. Payroll needs to distinguish a deliberate suspension from an attempted deduction that could not be collected. Neither result proves the amount of a recoverable debt.
Cafeteria-plan rules describe prepay, pay-as-you-go and catch-up arrangements for unpaid FMLA leave, with conditions on the choices and their tax treatment. Prepayment cannot be mandatory. Direct pay-as-you-go contributions are generally after tax, while available taxable compensation can support permitted pretax contributions. Catch-up can be pretax or after tax under the applicable rules. Have the plan administrator approve the actual arrangement; do not label every returning deduction pretax simply because the original election was pretax.
Watch a year boundary before promising pretax prepayment for future coverage. The cafeteria-plan rules restrict deferring compensation between plan years. Also obtain specific health FSA instructions if coverage or payments change; its coverage and reimbursement mechanics should not be inferred from the medical-premium code. Record the approved treatment without trying to redesign the plan inside the payroll worksheet.
For a direct-payment route, tell the employee the amount, covered period, due date, payment method and contact for questions. Give finance a way to identify the employee and period when money arrives. A generic deposit total cannot establish which leave case has been paid. Share the receipt reference with benefits and payroll before a later recovery instruction is calculated.
For insufficient earnings, apply the supported deduction priorities, wage protections, authorizations and order or plan requirements. Record what actually collected and route the remainder to its owner. Do not create negative net pay merely to preserve the normal deduction total. A garnishment or child-support order needs its own reviewed handling and any required notice; it is not simply another voluntary premium that can be paused and doubled later.
A premium balance needs a period-by-period reconciliation before payroll recovery. Benefits confirms the employee obligation and coverage, finance confirms direct receipts or refunds, and payroll confirms deductions actually taken. Keep any disputed or unverified amount outside the approved recovery instruction until resolved. Refer the detailed calculation to the premium arrears recovery process rather than maintaining a competing debt ledger in the leave-transition sheet.
Keep outside benefits distinct from employer payroll cash
Ask who is paying each amount and when the payment actually occurred. A carrier approval, a state benefit estimate and a payment statement are different records. Use actual payer evidence for reconciliation, while clearly labeling an estimate used for planning. Identify any pending claim decision that could change a later employer instruction.
For disability-plan or workers' compensation benefits running with FMLA leave, the federal substitution rule differs from ordinary unpaid FMLA leave. Supplementation with accrued leave can be agreed where state law permits. Obtain the applicable plan, law and agreement before calculating a top-up. For a state paid-family or medical-leave program, obtain that program's own coordination rules rather than assuming the disability example applies.
Send payroll a clear cash or reporting instruction. If the employer is to pay a supplement, state the approved formula, period, payer amount used, treatment of estimates and process for a later adjustment. If the entry is reporting-only, state that no new employee payment should be generated. Test the chosen code's effect on net pay and tax bases before relying on its name.
IRS Publication 15-A distinguishes an employer's agent from a third-party payer bearing insurance risk and explains how sick-pay tax and reporting duties can be allocated. An outside payment does not automatically remove the employer from the reporting workflow. Record the agreement owner and the route for actual payment and tax statements. Use the dedicated third-party sick-pay reconciliation procedure for the detailed filing responsibilities.
If an estimated benefit differs from the actual award, compare the original employer calculation with the approved correction. Explain whether any additional wage payment or proposed recovery follows, and have the responsible reviewer confirm the permissible route and timing. Do not automatically deduct a carrier overpayment or employer estimate difference from the next paycheck without that review.
Follow one employee from paid leave into a no-wage period
Consider another fictional case. An hourly employee begins an approved continuous leave on Monday. HR has confirmed FMLA coverage and the applicable paid-leave arrangements. The employee has forty hours of approved PTO at $30 per hour for the first week, followed by two weeks without employer wages. Benefits has approved continued group health coverage and communicated the employee's contribution arrangement.
For week one, payroll receives forty PTO hours and $1,200 gross, with no worked hours in this example. The normal employee contribution for that coverage period is collected through the usual paid-leave method. The paid hours also belong in the approved FMLA usage record. They should not leave the protected-leave record empty just because the employee received a paycheck.
For the two no-wage weeks, the employer pay instruction is zero regular wages and zero PTO. Benefits continues the approved coverage. Suppose the agreed direct-payment arrangement requires $75 for each of those two coverage weeks and the employee pays $150 to the employer. Finance attributes the receipt to both weeks and gives its reference to the case owner. There is no $150 premium balance to recover again merely because payroll deductions were zero.
If only $75 arrives, the case owner identifies which period remains unpaid and asks benefits for the approved response. The worksheet records the unresolved collection item and next action. It does not instruct payroll to drop coverage, debit a future paycheck or change the employer contribution without support.
When the employee returns, current contributions and any approved recovery remain separately identifiable. The two direct-payment weeks stay in the case history, even though the payroll deduction report shows zero for them. That history lets the employee and reviewer understand why a current deduction is appropriate and why an assumed catch-up amount may be wrong.
Route missed payments and leave extensions to their owners
Set review dates while the employee is away. Check the next change in pay source, an expiring balance, a contribution due date, an outside payment statement and the expected return. Review the event that can change the instruction; avoid repeatedly asking for the same facts when the arrangement remains unchanged.
A missed health-premium payment needs benefits review before a coverage action. Under the FMLA rule, the ordinary late-payment threshold is more than thirty days, unless an established employer policy allows a longer grace period. Dropping coverage also requires the specified written notice mailed at least fifteen days before the stated cessation date. The timing, policy and reinstatement requirements must be checked together; a failed payroll deduction is not the notice process.
Send a proposed coverage change through the authorized benefits and legal review and retain its effective date and notice evidence. Payroll should not create a carrier cancellation simply to clear an unpaid deduction. If the employer maintains coverage by advancing an employee contribution, give the recovery reviewer the actual coverage and advance evidence instead of assuming all missed amounts have the same treatment.
An extended absence also needs a new legal and operational decision. EEOC guidance explains that additional leave may be a reasonable accommodation under the Americans with Disabilities Act, or ADA, even after ordinary policy or FMLA leave is exhausted, absent undue hardship. Route the request to the accommodation owner. Do not automatically terminate employment or reactivate pay when an expected date passes.
For a change received after payroll cutoff, identify which employee result and payment date are affected. Use the authorized exception route to determine the correction while preserving wages due and applicable deadlines. Keep the original and revised instructions, who approved them and the actual result. The next scheduled run is a processing option to evaluate, not automatic permission to defer an amount owed.
Prepare the actual return and inspect the first paycheck
Obtain the confirmed return date and working pattern. HR should establish any required clearance and accommodation decisions through the appropriate process. EEOC guidance cautions against requiring an employee to be fully healed without restrictions when they can work with a reasonable accommodation, subject to the applicable standards. Payroll should receive the approved schedule and pay instruction, not decide medical readiness.
For an FMLA return, use the required same or equivalent pay and benefits treatment. Check unconditional increases that occurred during leave and the relevant premium-pay treatment. Copying the old salary or hourly rate without reviewing intervening changes can produce the wrong returning amount. Have HR identify the supported returning terms before payroll changes the effective record.
Give payroll separate instructions to end the leave earnings arrangement, resume work pay, restart current deductions and apply any approved recovery. Date each instruction against the actual period it covers. A reduced-schedule return may still contain protected absence, so restoring all scheduled hours as worked time can be wrong even though the employee is back at the workplace.
Preview the employee's first result using the approved schedule. Compare worked hours, paid leave, rates, salary adjustments, current contributions, any separate recovery and net pay. Confirm that temporary direct billing and payroll collection do not charge the same period twice. Compare the benefits and carrier outcome with the returning coverage decision as well; payroll status alone cannot establish it. If FMLA group health coverage lapsed for missed contributions, the return still carries restoration requirements. Benefits should confirm equivalent coverage and the required reinstatement without imposing a new qualification or open-enrollment wait.
Keep an unresolved benefit balance or missing internal approval on its own escalation path. Do not let an internal return checklist delay earned wages. The case owner should arrange timely processing of supported pay while the responsible reviewer resolves the remaining issue. After payment, verify what actually posted and reached the employee, then record any correction still due.
Leave-to-Payroll Transition Sheet
Use one case header, then repeat the interval and contribution sections whenever treatment changes. Complete the return section against the actual first payroll result. Store references to approved records rather than copying medical details or retaining unnecessary identity documents. Blank entries mean a decision is still needed; they are not authority to apply a default.
Case and authority
Employee and leave case reference: __________
Leave owner and payroll contact: __________
Approved leave basis and decision reference: __________
Approved start, expected end and next review date: __________
Normal schedule and approved absence pattern: __________
Keep the expected return distinct from a confirmed return. Refer medical evidence to its restricted record.
Pay interval, repeated for each change
Interval start and end, with affected pay date: __________
Actual worked hours and source record: __________
Paid-leave hours or salary treatment, with authority: __________
Employer amount, calculation and earning code: __________
Outside payer evidence and cash or reporting-only treatment: __________
Next transition trigger, owner and due date: __________
Reconcile the schedule, absence use and pay calculation separately. Identify estimates and the event that replaces them with actual figures.
Coverage and collection, repeated for each affected item
Plan or deduction, coverage period and employee share: __________
Continuation or change decision and effective date: __________
Approved collection route, tax treatment and authority: __________
Amount actually collected, method and receipt reference: __________
Uncollected or disputed amount, reviewer and next action: __________
A missed deduction does not establish a debt or authorize a coverage cancellation. Refer premium recovery to the reconciled period history.
Return and first result
Confirmed return date and approved working pattern: __________
Returning pay terms and intervening changes: __________
Current deductions and separate approved recovery instruction: __________
Direct billing or temporary code stop dates: __________
First payroll and coverage results, with evidence: __________
Remaining correction, accountable owner and deadline: __________
Close the transition only after its results are checked. Continue unresolved work without delaying supported wages.
Make the workflow usable for employees and reviewers
Give the employee a short, concrete schedule at leave start: expected employer pay, known outside benefit steps, continuing coverage, contribution method and whom to contact if a payment differs. Identify estimates. Explain how a changed return date or award can alter the next instruction without promising a net amount the team has not calculated.
Before the return paycheck, show current contributions and any approved recovery as separate amounts with the relevant periods. If the employee reports a direct payment, investigate it against finance's receipt records before collecting the same contribution again. Tell the employee what has been confirmed, what remains under review and when the next response is due.
Review the worksheet against actual payroll and benefits evidence before closing the case. Retain the approved versions, notices, receipt references, exception decisions and first-return result under the applicable retention and access rules. The useful record is the explanation of what changed, which authority supported it and whether the employee received the intended outcome.
For a small employer, the same person may coordinate multiple steps. Keep the decisions distinct and arrange a second review for consequential pay, coverage or recovery changes where staffing permits. With an outside leave administrator or payroll service, name the employer contact who can resolve a disagreement and specify how accepted instructions and rejected records become visible. Outsourcing a handoff does not make an unacknowledged change complete.
Revisit the process when a plan changes, an interface is replaced or a recurring error appears. Use a known intermittent case, a paid-balance exhaustion, a direct premium payment and a reduced-schedule return as demonstration cases. Compare expected records and amounts with the actual configured results. These are checks to perform in your environment, not claims that a product has already passed them.
More payroll guides and tools:

About the author
Ben Scott writes and maintains payroll decision guides for founders and operators. His work focuses on execution realities and how decisions hold up under growth, complexity, and controls and documentation pressure. He works hands-on in HR and leave-management roles that intersect with payroll-adjacent workflows such as benefits coordination, cutovers, and compliance-driven process controls.


