1099 Contractor Payments: Route Fees, Expenses and Tax Reporting

Updated: 2 days ago

A manager sends AP an invoice for $2,400 and asks for payment today. The fee is $1,800, the contractor bought $360 of materials, and another $240 is travel. Payroll has also received a request to pay the same person. A single “contractor” flag cannot tell either team which amounts to release, what belongs in the reporting total, or whether another payment is already in motion.
For 1099 contractor payments, decide the relationship, the payment components, the processing route and the reporting treatment separately. AP may send the money while a payroll provider prepares the information return. An expense system may collect receipts while payroll handles a taxable employee allowance. Assign those responsibilities explicitly.
U.S. payroll, AP and finance teams can use the worked invoice and Payment Component Register to keep each domestic service-payment amount attached to its treatment and settlement record. Foreign payees, specialized industries and unresolved worker status need the appropriate tax or legal reviewer before a standard domestic workflow is applied.
Make the payment component the unit of review
Start with the obligation the business actually owes. Record the contracting employer or customer entity, the payee, the services or expense, the relevant dates and the source request. If a person appears in both the vendor master and the employee record, use those records to investigate the relationship and payment purpose. Two system records do not authorize two payments.
Break a mixed request into components that can receive different decisions. A service fee, materials incidental to that service, travel supported by an expense accounting and an employee bonus need distinct treatment even when someone enters them as one invoice total. Keep the original document and give each component a stable identifier.
For each component, identify the business approver, the team that will process the payment, the person responsible for tax treatment and the person who will reconcile settlement. A small team can combine roles, but the responsibilities still need names. Where practical, have someone other than the preparer review changes to payee details and the release instruction.
Use three separate amounts in the working record: the approved obligation, the cash actually disbursed and the amount assigned to a reporting category. They may differ for legitimate reasons, such as withholding or an adequately accounted expense. Explain each difference through the underlying transaction. A total that happens to agree does not establish that every component was treated correctly.
The processing route is an operational choice about systems and owners. It does not by itself determine whether a person is an employee, whether an amount is taxable, or which information return applies. A provider's contractor-payment feature can be useful, but its name is not a classification opinion or evidence that all relevant reporting is configured.
Confirm the relationship before choosing a payment code
The IRS worker-status guidance calls for examining the relationship and the evidence of control and independence. A contract, an invoice or a worker's preference cannot replace that assessment. Obtain the approved determination and its scope rather than asking the payment preparer to infer status from a dropdown.
Record which entity engaged the worker and which services the determination covers. Someone's current employee status does not automatically answer how an earlier engagement should be treated. A new assignment, a different employer entity or materially changed working arrangements may require another review. Preserve the effective dates and the facts supporting the decision.
Federal tax, federal wage-and-hour and state requirements need their own analysis. For example, New Jersey describes its statutory ABC test, which illustrates why a national payment procedure cannot rely exclusively on a federal tax determination. The routing register should reference the relevant review, not attempt to become a fifty-state classification calculator.
Give HR, legal or the designated classification specialist a clear escalation when the evidence is unresolved. State exactly what is missing: the entity, service period, engagement facts or applicable jurisdiction. Record the payment deadline and any employee wage obligations separately. An internal routing hold does not authorize missing a legally required wage payment or withholding undisputed wages.
A useful handoff might say, “The vendor record covers a completed consulting engagement through September. The October request covers duties performed after employment began. Payroll and the classification owner must resolve that component before AP uses the former vendor code.” That instruction identifies an actual question and prevents an old record from silently deciding a new payment.
If the relationship has already been competently reviewed, AP need not repeat the entire legal analysis for every routine invoice. It should confirm that the current request still falls within the reviewed arrangement and route meaningful changes back to the owner. A checklist can support that boundary without promising that completing it establishes lawful contractor status.
Separate a service fee from an expense claim
Ask what the payer is buying and why the expense was incurred. A contractor's invoice can include both labor and items used to perform the work. Labeling an item “reimbursement” does not automatically remove it from nonemployee compensation. The Form 1099-NEC instructions include incidental parts and materials in payments for services and address travel reimbursements that were not accounted for to the payer.
Request a breakdown when the invoice combines different items. Keep the supplier's original description, the business purpose, the amount and the documents used to approve it. Do not rewrite the invoice merely to create a preferred tax result. If evidence is incomplete, show the unresolved amount and the decision owner rather than entering a final exclusion that nobody has supported.
Contractor travel and similar expense arrangements require particular care. Publication 463's independent-contractor rules explain accounting to the client and information-return treatment for adequately accounted reimbursed amounts. Apply those rules to the expense and arrangement actually under review. A receipt attached to an invoice is useful evidence, but it does not establish a blanket exclusion for every expense, material or allowance.
Keep employee reimbursements in a separate analysis. An employee accountable-plan arrangement requires a business connection, adequate accounting within a reasonable period and return of excess amounts within a reasonable period. If an arrangement or payment fails the applicable requirements, payroll may need to treat amounts as wages. IRS Publication 15 explains employer treatment of reimbursement arrangements and taxable allowances.
The expense tool's approval is often a business-spend approval. Confirm who also decides payroll tax treatment. A manager can agree that an employee needed equipment without resolving whether a flat allowance qualifies for exclusion. Likewise, the fact that an expense is reimbursable under a contract does not settle the contractor's information-reporting treatment.
For an employee advance, track the amount advanced, the supported business expense and any excess still to be returned or otherwise treated. Attach the reconciliation to the original advance identifier. Avoid issuing a second reimbursement for an expense already covered by that advance. If only part of an arrangement fails its requirements, send the specific amount and reason to the tax reviewer rather than recoding the entire employee expense population.
Choose a due date for obtaining missing documentation and a named follow-up owner. Keep the supplier or employee informed about the actual unresolved item. Do not describe a payment as approved when only the business purpose has been accepted and its amount or treatment remains open.
Give processing and reporting different owners
Employee wages and taxable employee compensation require payroll treatment, even when an AP platform or a bank portal happens to send the cash. The IRS's forms guidance distinguishes employee compensation reported on Form W-2 from reportable nonemployee service payments. Routing an employee payment through AP does not turn wages into a vendor expense.
For a supported independent-contractor service payment, AP or a dedicated contractor-payment workflow can own the disbursement. Specify who creates the vendor liability, who approves it, who submits the payment and who imports its reporting data. A payroll provider may prepare the 1099 while AP retains the actual payment record. That arrangement needs a documented feed and responsibility for exceptions.
For a supported employee expense repayment, an expense platform, AP or payroll may process the cash according to the employer's approved design. The important controls are correct treatment, a link to the expense evidence and protection against duplicate reimbursement. Employee status alone does not dictate the software module used to repay a supported expense.
Assign the reporting owner to every route, including a route expected to generate no employer-issued information return. “The platform handles it” needs a specific entity, service, data source and confirmation path. Record who checks whether the provider files, who handles rejected records and who answers payee questions after the engagement or subscription ends.
Where two providers cover one calendar year, define the handoff before loading totals. Identify the payer entity and payee identity, the covered payment dates, the included sources and the party filing each return. A vendor opening balance can be an accounting balance, a prior-payment total or both. An unexplained import can duplicate reporting even when no second cash payment occurs.
Build the provider demonstration around harmless sample data with separate payment and reporting instructions. Include one service invoice paid through AP, one supported expense component, one payment settled by card and one returned payment. The useful result is an explanation of which owner and source drive each outcome. A polished payment screen alone does not establish the reporting process.
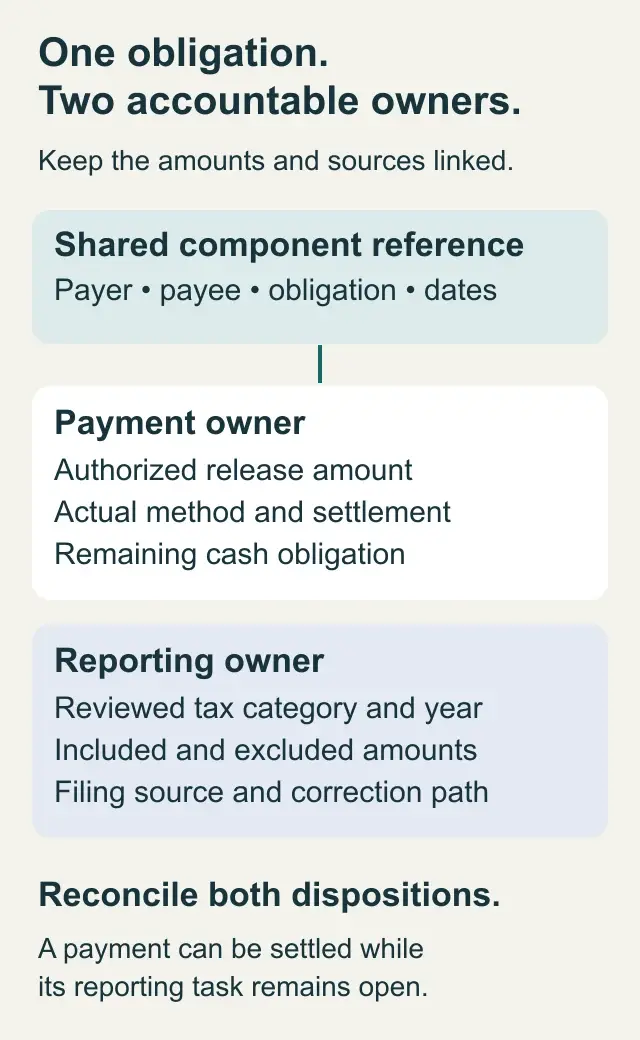
The payment preparer and reporting owner use the same obligation reference while retaining their different amounts, sources and responsibilities.
Collect payee details without exposing them in the register
For a U.S. independent contractor, use the appropriate approved tax-document process to obtain the payee's name and taxpayer identification details. The IRS explains Form W-9 collection after contractor status has been determined. Store the sensitive document in the restricted system and reference its location in the working register.
Keep legal name, business name and tax classification aligned with the actual form instructions. Do not decide reporting solely from an “LLC” suffix or a familiar trading name. A reporting exception for a corporation is not universal; the current instructions include exceptions to that exception, including certain attorney payments. Send those cases to the tax owner rather than relying on a single vendor-master flag.
Foreign persons and cross-border services should leave this standard domestic route for appropriate documentation, sourcing and withholding review. Do not demand a Form W-9 from every payee worldwide or assume that a U.S. bank account establishes U.S. tax status. Identify the questions that need resolution without publishing the payee's tax identifiers in a broadly shared worksheet.
Missing or incorrect taxpayer information can create a withholding obligation, not simply a reminder to ask again later. IRS backup-withholding guidance identifies situations requiring withholding at the current 24 percent rate. Have the responsible tax person determine the applicable trigger, exemptions, timing and remittance process; do not configure withholding from this general register alone.
Maintain a separate check for changes to banking instructions. Use the company's established independent verification procedure and retain the authorized change reference. A revised invoice email should not, by itself, replace a bank destination already approved in the vendor master. Review vendor-bank editing and payment-release permissions together, and document who independently checks a payment after its destination changes.
The operational record should show that the required checks were completed, by whom and when. Use restricted references instead of copying a full TIN, account number, tax form or sensitive email into the register. An approver usually needs to know that the evidence exists and applies to this payee, not to receive another uncontrolled copy of it.
Read the settlement record before setting the reporting flag
Record how each payment was actually settled. Direct check or ordinary bank transfer, payment card and a qualifying third-party network transaction can have different information-reporting consequences. An electronic payment is not automatically a Form 1099-K transaction. Obtain the processor's relevant transaction classification and settlement record rather than inferring treatment from a brand name or the fact that money moved online.
The Form 1099-K instructions explain the coordination with other reporting rules for covered payment-card and third-party-network transactions. Keep qualifying covered transactions out of the payer's duplicate Form 1099-NEC population. Do not assume the absence of a received Form 1099-K proves that the payer should include the payment on a different form.
A provider might initiate an ordinary bank transfer on behalf of the business and separately offer filing services. Another service might settle a covered network transaction. Ask the reporting owner to document which arrangement applies to the actual payment. The processor’s settlement report must identify the transaction arrangement; a generic “paid” status leaves the reporting category unresolved.
Preserve gross amount, fees, withheld amounts, net cash, payment date and any return or refund as separate fields in the underlying system. For example, exporting net bank receipts can conceal a processor fee deducted from the contractor’s deposit. That fee needs its own treatment instead of silently reducing the reporting amount. The reviewer needs the relevant gross basis and an explanation of deductions, not an unexplained spreadsheet adjustment.
Use a stable payment reference to connect the approved component to the settlement record and the reporting feed. If an invoice is paid in installments or through more than one method, retain the allocations. A single vendor-level “exclude from 1099” checkbox cannot accurately describe a year containing both covered card payments and directly paid reportable service fees.
When the settlement status is unknown, give someone the task of determining whether money already left the account. Do not recreate the invoice in payroll simply because AP's screen has not updated. Keep the original instruction visible until its disposition is known, then authorize a replacement only for the remaining obligation.
One $2,400 payment, a $2,160 reporting amount
This fictional example concerns a domestic sole proprietor whose service relationship has already been appropriately reviewed. The business owes a consulting fee of $1,800, materials costing $360 that were incidental to delivering that service, and $240 of travel incurred for the client. The total invoice is $2,400. It is paid directly by ordinary ACH, with no applicable card or third-party-network settlement exclusion.
The service owner confirms the work and the materials. The tax reviewer determines that the materials belong with the service fee for this example. The contractor provides the expense accounting required for the travel arrangement, and the reviewer confirms that the $240 falls within the applicable adequately accounted reimbursement treatment. Those are explicit assumptions of the example, not conclusions established by the word “travel” on an invoice.
The component record reads:
Consulting service: $1,800, payable through AP and included in the reviewed nonemployee-compensation population.
Incidental materials: $360, payable through AP and included with the service compensation.
Adequately accounted travel: $240, payable through AP and excluded from that information-return population under the reviewed arrangement.
The cash obligation is $1,800 + $360 + $240 = $2,400. The example's nonemployee-compensation amount is $1,800 + $360 = $2,160. The difference is the supported $240 travel component. AP releases one $2,400 payment and attaches the settlement reference to all three component records.
For payments in calendar year 2026, the ordinary federal Form 1099-NEC service-payment threshold is $2,000 in aggregate to a payee for the year, subject to the applicable conditions and exceptions. Current IRS information-return instructions also require reporting when federal income tax was withheld under backup-withholding rules regardless of the payment amount. The threshold does not decide worker status or whether income is taxable.
In this example, the reviewed $2,160 exceeds that 2026 threshold. Excluding both materials and travel merely because they were separately itemized would leave $1,800 and produce the wrong reporting decision. Including everything automatically would ignore the supported treatment of the travel. The component breakdown makes the actual reasoning inspectable.
If the travel accounting is missing, keep that conclusion unresolved and obtain the tax review appropriate to the actual facts. Do not copy the example's $240 exclusion into the real payment. Similarly, if the vendor is a corporation, the payment uses a covered card transaction or the client has other payments to the same payee, the reviewer must revisit the reporting conclusion and annual totals.
Now suppose payroll also received the original invoice. Before it creates a contractor payment, the shared register shows AP's $2,400 settlement reference and a zero remaining cash obligation for these three components. The payroll team can supply the authorized reporting service without paying the same invoice again. It must still receive the correct $2,160 reporting basis and the supporting allocation.
Retain the reviewer, source and assumptions with the actual record so another person can reproduce the result without guessing which parts of the illustration apply.
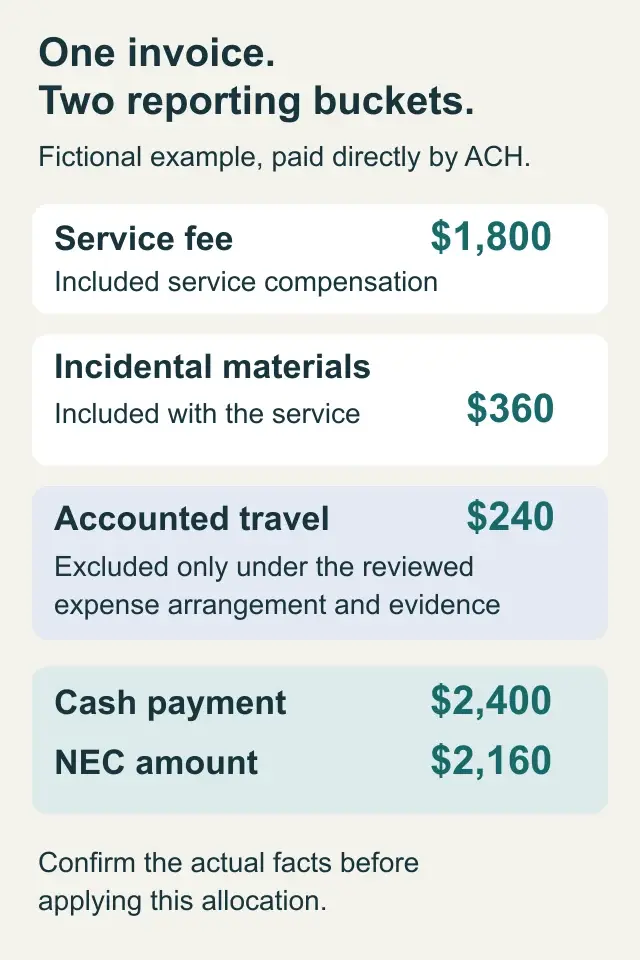
The fictional invoice produces one $2,400 cash payment and a reviewed $2,160 nonemployee-compensation amount.
Payment Component Register: one record for each treatment
Copy the four sections below for each component that needs a distinct treatment or release decision. A single invoice may therefore have several records connected to the same settlement. Keep sensitive documents in their approved restricted location and use references here.
A. Payee and obligation
Component identifier and parent request reference: ____.
Payer entity and approved payee-record reference: ____.
Service or expense dates and business purpose: ____.
Worker-status review reference, scope and owner: ____.
Approved component amount and currency: ____.
A record should describe an identifiable obligation. If the request is a duplicate, disputed or outside the reviewed engagement, state that before assigning a release instruction.
B. Treatment and responsibility
Component description and supporting document reference: ____.
Tax or reimbursement treatment and reviewer: ____.
Processing system and payment preparer: ____.
Reporting owner, payer identity and intended category: ____.
Missing evidence, responsible person and decision date: ____.
Separate business approval from tax treatment. An unresolved amount keeps an explicit owner and next decision; a blank field is not evidence of an approved exclusion.
C. Release and actual settlement
Approved release amount, approver and release date: ____.
Destination-verification reference and authorized payee: ____.
Payment method and covered-transaction review: ____.
Submission reference and current settlement state: ____.
Settled gross, deductions and net amounts with dates: ____.
Use the actual settlement source. If several components share one payment, record their allocations and check that they total the payment instruction without issuing each component again.
D. Reporting and closure
Included reporting amount, source year and rule reference: ____.
Excluded amount, reason and supporting review: ____.
Linked information return, reporting export or filing-owner reference: ____.
Remaining cash obligation, returned-payment or correction reference: ____.
Reconciler, unresolved task and final disposition date: ____.
Close a record only when its cash and reporting dispositions are both accounted for, or clearly describe the outstanding work. “Paid” may close the disbursement while a reporting-data issue remains open.
Use a common release queue across AP and payroll
A shared queue can be a controlled report rather than another application. Give it one owner and define which systems feed it. Include AP invoices, contractor-payment tools, payroll special runs, employee expenses and manual bank instructions that could pay the same obligation. The queue should expose overlap before release, not merely discover duplicate cash at close.
Use the component and parent-request identifiers as the primary match. Supplement them with payer, payee, amount, service period and invoice number. Differences in spelling or invoice formatting should prompt investigation rather than create a new obligation automatically. A match is a reason to review the records, not proof that every recurring invoice is a duplicate.
Choose explicit states such as awaiting treatment, ready for approval, submitted, settled, returned and cancelled. Define the evidence that moves an item between states. Assign a person to submissions whose outcome is unknown, especially around cutoffs when a second team may try to help. Avoid a generic “complete” flag that conceals whether it means approved, transmitted or actually settled.
Limit release authority to the authorized queue and amounts. If payroll is preparing a tax record for an AP-paid invoice, mark that job as reporting only and confirm it cannot also release cash. If the provider does not support that separation reliably, choose another documented handoff rather than relying on a memo field that a later operator may miss.
Urgency should change the escalation and the time available for review. It should not erase the payer, payee, amount, deadline or settlement questions. The approving owner should decide the lawful and contractually appropriate path with the relevant specialists. Keep wage-payment deadlines visible when a supposedly vendor-related request may actually involve an employee obligation.
At the end of the payment cycle, compare approved obligations with submitted instructions and settled cash. Investigate missing submissions, duplicates, returns and excess amounts. Also compare the reporting feed with the components it should contain. A paid-invoice report and a tax export answer different questions and should remain linked through a common reference.
Repair a misroute without creating a second payment
First establish what happened to the original instruction. Identify the employer or payer entity, component, system, release reference, bank outcome and tax data already created. If cash has settled, the corrective task may be an accounting or reporting adjustment rather than another payment. If the instruction was cancelled or returned, establish the remaining obligation before arranging a replacement.
For employee compensation mistakenly paid through AP, involve payroll and the tax reviewer promptly. They need to address wage reporting, withholding, deposits and any corrections under the applicable rules. Do not simply delete the AP record, add a payroll earning and send the same gross amount again. Preserve the original cash movement and determine the employee's correct treatment and remaining entitlement.
For a contractor payment accidentally loaded as wages, verify the underlying classification and reporting decisions before removing payroll amounts. The original treatment may reveal a classification question rather than a software entry mistake. Appropriate specialists should decide which returns and records need correction, the affected periods and how to communicate with the payee.
For duplicated expense repayment, identify whether an advance, corporate-card charge or earlier reimbursement already covered the same expense. Any recovery or offset needs the applicable policy and legal review, particularly where employee wages could be affected. An internal desire to restore the ledger balance does not by itself authorize a deduction from pay.
Keep the original record, the approved correction and the resulting outcome connected. Record whether cash, accounting, tax reporting or several of those changed. Retain the old and new references rather than overwriting the source in a way that makes the first release disappear. Check the revised feed so a reversed transaction does not remain in an annual report while the replacement is added again.
A correction should also remove the condition that caused the misroute. Examples include a duplicate vendor and employee record without a cross-reference, an undocumented reporting-only import, or a processor category that was inferred from its brand. Assign a specific change and review it on the next relevant payment, without representing that one successful case proves every route is safe.
Assemble the payer’s annual totals from every payment source
Start with all payment sources for each payer entity and calendar year. Include the systems no longer used, manual payments and records held by a prior provider. Reconcile payer and payee identities before adding amounts. Two names for one payee can fragment a threshold check; one shared display name can also conceal two different legal payees.
Separate directly paid service compensation, supported exclusions and covered card or network transactions using the approved component records. Track returns, refunds, voids and corrections with their dates and source references. The reporting owner must determine the appropriate treatment for the actual year; avoid netting unlike transactions merely to force the annual total to match a bank report.
Use the current payment-year rules. The 2026 $2,000 ordinary service-payment threshold should not be copied backward into a 2025 review or assumed to be the unchanged amount in later years. Publication 1099 and the applicable form instructions supply the general reporting framework, including corrections, deadlines and electronic-filing requirements. State reporting can require a separate review.
Before the filing owner releases an export, compare a sample of records back to the approved component and its actual settlement. Include an unusual expense, an installment, a covered card transaction and a corrected item. Record the sample boundary and the errors found. Sampling can test the handoff; it does not establish that unexamined records are correct.
Agree how rejected filings, corrected payee details and post-filing discoveries return to the responsible team. Preserve what was actually filed, the relevant acknowledgments and the correction history. Give the payee a clear contact for questions about amounts without promising that a filing acknowledgment settles classification or the payee's own tax liability.
The durable handoff is a reconciliation another person can repeat: approved component, actual cash result, reporting amount and any unresolved difference. Use that record to decide whether the route is ready for the next cycle or whether a specific owner must resolve a gap first.
Questions that change the route
Can a payroll provider pay a contractor?
It can be the chosen processing service if the arrangement and configuration support the required contractor payment, reporting and evidence. Confirm the underlying classification separately, identify who files and prevent a reporting-only import from also sending cash. Require a demonstration of the proposed payment and reporting configuration.
Does putting a payment through AP avoid payroll taxes?
The software route does not change the nature of employee wages. Payroll and the tax reviewer must address compensation according to the applicable rules even if another system disbursed the money. Correct the cash, accounting and reporting records together rather than treating the vendor code as the conclusion.
Is every contractor expense repayment excluded from Form 1099-NEC?
No. Distinguish incidental materials, allowances and adequately accounted expenses under the rules applicable to the arrangement. Obtain a supported treatment for the specific component. Separately stating an amount on an invoice is not enough to establish an exclusion.
Should a card-paid invoice also enter the payer's 1099-NEC total?
For a covered payment-card or third-party-network transaction, the reporting coordination rules apply. Have the reporting owner confirm the actual settlement category and prevent duplicate payer reporting. Ordinary electronic bank transfers should not be excluded merely because a payment platform initiated them.
What if AP and payroll both received the request?
Check the common obligation reference and original settlement state before either team creates another release. One team may own payment and another reporting. Make that division explicit, including the amount and evidence each team receives, so “please process” cannot mean two cash instructions.
Continue with Payroll Operations & Controls. Explore the full Decision Guides library.

About the author
Ben Scott writes and maintains payroll decision guides for founders and operators. His work focuses on execution realities and how decisions hold up under growth, complexity, and controls and documentation pressure. He works hands-on in HR and leave-management roles that intersect with payroll-adjacent workflows such as benefits coordination, cutovers, and compliance-driven process controls.