
Payroll vs Benefits Administration: Who Owns the Next Step?

Updated: 2 days ago

An employee receives confirmation that family medical coverage has been approved. The next paycheck still contains the old employee-only deduction. Benefits sees a completed enrollment; payroll sees an unchanged instruction. The employee needs someone to explain the coverage, the missing collection and the next paycheck without sending them between departments.
After enrollment, benefits administration should establish the authorized coverage and election facts. Payroll should apply the approved pay instruction and verify its paycheck result. A named event coordinator should follow the work until the affected coverage, payroll and employee communication steps have evidence of completion. Those responsibilities can sit with different people or with one small team, but they need separate decisions and records.
This guide helps U.S. employers assign that continuing work for health and welfare benefits. It concentrates on live elections, deductions, leave, terminations and correction handoffs. Retirement-plan contribution remittance, claims adjudication and plan-specific legal calendars need their own procedures. The examples are fictional, and the proposed ticket is an operating aid rather than a government form or a substitute for the plan documents.
Contents
Assign decisions, execution and follow-through
Start by naming the person authorized to decide a question and the person expected to carry out the resulting instruction. A benefits analyst may review election evidence, an authorized plan representative may decide an unusual eligibility question, and a payroll specialist may schedule the resulting deduction. Job titles alone do not establish those decision rights.
Benefits administration commonly coordinates eligibility, elections, contribution schedules and carrier or third-party administrator records. Payroll manages deduction codes, pay-run scheduling, tax configuration and the amounts actually processed. HR or leave administration may supply the employment or absence facts. Finance may own premium payment and liability reconciliation. Write down which of those functions your organization assigns internally and which services an agreement actually delegates.
Give each event one coordinator who remains responsible for its next action and escalation. This person does not gain authority to approve every underlying decision. They obtain the missing approval, require an accepted handoff and keep the employee's question from disappearing while specialists work. If the coordinator changes, the replacement should acknowledge the open tasks and due dates.
For a family-coverage change, the benefits decision owner might authorize the coverage tier and start date. Payroll accepts a specified deduction amount and first check date. A carrier liaison confirms the membership update. The coordinator can close the event after the required evidence arrives or document which task remains open. A successful payroll change cannot stand in for a missing coverage confirmation.
Keep operational coordination distinct from legal plan administration. Calling someone the ticket owner does not appoint that person the plan administrator or change responsibilities established by law, the plan or a service agreement. When a dispute requires a plan interpretation, route it to the authorized decision maker and preserve that decision with the instruction.
Use six dates instead of one effective-date field
A benefit event can have several legitimate dates. A birth, an employee's request, the coverage start, an approved election, a payroll change and the paycheck collecting the contribution may occur on different days. Record each date that matters to the event rather than letting one software field silently represent them all.
The useful date set is the event date, request-received date, coverage effective date, approved election or contribution effective date, first affected pay date and next required notice or response deadline. Add a coverage end date when applicable. Identify the document or authorized decision supporting each value.
An internal payroll cutoff determines which processing route is available. It does not by itself determine whether an employee has a timely enrollment request or a coverage right. The coverage decision owner must establish the applicable enrollment rules, while payroll states what can reach the scheduled check and what needs a separately approved correction.
Federal special enrollment rules give certain employees and dependents rights after specified events. DOL explains that marriage, birth, adoption and placement for adoption can create special enrollment rights, with timing and coverage-start requirements that differ by event. Confirm the applicable rule and plan procedure instead of applying the next payroll date to every enrollment.
Use an internal due date early enough for the responsible person to meet the real external deadline. Label it as an internal control date. A target such as Tuesday noon should never look like a universal legal deadline or permission to postpone a required notice until the next payroll cycle.
Turn an approved election into an accepted pay instruction
An enrollment screenshot rarely provides everything payroll needs. The handoff should identify the employee and employing entity, benefit and deduction code, coverage tier, approved employee contribution, calculation basis, tax treatment, start or stop date, first affected check and any separate correction. Include the election version and approving owner so payroll can distinguish a new instruction from a duplicate.
State whether the amount is monthly, annual, per check or calculated by another approved method. A $200 monthly employee contribution does not mean $200 on every paycheck. A schedule using 24 collection checks would collect $100 on each of those checks if the full-year obligation is $2,400. A schedule using 26 checks needs its own allocation and rounding rule. The plan and approved collection arrangement determine the schedule.
Keep regular collection and prior-period corrections in separate instruction lines. A recurring amount can remain correct even when two earlier checks missed it. Replacing the recurring value with the total catch-up amount could make an intended one-time adjustment repeat indefinitely.
Pretax status also needs an authorized basis. IRS describes a cafeteria plan as a written plan with requirements for eligibility and elections. A label such as Medical PreTax in payroll does not establish that the employee's election and benefit meet those requirements. Payroll should have the approved treatment and consult the employer's tax or benefits adviser when an exception falls outside the established setup.
Require the receiving owner to accept or reject the instruction before its processing deadline. Acceptance should say which check will reflect it, what amount is expected and whether a separate step is still unresolved. Rejection should identify the missing fact or conflict and the person who must resolve it. A file-upload receipt or an unanswered email is evidence of transmission, not acceptance of the work.
During the first affected run, payroll compares the authorized instruction with the employee-level preview and final result. Check both the recurring amount and any one-time adjustment. A control total can detect a broad discrepancy, but offsetting errors between employees can leave the total unchanged. Keep the employee-level evidence needed for the event's conclusion.
Treat carrier acceptance as its own outcome
The benefits system, payroll and the carrier or administrator can describe different parts of the same event. An approved election shows what the employer authorized. A payroll record shows what was collected. A carrier confirmation or appropriate administrator record supports the coverage state. None automatically proves the other two.
Name the person who reviews rejected membership records and obtains a usable response. Record the affected employee, plan, coverage period and specific rejection rather than attaching a broad feed-failed status to every event in the batch. Keep successful records distinguishable from the rejected population.
If coverage cannot be confirmed, benefits should promptly investigate the employee impact and establish the appropriate escalation. Payroll should not assume that stopping a deduction resolves an enrollment dispute, or continue collecting without asking the authorized owner how the unresolved coverage affects collection. Document the approved temporary treatment and its review date.
Finance's premium invoice may provide another check, but an invoice total is not a substitute for confirming a disputed employee's membership. Match the relevant population, benefit and coverage period before interpreting differences between billed premiums and payroll collections. Employer contributions, collection schedules and timing can explain legitimate differences that should not be forced to zero.

A benefit event needs evidence from each affected destination. A successful deduction does not establish active coverage.
Route live events by the action still missing
A new enrollment or coverage-tier change
Benefits confirms the eligible person, election, applicable coverage date and employee contribution. Payroll translates the approved amount into the established collection schedule and verifies the first affected check. The carrier liaison follows membership acceptance. The coordinator explains any gap between the coverage date and collection date to the employee.
A midyear election request
Send the request to the authorized benefits decision owner before changing pay. Federal cafeteria-plan regulations permit specified election changes and do not require a cafeteria plan to adopt every permitted change. Special enrollment rights and the tax election rules also need to be considered separately. A manager's approval or a software menu option alone is not the basis for a pretax change.
Have benefits state the approved action and its supporting rule; payroll then implements it. Do not transfer a health FSA change rule to an HSA simply because both deductions appear in the benefits section of the pay statement. Requests involving a different benefit type should follow that benefit's own eligibility and election review.
Leave with little or no pay
Ask two separate questions: what coverage must continue, and how will the employee's approved share be collected? For qualifying FMLA leave, group health coverage generally continues on the same terms as if the employee had continued working, while the employee normally remains responsible for their usual contribution. An unpaid check can therefore coexist with a continuing coverage obligation.
Benefits or leave administration should establish the applicable coverage and contribution arrangement. Payroll records what the check can actually collect. If a balance remains, identify the owner and period without treating it as an automatically authorized deduction from a later check. Other leave types require their own plan and legal review.
An unpaid premium is not permission for payroll to terminate coverage. FMLA rules address delinquent employee payments, including the grace period, advance written notice and reinstatement consequences. Route potential coverage termination to the authorized administrator; do not turn a payroll zero-net result into an automatic carrier stop.
Return from leave
Confirm the return date, coverage state and regular deduction restart together. Compare any prior balance with direct payments or earlier collections before proposing recovery. Separate the current contribution from the arrears installment, and require the appropriate approval for each. Check the first returning pay statement for both values, especially if pay frequency or the benefit year changed during leave.
Termination or reduced hours
HR supplies the employment event; benefits determines the affected coverage and continuation steps under the applicable arrangement. Payroll handles the approved final regular deduction and any separately authorized adjustment. The coordinator tracks the notice handoff independently of the final paycheck.
Federal COBRA, when applicable, creates duties for the employer, plan administrator and sometimes the employee or qualified beneficiary. DOL's employer guide explains qualifying events, loss of coverage and notice responsibilities. A termination record does not establish that a required election notice was sent. Confirm who performs that task, what starts the deadline and what evidence demonstrates completion; consider other applicable continuation requirements as well.
A carrier rejection or incorrect deduction
Assign the correction to the owner who can change the failing record. Benefits addresses an incorrect election or coverage record; payroll addresses the executed deduction; the integration owner addresses a mapping or delivery defect. The event coordinator keeps those tasks connected. Correcting the software connection should be followed by verification at the affected destinations before the ticket is finished.
Fix the missed deduction without inventing an election
Classify the problem before calculating a recovery. Was the election valid but not executed, was the approved amount wrong, or does the employee dispute the underlying coverage? These situations need different decision owners. Payroll should not create or backdate an election to make a previously processed check look consistent.
For a valid missed collection, benefits establishes the employee obligation for the relevant coverage periods and payroll establishes what was actually withheld. Include direct payments, refunds, reversals and earlier catch-up entries. Record any disputed portion separately so a total balance does not conceal an unresolved eligibility question.
Suppose the approved collection was $100 on each of two checks and neither check withheld it. The initial difference is $200. A confirmed $50 direct payment reduces the uncollected amount to $150. That arithmetic establishes a balance to review; it does not authorize taking $150 from the next check or decide whether the correction can be pretax.
Before recovery, obtain the authorized benefits decision, required employee authorization where applicable, payroll tax treatment and a collection schedule consistent with applicable wage-deduction rules. Escalate uncertain treatment to the employer's qualified adviser. Do not assume a current-year deduction code can repair every prior-year error. An overcollection likewise needs an approved refund and tax or reporting assessment rather than an unexplained negative deduction.
Keep correction authority proportionate to the problem. A routine implementation error can follow a documented approval path; a disputed election, threatened coverage loss, tax-year boundary or employee hardship needs additional review. A small amount still requires the applicable legal and plan treatment. A financial materiality threshold cannot waive a person's coverage or wage rights.
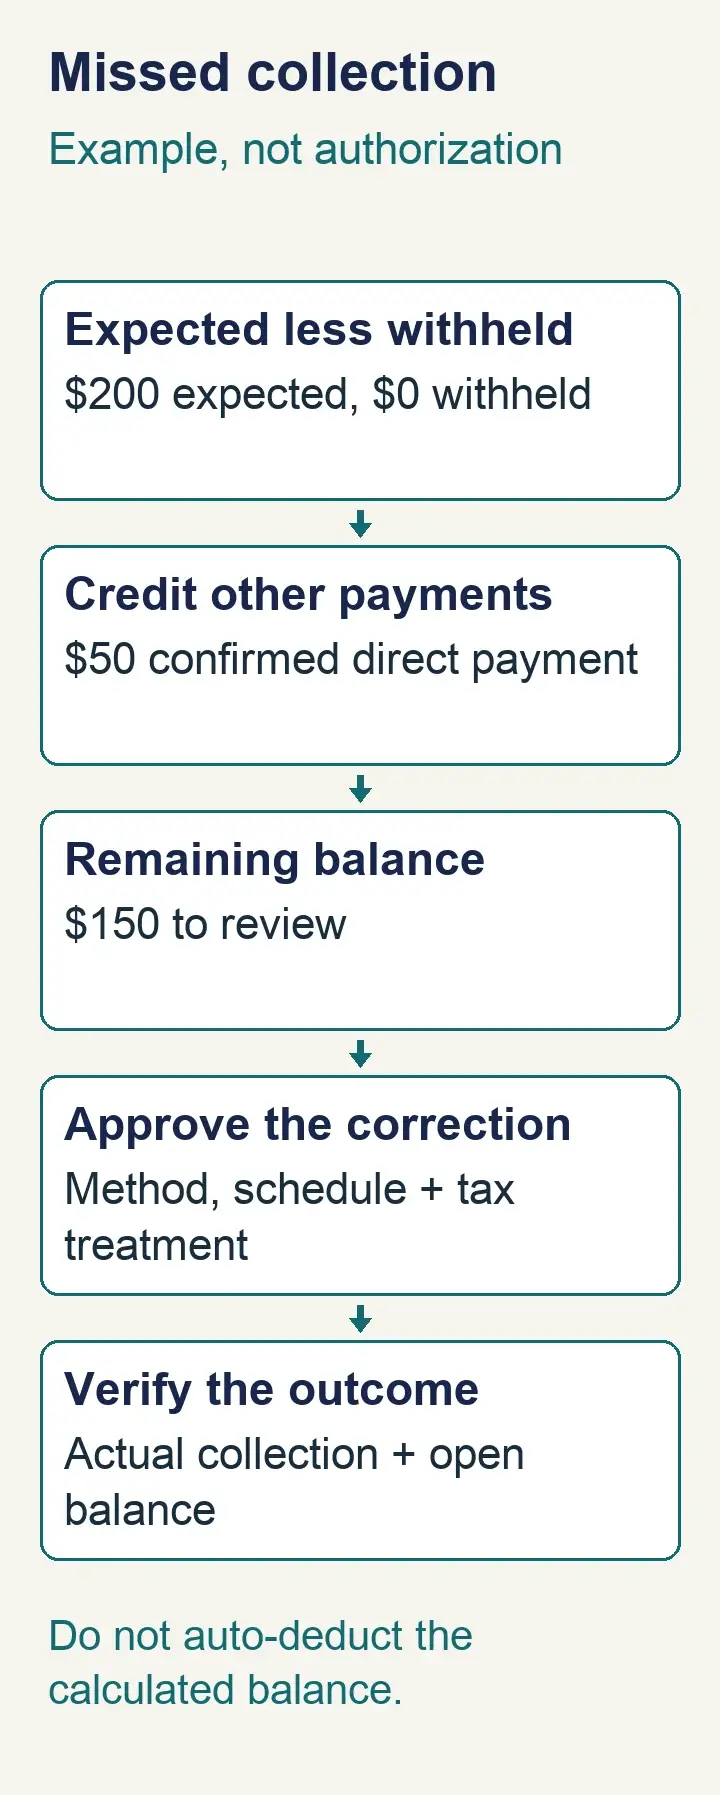
Calculate the difference first. Decide the lawful, approved correction separately from that arithmetic.
Use the Benefit Event Handoff Ticket
Create one ticket for an employee event, with related tasks for each affected benefit when their dates or owners differ. Copy the fields below as separate rows. Store sensitive evidence in an access-controlled location and link its reference; the ticket should not become an unrestricted folder of dependent or medical documents.
The ticket's coordinator is an operational role. The named benefits, payroll and notice decision owners retain their own authority. Use Pending decision, Accepted for execution, Partly verified or Complete to describe the work, and identify the remaining task whenever the event is partly verified.
Event identity and timing
1. Event reference: Employee ID, employing entity, benefit, event type and instruction version: ______.
2. Dates and deadlines: Event, request received, coverage start or end, approved election effective date, first affected check and applicable notice deadline: ______.
3. Coordinator and backup: Named person tracking the event, backup and next update time: ______.
Timing note: distinguish the plan or legal deadline from your earlier internal processing cutoff.
Authorized coverage decision
4. Benefits decision: Approved election, coverage tier, affected people, contribution schedule and decision owner: ______.
5. Supporting authority: Plan or approved rule reference, election evidence and any exception decision: ______.
6. Coverage or notice task: Receiving carrier or administrator, required action, responsible person and due date: ______.
Authority note: this ticket records an authorized decision; it does not create an election right or replace a required notice.
Accepted payroll work
7. Regular instruction: Deduction code, amount and basis, approved tax treatment, collection dates and recurring start or stop: ______.
8. Separate correction: Affected periods, expected collection, actual collection, direct payments or refunds, unresolved amount and authorized adjustment: ______.
9. Payroll acceptance: Receiving owner, accepted check date, expected recurring and one-time amounts, or rejection reason and resolver: ______.
Calculation note: reconcile direct payments and prior adjustments before authorizing another collection. Keep recurring and one-time amounts separate.
Verified outcomes and communication
10. Pay result: Preview reviewer, final check reference and verified deduction or adjustment result: ______.
11. Coverage and notice proof: Relevant membership confirmation, administrator receipt or required notice evidence; unresolved item and owner: ______.
12. Employee message: Sender, explanation of coverage and paycheck effects, message date and next promised update: ______.
13. Final disposition: State, remaining task and due date, independent reviewer where required, and completion evidence location: ______.
Completion note: mark Complete only when the event's required pay, coverage, notice and communication tasks are supported. Otherwise retain the specific open task and escalation.
Follow a family-coverage change across two pay runs
Consider a fictional employer with an approved twice-monthly collection schedule. An employee changes from employee-only to family coverage. Benefits has already confirmed the election and a November 1 coverage start; this example does not establish which real event permits a change or its required effective date.
The employee contribution rises from $120 to $240 a month, collected on two scheduled checks. The regular deduction therefore changes from $60 to $120. Payroll receives the approved instruction after the first November check was finalized with the old $60 amount. Benefits confirms that the full November employee share under this arrangement is $240.
Two old-rate deductions would collect only $120 for November, leaving a $120 difference. With the second regular deduction corrected to $120, total regular November collections become $180 and the remaining shortfall is $60. Keep those two scenarios distinct; collecting a $120 catch-up in addition to the corrected second deduction would overcollect.
The ticket can summarize the actual route in these worked rows:
1 and 4. Event and decision: Fictional case FAM-17, approved November 1 family coverage and $240 November employee share; benefits owner Maya.
9. Payroll acceptance: Luis accepts $120 recurring for the second November check, with the prior-check shortfall tracked separately.
8. Correction decision: First check collected $60; second regular collection will be $120; remaining $60 reviewed for a separately approved collection method and tax treatment.
11. Coverage proof: Carrier liaison confirms family membership effective November 1 and records the confirmation reference.
12. Employee update: Coordinator explains the new recurring deduction, the earlier shortfall and the proposed correction before it is executed.
13. Completion evidence: Final paycheck and coverage confirmation match the approved route; any unpaid balance stays open until settled or otherwise validly resolved.
If the second check also misses the change, reopen the payroll task and recalculate from actual collections. Do not reuse the earlier expected balance as if the planned correction had happened. Preserve the original instruction and record the new execution failure.
Tell the employee what changes next
Give the employee one contact who can coordinate the answer across functions. A useful message states what coverage has been confirmed, which check is affected, the regular deduction, any distinct correction and when the next update will arrive. Identify an unresolved question honestly instead of promising that a payroll edit guarantees coverage.
If a recovery is proposed, explain the relevant coverage periods, expected and actual collections, any direct payments credited and the proposed schedule. Provide a route for the employee to dispute the facts before an unapproved adjustment is processed. Required notices and authorizations still follow their applicable procedures; an informal ticket message does not replace them.
Limit what moves through the payroll queue. A payroll operator may need an employee identifier, benefit code, approved amount, dates and decision reference without needing detailed medical evidence. HHS distinguishes employment records from records held by a health plan or covered provider. Do not describe every HR record as HIPAA-protected, and do not treat that distinction as permission for unrestricted sharing. Apply the employer's other privacy obligations and access rules as well.
Review completed events and exceptions on different calendars
Review new or changed deductions around the first affected payroll. Review carrier responses according to the feed and administration schedule. Reconcile billed premiums, employer funding and employee collections for the relevant coverage period. Keeping these calendars separate lets a timely paycheck check coexist with a still-pending monthly invoice reconciliation.
During exception review, ask what action is due next and what employee consequence changes if it is missed. A possible coverage interruption or imminent notice deadline deserves attention before an older low-impact paperwork item. Preserve the original event date and missed commitments when an item changes owners.
For completed events, inspect a sample of actual evidence and recurring failure patterns. Count instructions rejected for missing facts, first-paycheck failures, carrier rejections, unconfirmed coverage and repeated correction attempts separately. These measures describe different weaknesses; combining them into a single completion percentage can hide the handoff that needs repair.
Retain the approved instruction, acceptance, affected pay result, coverage or notice proof and final communication under the appropriate retention and access policy. Keep later amendments connected to the original record. An employee inquiry after completion should reopen the affected conclusion with its new evidence rather than erase the earlier history.
Keep the model workable with a small team or outside service
One person may perform benefits and payroll tasks in a small employer. They can still record the authorized election, the separate pay instruction and the result. Arrange a second review for unusual corrections or decisions beyond that person's authority, using a qualified internal reviewer or the appropriate outside adviser. Do not invent an independent review that did not occur.
For outside administrators, describe the output you expect: an accepted enrollment change, a membership rejection resolved, a deduction scheduled or a required notice issued. Record how your team learns that the output is complete. A service desk ticket marked solved can mean a technical question was answered while the employee's coverage or paycheck problem remains open.
Read the agreement before assuming a broker, payroll service or benefits platform owns premium payment, employee communication or continuation notices. Software can move an instruction while leaving those tasks with the employer. ADP's public benefits material, for example, describes enrollment, carrier integration and payroll-related capabilities while noting that integrations vary by solution. Confirm the actual product and service scope your employer uses.
When the arrangement repeatedly fails, distinguish a missing process from a missing capability. Better instructions may solve a handoff problem. A required carrier connection, history report or exception workflow that the contracted service cannot provide may justify a different service scope. Assess that decision using specific failed cases and the work your staff would retain.
Test the handoffs when plans and systems change
Refresh the ownership map when contribution rates, deduction codes, plan years, administrators, interfaces or payroll schedules change. An unchanged employee election can still produce a wrong paycheck if a new collection calendar uses an old per-check amount. Preserve pending events and balances when transferring the work to another system or team.
Use a permitted test environment or a controlled review of representative records to examine an ordinary election, a late instruction, an unpaid-leave case, a return and a rejected carrier record. Define expected coverage and pay results before the review. Do not create fictitious elections or unnecessary deductions in a real employee's record to demonstrate a workflow.
Choose the first improvement from the failure your employees are experiencing. If approved elections miss pay, require payroll acceptance and a first-check comparison. If pay is correct but membership is uncertain, strengthen the carrier-response task. If employees receive inconsistent answers, assign the event coordinator and update commitment. Implement the smallest change that closes that observed gap, then verify it against actual outcomes.
Explore related payroll resources:

About the author
Ben Scott writes and maintains payroll decision guides for founders and operators. His work focuses on execution realities and how decisions hold up under growth, complexity, and controls and documentation pressure. He works hands-on in HR and leave-management roles that intersect with payroll-adjacent workflows such as benefits coordination, cutovers, and compliance-driven process controls.


