
No Tax on Overtime for Employers: Reconcile 2026 Pay to W-2 Code TT

Updated: 2 days ago

An employee sees $360 of overtime pay on a statement and expects payroll to report $360 as qualified overtime. For a covered, nonexempt employee working a straightforward time-and-a-half arrangement, that expectation can be wrong. Part of the $360 pays the regular rate for those hours. The amount required above that rate is the part payroll needs to isolate.
For 2026, employers report qualified overtime compensation in Form W-2 box 12 using Code TT. Build that amount from the applicable FLSA overtime calculation and the qualified compensation actually paid, then reconcile the employee's annual total to the form. Do not reduce reported wages or cap Code TT at the employee's potential personal deduction.
This guide is for U.S. employers organizing that reporting work, including payroll, HR and the person reviewing year-end forms. It provides fictional calculations, a reporting test plan and an Overtime Reporting Bridge you can copy. Wage-law coverage and special overtime methods require their own determination; an earnings-code label does not establish either.
Contents
Start with the 2026 reporting obligation
The employer's deliverable is a supported annual information return, even when the employee cannot ultimately deduct the entire amount. The IRS specifies Code TT for total qualified overtime compensation paid. Its August 2026 guidance expressly distinguishes that reported total from the deduction calculated on the employee's return.
Keep three amounts separate in your process: overtime wages paid, qualified overtime compensation reported, and the employee's allowable deduction. They answer different questions. A paycheck may label the whole time-and-a-half payment as overtime; Code TT generally captures the required premium above the regular rate; the return then applies individual limits and eligibility conditions.
Overtime generally remains subject to federal income tax withholding and employer and employee Social Security and Medicare taxes. A Code TT entry identifies the qualified amount for information reporting; it does not remove those wages from the ordinary payroll tax calculation.
The reporting obligation remains with the employer when a payroll service prepares the forms. Assign an internal owner to approve the Code TT reconciliation, a reviewer to resolve wage-calculation questions and a contact to receive employee correction requests. Ask the service which records it needs and who actually files a correction.
Do not continue using 2025 transition relief as your 2026 process. The IRS's current guidance requires separate reporting for 2026 and says the special 2025 relief does not extend to later years. A supplemental worksheet that helped explain 2025 pay does not replace the required 2026 Code TT entry.
Treat the current tax-year instructions as the release specification. The 2026 W-2 instructions give February 1, 2027 as the normal filing and employee-furnishing deadline. Put earlier internal dates on your reconciliation calendar so a rejected file, missing employee balance or unresolved calculation has an owner before release.
Identify the FLSA rule behind each premium
First establish whether the person is covered by the FLSA and nonexempt from its overtime requirement for the work in question. Salary status, a job title or an employer's decision to pay something called overtime does not by itself answer that question. Preserve the approved determination and its effective dates with the reporting population.
For the common section 7(a) calculation, use actual FLSA hours worked in a fixed workweek and the applicable regular rate. Do not average a busy week and a quiet week because they share a biweekly paycheck. Paid leave and hours worked are not interchangeable inputs to the ordinary calculation.
Create a separate review route for employees using another authorized section 7 method, such as certain hospital or public-safety arrangements. The IRS directs employers to the premium actually paid under the applicable alternative provision, rather than automatically recomputing every case under the ordinary over-40 formula. Federal employees covered by OPM rules also have specific guidance.
The same caution applies when a state rule, agreement or company policy generates additional premium pay. Do not mark every such dollar as qualified, and do not automatically discard it all. Determine which portion, if any, meets or is properly credited toward the applicable FLSA obligation. Record that analysis before deciding what enters Code TT.
An unresolved classification should appear as a named exception, with the affected workers and payroll runs identified. A temporary reporting category is useful for investigation, but it is not permission to postpone wages. Keep wage-payment decisions moving through the appropriate payroll and legal review while you resolve reporting treatment.
Separate overtime wages from the qualified premium
Consider a fictional employee covered by the ordinary FLSA overtime rule. The employee works 50 hours in one workweek at $24 per hour, with no other remuneration affecting the regular rate. All 50 hours are hours worked. The employer pays time and a half for the ten overtime hours.
The calculation is:
Straight-time compensation for all hours: 50 × $24 = $1,200.
Required additional overtime premium: 10 × $24 × 0.5 = $120.
Total weekly pay: $1,200 + $120 = $1,320.
The ten overtime hours paid at $36 total $360, comprising $240 of straight-time pay and $120 of premium.
If all that compensation is paid, $120 is the qualified overtime compensation from this workweek under the stated assumptions. The $360 overtime line is not the Code TT amount. The employee's personal deduction and tax savings are separate calculations, so neither should be printed as the promised result of this example.
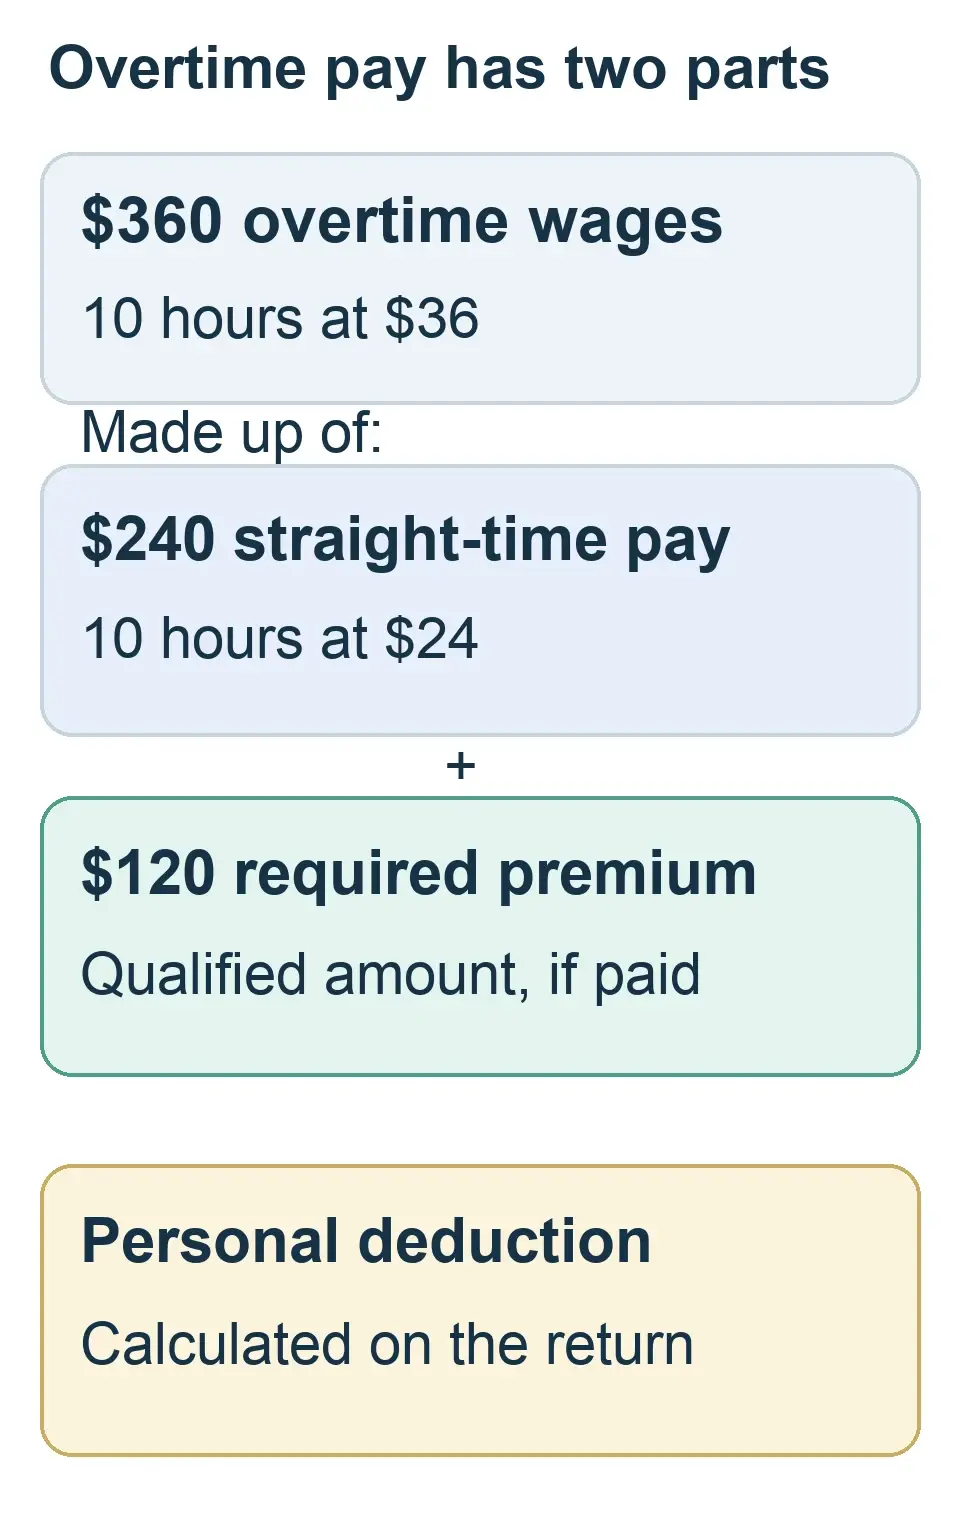
The qualified amount follows the required premium. The example assumes the ordinary over-40 rule, a $24 regular rate, no other remuneration and full payment.
Do not turn this example into a rule that divides every overtime bucket by three. That shortcut only reproduces the premium when the bucket actually contains the complete time-and-a-half payment at the correct regular rate. A system may store straight time and the premium in separate codes, or combine double time, retroactive adjustments and other pay in one report.
For example, if the same employee instead receives double time for those ten hours, the overtime wages are $480. Under these otherwise unchanged assumptions, the minimally required FLSA premium is still $120. The additional contractual payment does not turn the entire double-time premium into qualified compensation.
Document whether each earnings code contains all pay for overtime hours, only an additional premium, or a mixed result. Include the calculation reference and any exclusions. A code name such as OT1.5 is a useful clue, but you need a reproduced result to approve its reporting treatment.
Recalculate the regular rate when the underlying pay changes
The regular rate can differ from an employee's base hourly rate. Nondiscretionary bonuses and shift differentials can affect it, subject to the FLSA's exclusions and calculation rules. A reporting process that always multiplies base rate by one-half can therefore miss part of the required premium.
Extend the fictional example with a $120 nondiscretionary production bonus attributable entirely to that same 50-hour workweek. Assume the bonus must be included in the regular rate and there are no other relevant payments or exclusions. Straight-time wages of $1,200 plus the $120 bonus produce a $26.40 regular rate: $1,320 divided by 50.
The required premium becomes 10 × $26.40 × 0.5 = $132. Compared with the original $120 premium, another $12 is due. Total pay for the workweek, including the bonus and revised premium, is $1,452. The bonus itself is not all qualified overtime compensation; its effect on the required overtime premium is the reporting issue.
If the bonus arrives after the original paycheck, preserve the original workweek and the later payment reference. Show the additional premium separately from the bonus principal. A reviewer should be able to connect the $12 adjustment to the original $120 without adding the entire revised $132 to the original $120.
A bonus spanning multiple workweeks requires an appropriate allocation before the overtime adjustment is determined. Multiple rates, commissions, piecework and other arrangements also need their applicable wage calculation. Use a documented method and specialist review where necessary instead of applying this single-week example universally.
At a provider demonstration or configuration review, ask to see the original calculation, the later adjustment and the annual qualified-overtime total together. A corrected paycheck without a corrected reporting accumulator is an incomplete result. Record what you actually observed; a feature description is not evidence that your configuration passed.
Build an employee ledger by payment year
Keep the earned workweek and payment date as separate fields. The workweek supports the overtime calculation. The payment date supports the reporting year. The W-2 instructions generally base entries on wages paid during the calendar year, including their example of December work paid in January appearing on the following year's form.
For each qualified payment, retain the employee identifier, employing entity, workweek, calculation reference, payment date, run identifier and qualified amount. Add the earnings-code and mapping version needed to explain how that amount reached the annual accumulator. Restrict access to the detailed employee records.
Use a movement ledger that preserves the original entry and later adjustments. Identify whether a replacement supersedes an earlier result, adds a premium difference or corrects reporting only. Do not sum a final recalculated amount with the original amount it replaces.
For a simple fictional annual reconciliation, suppose supported qualified payments total $2,880 through September. October adds $360, November adds $240 and December adds $120, all paid in the same calendar year. The expected total is $3,600. If the W-2 preview shows $3,480, locate the missing $120 rather than adding an unexplained balancing line.
That difference could arise from a missing run, an unmapped code or a balance imported incompletely. The numbers alone do not identify the cause. Trace the employee, payment and source record before authorizing a correction, then rerun both the employee comparison and the employer-level total.
Handle prior-year payments, voids and recoveries with an explicit tax-year review. Do not assume that a negative entry in the current payroll accumulator fixes an earlier W-2, or that correcting Code TT necessarily changes wages or employment taxes. The required forms follow what was actually wrong.
Prove the mapping with cases that produce different answers
Ask the payroll service how it creates Code TT, which pay components feed the result and whether it needs historical data loaded separately. Obtain the configuration version and a sample report. There is no universal promise that every provider will reconstruct earlier workweeks from a current earnings code.
Build a test set around the arrangements you use. Include a straightforward hourly week, a week with no FLSA overtime, an included bonus, a differential or multiple-rate case, and a premium arising under a different rule. Add an authorized alternative-method case only if it belongs to your population, with the approved calculation.
For each case, write the expected wage result and qualified amount before comparing the system output. The zero case matters: a state-only premium in a week without an FLSA overtime obligation should not become qualified merely because it uses an overtime code. Conversely, a legally creditable premium needs its actual FLSA treatment evaluated rather than an automatic exclusion.
Test changes as movements. Add the later bonus adjustment, replace a run, reverse a duplicate import and include a payment crossing December into January. Reconcile the annual accumulator after each action. Preserve screenshots or exports that show the actual result, the reviewer and any unresolved difference.
Separate calculation acceptance from form acceptance. A qualified amount can be correct in an earnings report while a year-end export omits Code TT or places it in an informational box. Inspect the employee preview and the supported filing output for the relevant tax year. Ask how filing acceptance and rejected records will be monitored.
These are proposed employer tests, not a claim that HR Decision Guide has tested any named product. If your provider cannot demonstrate a required case, record the gap, owner and resolution date. Decide whether an approved supplemental process can produce the required reporting without treating an undocumented manual adjustment as a permanent solution.
Carry the qualified balance through a provider change
A midyear switch can preserve ordinary gross wages while losing the breakdown needed for qualified overtime reporting. Inventory the outgoing provider's available workweek support, paid qualified amounts, correction history and employee-level balances before access ends. Confirm who produces each required W-2 and how the two services coordinate.
Distinguish a historical balance loaded for reporting from wages newly processed by the receiving service. Identify its source period, entity, employee and paid year. A second import should not create a second payment or a second qualified amount.
Reconcile a selected employee across the outgoing closing report, incoming opening balance and later year-end preview. Then reconcile the full transferred population. Include a corrected employee and someone whose earlier qualified amount is zero, since missing and duplicated populations can hide behind a plausible aggregate total.
Make correction ownership part of the handoff. If an error originates in a workweek calculated by the former service but is discovered after conversion, identify who recalculates it, who changes the reporting balance and who files or furnishes the correction. Keep the original support accessible to the employer.
The appropriate W-2 filing arrangement depends on the facts, including the employing entity and any transaction or successor rules. Do not direct both services to issue overlapping forms merely to ensure that something is filed. Agree the arrangement with the responsible tax reviewer and reconcile the complete reporting population to it.
Give employees an explanation payroll can stand behind
Prepare one approved explanation that managers, HR and payroll can use. Start with what the employee sees, then explain what payroll reports and how to question it. Keep the correction contact visible instead of asking employees to interpret an unexplained number.
A reusable message is:
“Your overtime wages remain part of your pay. For 2026, we report qualified overtime compensation in box 12 of Form W-2 using Code TT. This generally represents the required FLSA premium above the regular rate, so it may differ from the overtime line on your pay statement. Your personal deduction depends on your tax return. If the reported amount appears incorrect, send payroll the pay dates and workweeks you want reviewed through our secure payroll contact route.”
Before using that message, replace the contact-route description with your actual secure channel and confirm that it reflects your approved calculation method. Provide a separate explanation for any population using special rules. Do not ask employees to email tax returns, full Social Security numbers or unrelated household financial details to a general inbox.
The deduction is available for tax years 2025 through 2028, subject to its conditions. The annual cap is $12,500, or $25,000 for a joint return, with reductions beginning above modified AGI of $150,000 or $300,000 respectively. Eligibility includes an employment-valid Social Security number, and married taxpayers generally must file jointly. Those return-level limits do not reduce the employer's total Code TT reporting.
Withholding is a separate conversation. Do not switch off withholding on an overtime code. The IRS says an employer may not reduce withholding for the expected deduction unless the employee supplies an updated valid Form W-4 accounting for it. The 2026 form provides for expected qualified overtime in its Step 4(b) deductions worksheet.
Direct employees to the current W-4 instructions or IRS estimator when they want to consider a withholding adjustment. Payroll should process a valid form through its normal controls rather than prescribe a deduction using one employer's wage history alone. State or local treatment also needs the applicable jurisdiction's guidance; the federal deduction does not establish it.
Correct Code TT errors without sending the problem back to the employee
Create a correction intake that records the employee's question, relevant pay dates, workweeks and the amount shown on the furnished form. A difference between an overtime-pay line and Code TT is not automatically an error, but it deserves a reproducible explanation rather than a generic reply.
Review the coverage decision, regular-rate calculation, credited premiums, payment history and mapping. Classify the result as an explained difference, an incorrect qualified amount, a wage error, or a combination. Keep the wage correction and reporting correction connected while giving each its proper processing route.
When an employer discovers a Code TT error, the IRS requires filing Form W-2c with SSA and furnishing it to the employee as soon as possible. Assign the filing owner, verify the corrected employee statement and retain evidence of delivery and filing disposition. A provider support ticket by itself does not establish that either action occurred.
Do not tell an employee with an omitted or understated 2026 amount simply to estimate a larger deduction from pay stubs. The current IRS guidance requires the properly reported amount and directs the employee to request a W-2c. It also says Form 4852 does not satisfy the statement requirement for this deduction.
An overstatement does not entitle the employee to use an amount that was never qualified compensation paid. Explain that the tax return still has to use the correct underlying amount and give the employee the corrected information promptly. Personal return questions belong with the employee's tax adviser; employer reporting corrections remain the employer's work.
Do not decide a small Code TT error can be ignored because its dollar value falls below an internal tolerance. The specific reporting requirement still applies. Use internal priorities to organize investigation and escalation, with an owner and due date, rather than convert a workflow threshold into a legal exception.
Use the Overtime Reporting Bridge
Copy this record into your controlled payroll workspace. Complete groups A and B for each workweek or adjustment requiring review. Complete group C once for the employee's reporting-year reconciliation, referencing the underlying rows. The annual total must not be added repeatedly from each weekly record.
Use employee IDs and restricted evidence links rather than placing sensitive details in a broadly shared worksheet. The record supports the employer's calculation and reporting review; it is not an employee tax-return calculator or a substitute for a coverage determination.
A. Establish the workweek basis
1. Employee and employer: Record the employee ID, employing entity and reporting year being reviewed.
2. Applicable rule: Identify the FLSA coverage and overtime method, determination owner, effective dates and evidence reference.
3. Workweek boundaries: Enter the start and end, including the time boundary used by the approved calculation.
4. Hours and threshold: Record FLSA hours worked and the threshold applicable to this employee's approved overtime method.
5. Regular-rate support: Reference included remuneration, exclusions, allocation and the approved regular-rate calculation.
Group A note: a paycheck period may contain more than one workweek. Preserve each required calculation separately.
B. Follow the premium into payment
6. Required premium: Enter the premium required by the applicable method, with the calculation reference and reviewer.
7. Credited and additional premiums: Explain any legally creditable premium and additional amount needed to satisfy the FLSA obligation.
8. Qualified amount paid: Record the supported qualified portion actually paid, its payment date and payroll run identifier.
9. Other premium pay: Identify amounts excluded from qualified compensation and the reviewed reason, without deleting their wage history.
10. Adjustment movement: For a correction, record the original amount, replacement or additional amount, difference and affected paid year.
11. Reporting route: Identify the earnings-code mapping version, reporting accumulator and source-row reference.
Group B note: preserve superseded entries. Add only the supported movement once; do not count an original premium and its full replacement together.
C. Release the employee's annual amount
12. Annual bridge: Reconcile the opening supported balance, subsequent qualified payments and reviewed adjustments to the expected annual total.
13. W-2 comparison: Record the Code TT preview amount, expected amount and any difference for this employee and paid year.
14. Exception resolution: Name the unresolved issue, responsible reviewer, action date and effect on reporting or wages.
15. Form and filing outcome: Identify the released W-2 or W-2c version, employee-furnishing evidence and filing acceptance or rejection status.
16. Employee response and approval: Record the explanation or correction supplied, approval owner and final evidence location.
Group C note: the employer-level total should agree to the sum of approved employee totals. A matching total does not excuse unresolved individual differences.
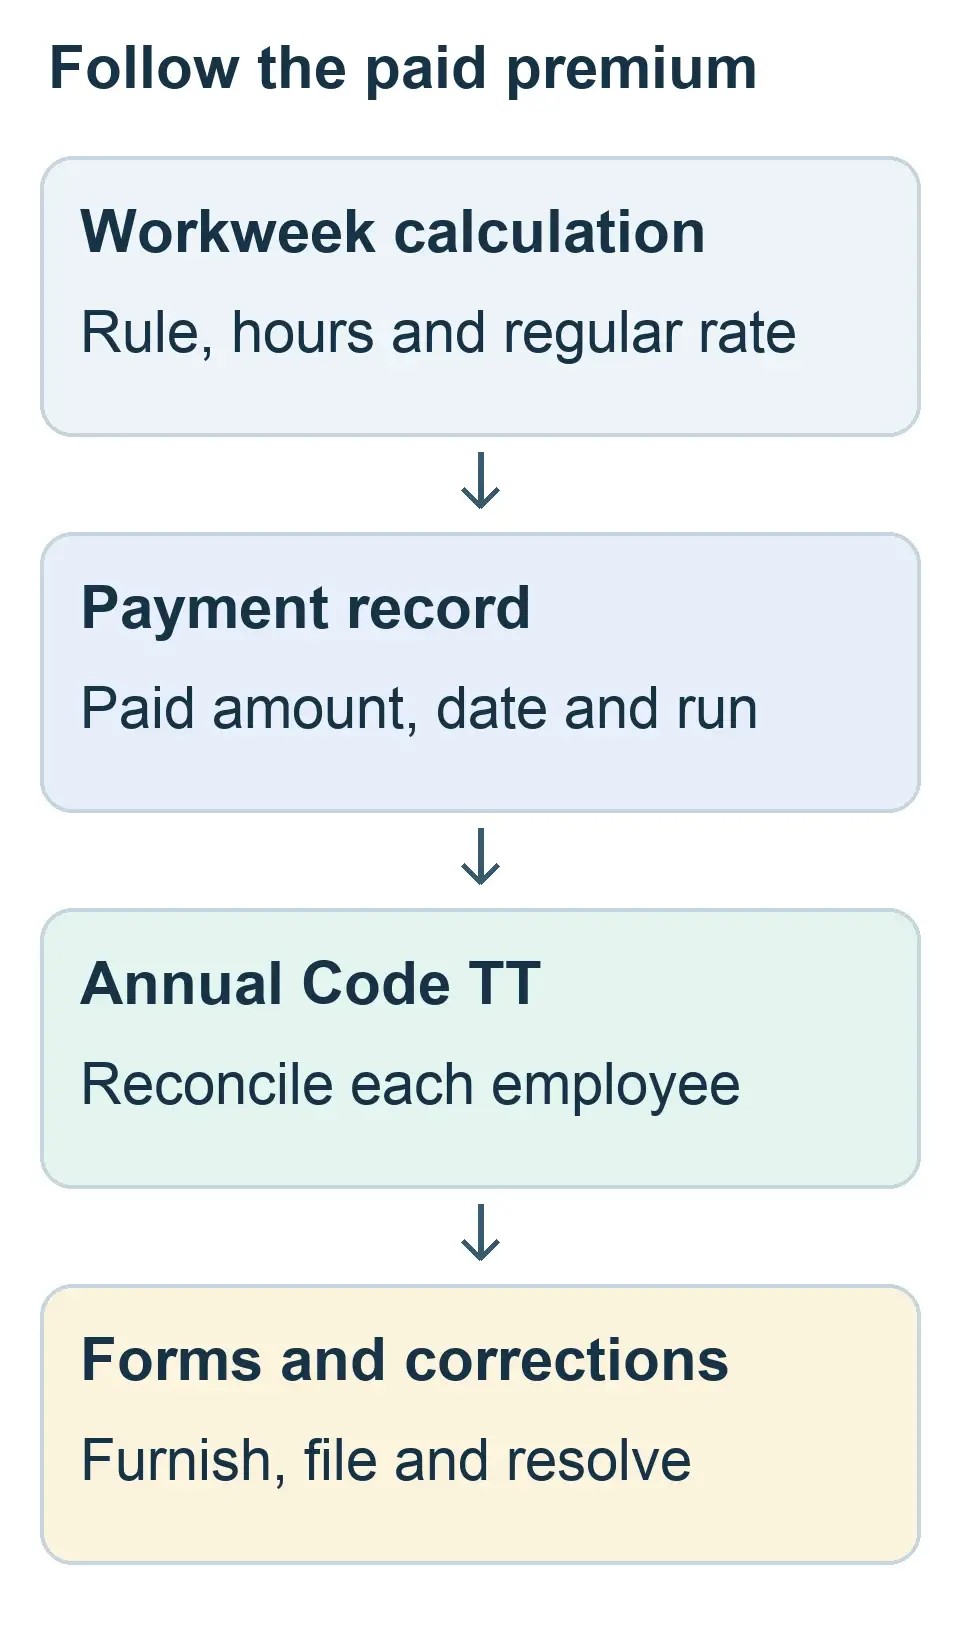
Review both the calculation and the delivery. A correct accumulator is not evidence that the correct employee statement was furnished or the filing accepted.
Finish one employee before approving the population
Choose an employee whose history includes an actual overtime payment and a later change, if one exists. Reconstruct the applicable workweek result, follow the paid qualified amount into the annual balance and compare it with the tax-year form preview. Record the outcome in the bridge before expanding the review.
Then use your population reports to identify employees, codes or runs missing from the same route. Investigate unexpected zeros, large changes and differences between the ledger and forms. Apply the resolved mapping consistently, while retaining individual exceptions that need a separate decision.
Before release, confirm that the employer can reproduce each reported total, explain the difference from an overtime-pay line and carry a correction through to the employee and filing system. That is the evidence payroll needs when the first Code TT question arrives.
Explore related payroll resources:

About the author
Ben Scott writes and maintains payroll decision guides for founders and operators. His work focuses on execution realities and how decisions hold up under growth, complexity, and controls and documentation pressure. He works hands-on in HR and leave-management roles that intersect with payroll-adjacent workflows such as benefits coordination, cutovers, and compliance-driven process controls.


